
Big Data and Business Analytics Market Report Scope & Overview:
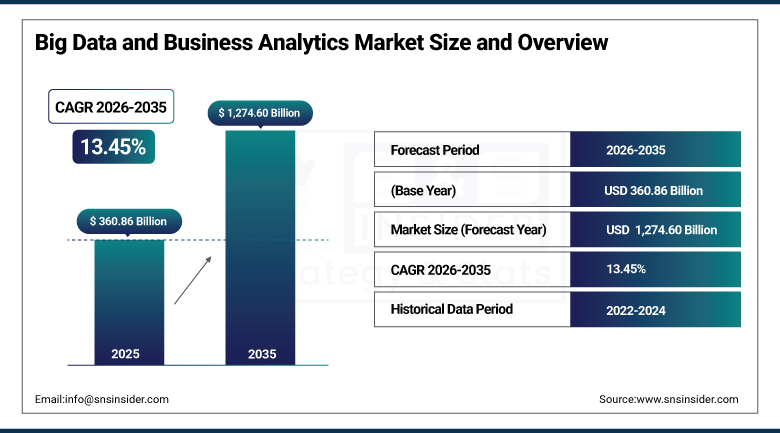
The Big Data and Business Analytics Market was valued at USD 360.86 Billion in 2025 and is expected to reach USD 1,274.60 Billion by 2035, growing at a CAGR of 13.45% from 2026-2035.
Big data and business analytics is used to describe the technologies, platforms, and services which gather, analyze, and process big and diverse sets of data for business purposes. Businesses apply these solutions for customer insight, supply chain management, fraud detection and more. The transition from descriptive analysis to predictive and prescriptive insights is extending the scope of application even further. The growth drivers include increasing amounts of data from Internet-connected devices and digital communications channels, fast adoption of cloud-based data platforms, as well as the use of artificial intelligence and machine learning in analytics applications. Skills shortage and data privacy legislation remain problems, but the high price of not using data to make business decisions is keeping investments strong.
In September 2024, Oracle Corporation introduced new HeatWave capabilities that allow customers to run machine learning and lakehouse applications securely, using generative AI on both Amazon Web Services and Oracle Cloud Infrastructure. The launch improved manageability and performance of transactional and analytical workloads on a single platform.
To Get more information On Big Data and Business Analytics Market - Request Free Sample Report
Big Data and Business Analytics Market Trends
-
Rising convergence of analytics platforms with generative AI and machine learning services.
-
Growing adoption of cloud data platforms and lakehouse architectures replacing on-premises warehouses.
-
Expanding use of self-service analytics that puts insight directly in the hands of business users.
-
Increasing demand for real-time processing to support fraud detection and personalised customer engagement.
-
Rising emphasis on data governance, semantic standards, and secure access for autonomous AI agents.
-
Growing consolidation as platform vendors acquire startups in migration, observability, and cataloguing.
U.S. Big Data and Business Analytics Market Overview
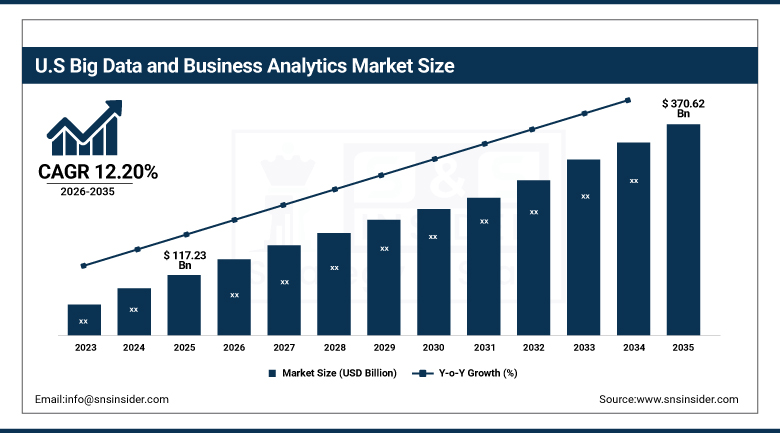
The U.S. Big Data and Business Analytics Market was valued at USD 117.23 Billion in 2025 and is expected to reach USD 370.62 Billion by 2035, growing at a CAGR of 12.20% from 2026-2035.
The U.S. Big Data and Business Analytics Market is the largest national market in the world, supported by an early and broad base of cloud adopters, a large concentration of technology vendors, and heavy analytics spending in financial services, healthcare, retail, and government. Enterprises across the country are consolidating fragmented data estates onto cloud platforms and layering machine learning and generative AI on top, which is lifting demand for data management, integration, and governance tools. Federal and state programs increasingly rely on analytics for fraud detection, public health surveillance, and program management. Competition among hyperscale cloud providers and independent data platform vendors is intense, and it is producing rapid product releases, strategic partnerships, and acquisitions.
On June 6, 2025, Snowflake Inc. acquired Crunchy Data Solutions, an organization that deals with PostgreSQL technology, at a value of USD 164.5 million in cash. This acquisition enabled the development of an operational database within the Snowflake platform.
Big Data and Business Analytics Market Segment Analysis
-
By Component, the Software segment dominated the market with a 61.40% share in 2025, while the Services segment is the fastest growing with a CAGR of 14.80% during 2026-2035.
-
By Deployment, the Cloud segment dominated the market with a 63.70% share in 2025, while the Hybrid segment is the fastest growing with a CAGR of 16.10% during 2026-2035.
-
By Analytics Tool, the Dashboard & Data Visualization segment dominated the market with a 33.20% share in 2025, while the Self-Service Tools segment is the fastest growing with a CAGR of 15.40% during 2026-2035.
-
By Application, the Customer Analytics segment dominated the market with a 29.80% share in 2025, while the Marketing Analytics segment is the fastest growing with a CAGR of 15.70% during 2026-2035.
-
By End-Use Industry, the BFSI segment dominated the market with a 24.90% share in 2025, while the Healthcare segment is the fastest growing with a CAGR of 15.30% during 2026-2035.
By Component, Software Dominates the Market and Services Grows Fastest
Software dominated the market in 2025. Data management, integration, business intelligence, and advanced analytics platforms form the core purchase for nearly every organisation building an analytics capability, and they carry the largest licence and subscription value. Vendors continue to add machine learning, natural language querying, and automated data preparation to their products, which encourages upgrades and expanded seat counts. The shift to cloud subscription pricing has also broadened the customer base by lowering the entry cost for mid-sized firms, keeping software firmly at the centre of spending.
Services is expected to be the fastest-growing component over the forecast period. Implementation, integration, managed analytics, and consulting work are in strong demand because many enterprises lack the engineers and data scientists needed to build and run modern data platforms. Migration from legacy warehouses to cloud environments, along with the governance work required for AI adoption, generates long, multi-stage engagements. Providers of managed services benefit as buyers prefer to outsource day-to-day operations.
By Deployment, Cloud Dominates the Market and Hybrid Grows Fastest
Cloud deployment dominated the market in 2025. Elastic storage and compute allow organisations to scale analytics workloads up and down with demand, avoid large hardware investments, and reach new capabilities faster than on-premises software cycles allow. Leading cloud providers and independent data platforms have built integrated services for ingestion, warehousing, machine learning, and visualisation, making the cloud the default environment for new projects. Its pay-as-you-go economics are attractive to firms of every size.
Hybrid deployment is projected to be the fastest-growing model over the forecast period. Many regulated enterprises must keep sensitive data on premises or in private environments while still using public cloud analytics for scale, and they need consistent governance across both. Hybrid architectures, supported by open table formats and federated query engines, let firms move workloads gradually and avoid lock-in. As data sovereignty rules tighten in several regions, hybrid setups are gaining ground.
By Analytics Tool, Dashboard & Data Visualization Dominates the Market and Self-Service Tools Grows Fastest
Dashboard and data visualisation tools dominated the market in 2025. They are the most widely deployed layer of the analytics stack, turning large data sets into charts and scorecards that executives and operational teams use every day. Their appeal lies in immediate, easily understood output and integration with almost every data source. Vendors have enhanced them with natural language search, automated insight suggestions, and embedded analytics inside business applications.
Self-service tools are expected to be the fastest-growing category over the forecast period. Organisations want business users to explore data without waiting for specialist teams, which relieves pressure on scarce analysts and shortens the time from question to decision. Drag-and-drop preparation, governed data catalogues, and conversational interfaces make these tools accessible to non-technical staff. Growth is further supported by demand for consistent semantic definitions that keep metrics aligned across departments.
By Application, Customer Analytics Dominates the Market and Marketing Analytics Grows Fastest
Customer analytics dominated the market in 2025. Companies in retail, banking, telecommunications, and insurance rely on it to segment customers, predict churn, personalise offers, and measure lifetime value. The volume of behavioural data captured through digital channels gives these programs rich material, and the link between customer insight and revenue makes them an early priority for analytics budgets. Mature use cases and proven returns support a steady flow of investment.
Marketing analytics is projected to be the fastest-growing application over the forecast period. The demand for hyper-personalization, real-time optimization of campaigns, and reliable attribution on more and more fragmented digital platforms is pushing towards its usage. Predictive models and generative AI are being used by marketers in order to allocate budgets and create content, and limitations to third-party tracking due to changes in privacy policy make first-party data analysis even more relevant.
By End-Use Industry, BFSI Dominates the Market and Healthcare Grows Fastest
BFSI dominated the market in 2025. Banks, insurers, and asset managers generate huge transaction volumes and face strict requirements for risk management, fraud detection, credit scoring, and regulatory reporting, all of which rely on advanced analytics. The sector has long invested in data infrastructure and has the budgets to adopt new platforms quickly. Real-time fraud monitoring and personalised financial products keep spending high.
Healthcare is expected to be the fastest-growing end-use industry over the forecast period. Providers, payers, and life sciences companies are using analytics to improve patient outcomes, reduce costs, detect billing fraud, and speed research, drawing on electronic records, imaging, and genomic data. Value-based care models and population health programs increase the need for predictive insight, and the growing adoption of AI in clinical and operational workflows adds further momentum.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
86.40% |
|
Europe |
Germany |
25.90% |
|
Asia Pacific |
China |
42.30% |
|
Latin America |
Brazil |
43.70% |
|
Middle East & Africa |
United Arab Emirates |
21.40% |
North America Big Data and Business Analytics Market Insights
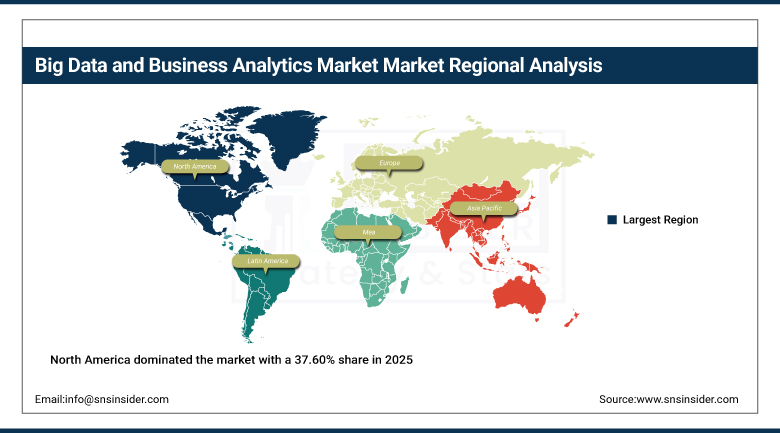
North America dominated the market with a 37.60% share in 2025. Early adoption of cloud computing, artificial intelligence, and machine learning, together with a dense concentration of technology vendors and data-intensive industries, underpins the region's lead. Financial institutions, government agencies, and healthcare organisations are major buyers, and venture funding keeps a steady stream of new analytics companies entering the market.
Canada adds demand through its banking, energy, and public sectors, supported by a growing artificial intelligence research community. Continued platform consolidation, AI integration, and heavy enterprise investment are expected to keep North America in front through the forecast period, although its growth rate will trail Asia Pacific, where digital infrastructure is expanding from a smaller base.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Big Data and Business Analytics Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 16.40% during 2026-2035. Rapid digital transformation, expanding industrialization, rising cloud investment, and government-led digital programs are accelerating analytics adoption. Businesses across the region are generating large volumes of data from e-commerce, mobile payments, and manufacturing sensors, and they are moving quickly to convert it into commercial insight.
China anchors regional demand with heavy investment in digital infrastructure, cloud ecosystems, and AI-powered business tools. Japan contributes mature enterprise demand, while India is a fast-growing market supported by a large IT services sector and expanding digital public infrastructure. South Korea and Southeast Asian economies add further momentum as firms adopt cloud platforms.
Europe Big Data and Business Analytics Market Insights
Europe commands a substantial portion of the market owing to its adoption of cloud, growing data usage in telecommunication and health care sectors, and rising government expenditure on analytics-based tools. Approximately seven out of ten businesses from the region have started their shift towards the cloud and adopt a cloud-first strategy. The industrial and manufacturing analytics-based investments of Germany have been driving regional demand.
The United Kingdom and France add consistent demand from financial services and retail. Strict data protection rules, including the General Data Protection Regulation, shape how platforms are designed and increase demand for governance and privacy tools. Interest in sovereign cloud options is also rising, giving regional providers an opening alongside global vendors.
MEA & Latin America Big Data and Business Analytics Market Insights
The Middle East & Africa region is supported by national digital strategies in the United Arab Emirates and Saudi Arabia, where governments are investing in smart cities, data centres, and artificial intelligence. Banks and telecommunications operators are early adopters, and public sector agencies are building analytics capacity to support planning and service delivery.
Latin America has Brazil as its main driver with a significant financial services industry and an emerging e-commerce sector maintaining a continuous need for analytics software. Mexico has potential growth in the areas of banking, retail, and manufacturing. Lack of skills and infrastructure hinders adoption in other nations; however, cloud computing is becoming increasingly accessible.
Growth Drivers: Data Growth, Cloud Migration, and AI Integration
The rapid growth in data volumes is the primary driver. Connected devices, digital transactions, social platforms, and industrial sensors generate information at a scale that manual analysis cannot handle, and organisations that can turn it into insight gain clear advantages in cost, speed, and customer understanding. This pressure pushes enterprises of every size to invest in platforms that can store, process, and analyze data reliably.
Cloud migration and the integration of artificial intelligence form a second major driver. Cloud data platforms lower the cost of scaling analytics, while machine learning and generative AI extend what analysts can do, from automated forecasting to natural language queries. Rising demand for real-time insight, particularly in finance, retail, and telecommunications, reinforces spending and keeps vendors investing heavily in new capabilities.
Restraints: Data Privacy Regulation and Skills Shortages
Data privacy laws are yet another major constraint. There exist different regulations for the processes of data collection, storage, and sharing which are stricter in comparison to other regulations. This adds to the cost and reduces the amount of data that can be used. The process of setting up governance, consent management, security frameworks, and sharing of data across borders is a complex one.
Constraints also arise from skill shortages. Data engineers, scientists, and analysts remain in short supply, and many organisations struggle to recruit or retain them. Projects can stall for lack of expertise, and the cost of talent adds to total project budgets. Vendors are responding with low-code tools and managed services, though the gap remains a brake on adoption.
Opportunities: Agentic AI and Industry-Specific Analytics
AI agents asking questions, understanding, and acting on corporate data present a major opportunity. Suppliers of AI agents can gain new revenues when companies expand from pilots to deployments because of their capabilities to govern access, add semantics, and establish connections safely for these agents. This increases the strategic importance of data platforms as the basis of AI.
Analytics in specific industries also presents another opportunity for growth. Some of the specific solutions that can be suggested for health care sector, manufacturing sector, retail sector, and financial sectors include elements specific to those sectors, thus leading to effective implementation and return on investment of the solutions. There would also arise some opportunities in developing countries due to the better digital infrastructure available to them.
Recent Developments:
-
2026: Microsoft Corporation expanded Microsoft Fabric with additional data, analytics, and AI capabilities, strengthening its unified platform for enterprise data engineering, business intelligence, and AI workloads.
-
2026: International Business Machines Corporation introduced Agentic Data Intelligence in watsonx.data intelligence for self-managed environments, enabling AI agents to access trusted enterprise data, governance, and business context.
-
2026: SAP SE introduced the SAP Autonomous Enterprise and unified Business AI Platform, integrating AI agents with enterprise data, workflows, governance, and business processes to support automated decision-making.
Big Data and Business Analytics Market Key Players are:
-
Amazon Web Services, Inc.
-
Microsoft Corporation
-
International Business Machines Corporation
-
SAP SE
-
SAS Institute Inc.
-
Google LLC
-
Teradata Corporation
-
Cloudera, Inc.
-
Snowflake Inc.
-
Databricks, Inc.
-
Salesforce, Inc. (Tableau)
-
Alteryx, Inc.
-
Cisco Systems, Inc. (Splunk)
-
Hewlett Packard Enterprise Development LP
-
Informatica LLC
-
Strategy Incorporated (MicroStrategy)
-
Palantir Technologies Inc.
-
Cloud Software Group (TIBCO)
Big Data and Business Analytics Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 360.86 Billion |
| Market Size by 2035 | USD 1,274.60 Billion |
| CAGR | CAGR of 13.45% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Hardware, Software, Services) • By Deployment (Cloud, On-Premises, Hybrid) • By Analytics Tool (Dashboard & Data Visualization, Self-Service Tools, Data Mining & Warehousing, Others) • By Application (Customer Analytics, Supply Chain Analytics, Marketing Analytics, Risk & Credit Analytics, Workforce Analytics, Others) • By End-Use Industry (BFSI, Healthcare, Retail & E-Commerce, Telecommunications, Manufacturing, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amazon Web Services, Inc., Microsoft Corporation, International Business Machines Corporation, Oracle Corporation, SAP SE, SAS Institute Inc., Google LLC, Teradata Corporation, Cloudera, Inc., Snowflake Inc., Databricks, Inc., Salesforce, Inc. (Tableau), Qlik Technologies, Alteryx, Inc., Cisco Systems, Inc. (Splunk), Hewlett Packard Enterprise Development LP, Informatica LLC, Strategy Incorporated (MicroStrategy), Palantir Technologies Inc., Cloud Software Group (TIBCO). |

Frequently Asked Questions
Key players include Amazon Web Services, Inc., Microsoft Corporation, International Business Machines Corporation, Oracle Corporation, SAP SE, and SAS Institute Inc., among other technology vendors.
Governed data foundations for AI agents and industry-specific analytics solutions represent the primary opportunities for vendors.
Growth is primarily driven by rapid growth in data volumes, cloud migration, and the integration of artificial intelligence into analytics.
By Component, Software dominated the market with a 61.40% share in 2025, reflecting its role as the core purchase for analytics programs.
North America dominated the market with a 37.60% share in 2025, supported by early cloud and AI adoption and a dense base of technology vendors.
