
Big Data in Flight Operations Market Report Scope & Overview:
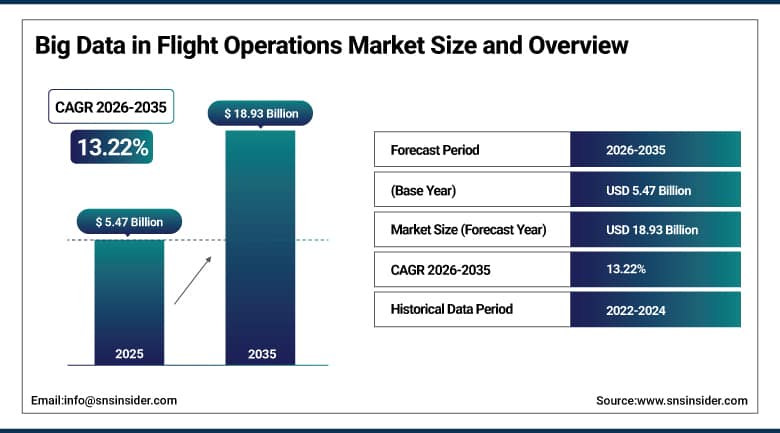
The Big Data in Flight Operations Market was valued at USD 5.47 Billion in 2025 and is expected to reach USD 18.93 Billion by 2035, growing at a CAGR of 13.22% from 2026-2035.
The Big Data in Flight Operations Market is expanding as airlines, airports and maintenance providers turn the large volumes of data generated by aircraft, crews and ground systems into operating decisions. Modern aircraft produce continuous streams from engines, avionics and flight management systems, and these streams are combined with weather, air traffic, fuel and passenger data. Analytics platforms use the information to plan routes, reduce fuel burn, anticipate component failures and recover quickly from disruption. Cloud platforms and artificial intelligence are lowering the cost of processing, while record passenger demand raises the value of every efficiency gain. Competition among aircraft makers, avionics suppliers and software vendors is increasing. North America is the largest region, while Asia Pacific is expected to grow fastest.
⮞In January 2026, the International Air Transport Association reported that global passenger demand rose 5.3% in 2025 and that the industry load factor reached a record 83.6%. Fuller aircraft and busier networks increase the operational value of data-driven planning.
To Get More Information On Big Data in Flight Operations Market - Request Free Sample Report
Big Data in Flight Operations Market Trends
-
Airlines are moving flight planning, crew and maintenance analytics to shared cloud platforms.
-
Predictive maintenance is using engine and component data to cut unscheduled removals and delays.
-
Generative artificial intelligence assistants are being added to operations control and disruption recovery.
-
Aircraft makers are offering data platforms that connect fleets, suppliers and maintenance providers.
-
Fuel and emissions analytics are becoming central to route optimization and sustainability reporting.
U.S. Big Data in Flight Operations Market Outlook
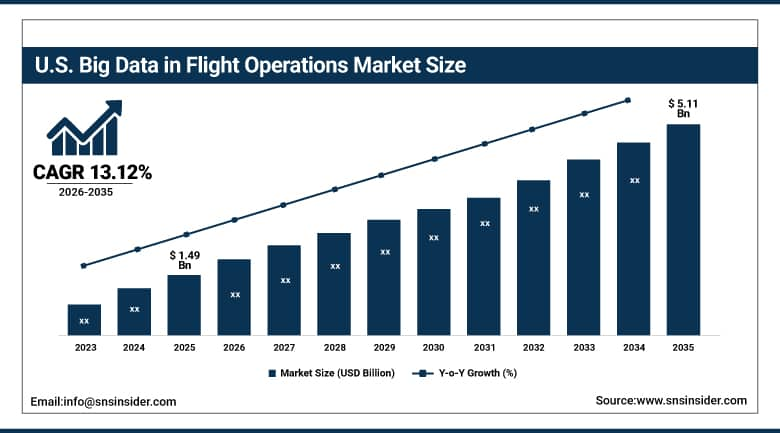
The U.S. Big Data in Flight Operations Market was valued at USD 1.49 Billion in 2025 and is expected to reach USD 5.11 Billion by 2035, growing at a CAGR of 13.12% from 2026-2035.
The U.S. Big Data in Flight Operations Market is the largest national market, shaped by low-cost airlines, cargo operators and a base of aerospace suppliers and technology companies. Airlines use analytics for flight planning, crew scheduling, fuel management and irregular operations recovery, and large fleets create the data volume that makes advanced models effective. Maintenance providers apply predictive tools to engines and airframes, and airports use data to coordinate gates, baggage and ground handling. Federal programs to modernize air traffic control are expected to widen the data available for planning, and carriers are partnering with cloud providers to analyze it. Growth is steady, supported by high passenger volumes, strong spending on technology and the willingness of large carriers to test new applications early.
⮞In July 2025, the U.S. Department of Transportation and the Federal Aviation Administration announced USD 12.50 billion in initial funding to modernize air traffic control systems, with a total need estimated at USD 31 billion. The program is expected to improve data exchange between airlines, airports and controllers.
Big Data in Flight Operations Market Segment Analysis
-
By Component, the Software segment dominated the Big Data in Flight Operations Market with approximately 64.80% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 15.37%.
-
By Deployment, the Cloud-Based segment dominated the Big Data in Flight Operations Market with approximately 68.00% share in 2025, and is also the fastest growing with a CAGR of approximately 14.62%.
-
By Application, the Flight Operations Optimization segment dominated the Big Data in Flight Operations Market with approximately 35.00% share in 2025, while the Predictive Maintenance segment is the fastest growing with a CAGR of approximately 15.84%.
-
By End User, the Airlines segment dominated the Big Data in Flight Operations Market with approximately 56.40% share in 2025, while the MRO Providers segment is the fastest growing with a CAGR of approximately 15.21%.
By Component, Software Dominates the Big Data in Flight Operations Market and Services Grows Fastest
Software accounts for the larger share because analytics platforms, data pipelines, visualization tools and machine learning models form the core of every deployment. Airlines license flight planning, fuel optimization, crew management and maintenance analytics products that integrate with flight operations systems, and they pay recurring fees as usage expands. Aircraft makers and avionics suppliers bundle data applications with fleet delivery, which embeds their platforms early. Vendors continually add features such as disruption forecasting and carbon tracking, and the software layer captures most of the value generated from the data, which keeps competition focused on model accuracy and ease of integration.
Services are growing fastest because airlines often lack the data engineering and analytics talent to design, integrate and operate large platforms. Consulting, implementation, training and managed analytics services help carriers connect legacy systems, cleanse data and build models tuned to their networks. Providers also run continuous monitoring and optimization for clients that prefer to outsource. As cloud migration accelerates and artificial intelligence projects move from pilots to production, demand for integration and support rises, and long-term service contracts offer vendors predictable revenue alongside software licenses, while managed services help airlines scale analytics teams quickly.
By Deployment, Cloud-Based Dominates the Big Data in Flight Operations Market and Also Grows Fastest
Cloud-based deployment leads because flight operations data is large, constantly updated and needed by many teams across several locations. Cloud platforms scale on demand, support real-time streaming and make it simple to share information among flight dispatch, maintenance, crew and airport teams. Carriers avoid the capital cost of data centers and benefit from frequent updates and strong security tools. Aircraft makers host fleet data platforms in the cloud, which allows operators to compare performance across airlines and benefit from collective learning on component behavior, which improves the accuracy of failure forecasts across fleets.
The cloud segment is also growing fastest as airlines retire legacy systems and adopt platforms offered by technology providers and aerospace suppliers. Hybrid arrangements are common, with sensitive or latency-critical functions kept close to operations while analytics run in the cloud. Providers address data sovereignty and cybersecurity concerns through regional hosting and certification. Pay-as-you-go pricing helps smaller airlines and regional carriers start with limited budgets, and artificial intelligence services delivered through the cloud shorten the path to new analytics capabilities, helping carriers move from small pilots to fleet-wide use.
By Application, Flight Operations Optimization Dominates the Big Data in Flight Operations Market and Predictive Maintenance Grows Fastest
Flight operations optimization holds the largest share because fuel, crew and aircraft are the biggest costs for an airline, and even small improvements in planning produce significant savings. Analytics refine route selection, altitude and speed profiles, fuel loading and takeoff weight, and they support dynamic scheduling when weather or congestion disrupts the network. Operations control centers use real-time dashboards to reassign aircraft and crews. The same data supports emissions reporting, which has become a priority as airlines pursue sustainability targets and respond to regulatory requirements, while flight data monitoring also supports safety management programs.
Predictive maintenance is growing fastest as operators use sensor data from engines, landing gear, brakes and other systems to anticipate failures before they cause delays. Models detect small changes in performance, schedule repairs at convenient stops and reduce unplanned removals and aircraft on ground time. Engine makers and airlines are expanding the use of digital twins to simulate component wear. A shortage of technicians raises the value of tools that focus labor where it is needed, and air traffic management and passenger experience management applications also contribute to the broader adoption of analytics, for example through gate planning, baggage tracking and personalized disruption alerts.
⮞In July 2025, Boeing forecast that the industry will need 660,000 new pilots and 710,000 new technicians through 2044. The shortage of skilled maintenance labor supports demand for analytics that focus work where it matters most.
By End User, Airlines Dominates the Big Data in Flight Operations Market and MRO Providers Grows Fastest
Airlines are the largest users because they operate the aircraft, carry the fuel and crew costs and own the operational decisions that analytics inform. Network carriers, low-cost airlines and cargo operators all invest in planning systems, performance monitoring and disruption management. Large airlines build in-house data science teams and partner with technology companies, while smaller carriers rely on packaged solutions. The commercial benefit is direct, since better planning lowers fuel use, reduces delays and improves aircraft utilization, which raises profits in a business with thin margins and gives airlines a lasting reason to widen their analytics budgets.
Maintenance, repair and overhaul providers are growing fastest as aircraft fleets age, engine programs become more data-intensive and airlines outsource more upkeep. These providers use analytics to forecast workloads, manage parts inventory and shorten turnaround times at hangars. Partnerships with engine and airframe makers give them access to health monitoring data that supports condition-based work scopes. Airports and ground handlers also use data for gate allocation, baggage handling and turnaround coordination, and these users add to demand alongside regulators and air navigation service providers that rely on shared flight data.
⮞In July 2026, Airports Council International World reported that global airports handled 9.8 billion passengers in 2025, up 3.7% from 2024, with Atlanta the busiest at 106.3 million. Heavier traffic increases the need for coordinated data use among airports and airlines.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
71.88% |
|
Europe |
Germany |
27.40% |
|
Asia Pacific |
China |
31.60% |
|
Latin America |
Brazil |
46.10% |
|
Middle East and Africa |
United Arab Emirates |
38.70% |
North America Big Data in Flight Operations Market Insights
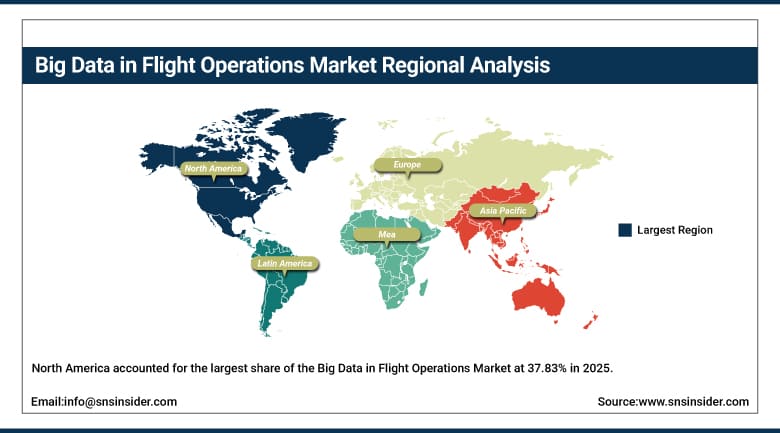
North America accounted for the largest share of the Big Data in Flight Operations Market at 37.83% in 2025, led by the United States, with Canada contributing through its network carriers and aerospace industry. The region hosts major airlines, aircraft and engine makers, avionics suppliers and technology companies that develop analytics for aviation. Large fleets produce vast data volumes, and carriers have a long record of investing in operations control technology. Cargo and low-cost operators add further demand, and a strong base of maintenance providers uses predictive tools, supported by research centers and universities that train specialists in aviation analytics.
Federal programs are strengthening the data environment. Air traffic control modernization, expanded use of satellite-based surveillance and better information sharing between airlines and controllers support more precise planning. Airlines face pressure to improve on-time performance and manage rising labor and fuel costs, which sustains investment in analytics. Partnerships between airlines and cloud and artificial intelligence providers are common, and the region is the first to deploy many new applications, although growth moderates as the base matures, and attention is turning to generative artificial intelligence for operations control and customer recovery.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Big Data in Flight Operations Market Insights
Europe is a large and sophisticated market, anchored by major network airlines, low-cost carriers, aircraft manufacturers and leading software companies such as flight planning specialists. Dense airspace and congested airports increase the value of precise planning and disruption management, and environmental policy pressure encourages carriers to track fuel use and emissions closely. The European aerospace sector develops data platforms that connect aircraft, suppliers and operators, and many airlines were early adopters of shared analytics environments, which gave the region a head start in turning data into planning advantage.
Cooperation among air navigation service providers, airlines and regulators supports data sharing, and programs such as the Single European Sky seek to improve efficiency. Regulation of data protection and cybersecurity shapes how platforms are deployed, which favors providers able to offer regional cloud hosting. Maintenance and repair capacity is substantial, particularly in Germany, France and the United Kingdom. Growth is solid, supported by the recovery of travel demand and by sustainability goals that reward efficient operations, including emissions trading rules that put a price on fuel burn.
⮞In January 2026, Eurocontrol's Maastricht Upper Area Control Centre reported that it handled 1,829,242 flights in 2025, up 2% from the previous year. The traffic level shows the density of airspace that data-driven coordination must support.
Asia Pacific Big Data in Flight Operations Market Insights
Asia Pacific is the fastest growing region, with a projected CAGR of 16.18% from 2026-2035, supported by rapid growth in air travel, large aircraft orders and heavy investment in new airports. China, India, Japan, South Korea and Southeast Asian countries are expanding fleets and building networks, which creates a need for planning and maintenance systems that can scale. Low-cost carriers are adopting cloud analytics to improve aircraft utilization, and national carriers are modernizing legacy systems while building in-house data science teams.
Governments are investing in digital air traffic management and smart airport programs, and domestic technology companies are developing aviation analytics for local operators, often in partnership with state-owned carriers and airports. Maintenance capacity is expanding as fleets grow, with regional hubs seeking a share of repair work, and training programs are slowly widening the pool of data specialists. Challenges include a shortage of data skills, varying regulation and the cost of integration with older systems. Training programs and joint ventures with global vendors are helping to close skill gaps. Even so, the pace of fleet growth and the willingness of carriers to adopt new technology point to the strongest growth among the major regions.
MEA and Latin America Big Data in Flight Operations Market Insights
The Middle East and Africa is led by the United Arab Emirates, with Qatar, Saudi Arabia, Turkey and South Africa also contributing. Gulf carriers operate modern long-haul fleets from major hub airports and are early adopters of predictive maintenance and artificial intelligence. Governments invest in aviation as part of economic diversification, which supports new airports and airline expansion. Africa has smaller fleets and limited digital infrastructure, so adoption is slower, though growth in air connectivity is raising interest, and partnerships with international vendors are helping carriers leapfrog older systems.
Latin America is led by Brazil, with Mexico, Chile, Colombia and Argentina also contributing, and Mexico is treated here as part of this region. Large regional carriers use analytics to manage fuel costs and improve punctuality across long domestic networks and varied terrain. Currency volatility and tight airline budgets can slow technology spending, so many operators prefer cloud services with flexible pricing. Maintenance providers in the region are adopting data tools to support growing fleets and expanding services for international customers, while airports invest in data platforms to manage rising passenger numbers.
Growth Drivers: Fuel Cost Pressure and Predictive Maintenance Demand Drive Growth in the Big Data in Flight Operations Market
Fuel is one of the largest expenses for airlines, and carriers are under constant pressure to reduce consumption and emissions. Data analytics help optimize route selection, altitude profiles and fuel loading, and they provide the measurement needed for sustainability reporting. Even small percentage savings across large fleets translate into significant cost reductions, which makes the return on investment easy to demonstrate. Regulatory and customer expectations about environmental performance reinforce this demand and encourage airlines to adopt more detailed operational analytics.
Predictive maintenance adds a second growth engine. Sensors on engines and aircraft systems produce large volumes of condition data that models use to forecast failures, plan repairs and avoid unscheduled groundings. Fewer delays and cancellations improve customer satisfaction and protect revenue, while better parts planning lowers inventory costs. Aircraft and engine makers are offering platforms that share fleet-wide insight with operators, and airlines are increasingly willing to rely on these tools as evidence of their benefit accumulates over the forecast period, which draws in operators that were previously cautious.
Restraints: Data Integration Complexity and Cybersecurity Concerns Restrain Growth in the Big Data in Flight Operations Market
Airlines operate many legacy systems that were not designed to share data, and integrating them with modern analytics platforms is slow and expensive. Information is spread across flight operations, maintenance, crew and commercial departments, each with its own formats and ownership. Data quality problems reduce the reliability of models, and a shortage of skilled data engineers and analysts in aviation slows implementation, so projects often take longer and cost more than planned. Smaller carriers with limited budgets often postpone projects, which holds back adoption in parts of the market.
Cybersecurity and data governance are further concerns. Flight operations data is sensitive, and a breach could disrupt safety-critical processes or expose commercial information. Regulators and airlines apply strict standards, and questions about data ownership between airlines, aircraft makers and service providers complicate sharing arrangements. Certification requirements for software that affects flight decisions lengthen development cycles and slow the release of new features, and cloud sovereignty rules in some countries limit the use of global platforms, forcing vendors to run separate regional environments at added cost.
Opportunities: Generative Artificial Intelligence and Digital Twins Create Opportunities in the Big Data in Flight Operations Market
Generative artificial intelligence offers new ways for operations staff to interact with data. Assistants can summarize disruptions, suggest recovery options, answer questions about maintenance history and draft reports, reducing the time controllers and engineers spend searching across systems. Airlines are experimenting with these tools in operations control centers and customer service, and technology providers are building aviation-specific models trained on manuals and operational records. Successful pilots could lead to broad deployments across fleets, and early users report faster responses during irregular operations.
Digital twins of aircraft, engines and airports are a second opportunity. By combining live data with physical models, operators can simulate wear, test maintenance plans and evaluate operational changes before applying them. Aircraft makers are expanding these capabilities, and airlines are exploring twins of networks to test schedules and recovery strategies. Growth in new markets, expansion of cargo and the arrival of new aircraft types also create demand for analytics platforms able to ingest data from diverse sources, and vendors with open interfaces are well placed to serve operators that run mixed fleets.
Recent Developments:
-
In February 2026, Palantir and Airbus extended their strategic collaboration on the Skywise aviation data platform, which Airbus reports has more than 50,000 daily users. The agreement includes migration of the platform to a sovereign cloud environment.
-
In November 2025, Emirates announced a strategic collaboration with OpenAI and an AI Centre of Excellence, with predictive maintenance among the focus areas. The move extends the carrier's earlier adoption of Skywise fleet performance and predictive maintenance tools.
-
In August 2025, Collins Aerospace announced that JetBlue had deployed its FlightAware Foresight predictive analytics to anticipate and reduce disruption. The deployment shows the use of forecasting models to improve on-time performance.
Big Data in Flight Operations Market Key Players
-
IBM
-
Oracle
-
Amazon Web Services
-
Google
-
SAP
-
Thales
-
Airbus
-
Teradata
-
GE Aerospace
-
Lufthansa Systems
-
Collins Aerospace
-
Palantir Technologies
-
NAVBLUE
-
SITA
-
Jeppesen
-
Sabre
Big Data in Flight Operations Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.47 Billion |
| Market Size by 2035 | USD 18.93 Billion |
| CAGR | CAGR of 13.22% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software and Services) • By Deployment (Cloud-Based and On-Premise) • By Application (Flight Operations Optimization, Predictive Maintenance, Air Traffic Management, Passenger Experience Management, and Others) • By End User (Airlines, Airports, MRO Providers, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | IBM, Microsoft, Oracle, Amazon Web Services, Google, Honeywell, SAP, Thales, Airbus, Teradata, GE Aerospace, Lufthansa Systems, Collins Aerospace, Palantir Technologies, NAVBLUE, SITA, Jeppesen, Sabre |

Frequently Asked Questions
Key opportunities include generative artificial intelligence assistants for operations control, digital twins of aircraft and airports, and analytics platforms for new aircraft types and cargo growth. Fast-growing fleets in Asia Pacific and the Middle East also offer new customers.
The major growth factor is the need to cut fuel costs and avoid unscheduled maintenance. Analytics improve route planning and forecast component failures, which lowers costs and delays across large fleets.
