
Biocides Market Report Scope & Overview:
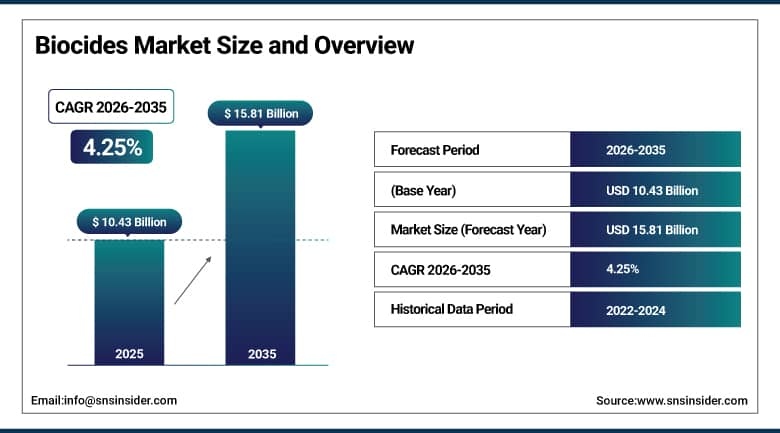
The Biocides Market was valued at USD 10.43 Billion in 2025 and is expected to reach USD 15.81 Billion by 2035, growing at a CAGR of 4.25% from 2026-2035.
The Biocides Market is expanding at a steady pace as water utilities, coatings makers and food processors tighten microbial control. Asia Pacific leads consumption while North America and Europe set the regulatory benchmarks that shape product choices. Municipal and industrial water treatment adds the most volume. Water-based paints need in-can protection. Halogen products remain the cost leader and organic chemistries are gaining ground where chlorine-free options are preferred. High registration costs for active substances are consolidating supply among larger producers. Oxidizing products account for more than half of use. Sustained spending on sanitation and hygiene supports solid value growth through 2035.
⮞In August 2025, the World Health Organization and UNICEF reported that 2.10 Billion people lacked safely managed drinking water in 2024. The gap keeps demand high for chlorine, bromine and other disinfectants used in municipal and community water systems.
To Get More Information On Biocides Market - Request Free Sample Report
Biocides Market Trends:
-
Tighter registration rules in the European Union and South Korea are narrowing the list of legacy active substances and favoring suppliers with approved portfolios.
-
Bio-based, biodegradable and chlorine-free chemistries are gaining attention from paint, personal care and water treatment buyers.
-
Utilities are adopting chlorine dioxide and peracetic acid to limit disinfection byproducts while keeping oxidizing performance.
-
Producers are restructuring through acquisitions and price actions to recover energy and raw material costs.
-
Water infrastructure build-out in Asia Pacific, the Middle East and Latin America is widening the base of treatment chemical demand.
U.S. Biocides Market Outlook:
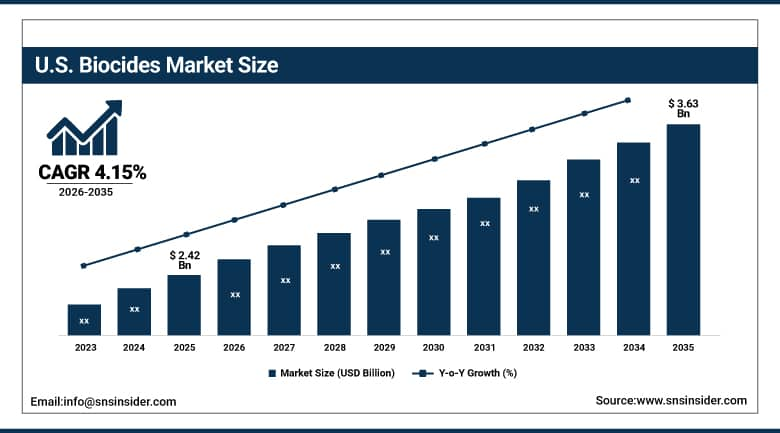
The U.S. Biocides Market was valued at USD 2.42 Billion in 2025 and is expected to reach USD 3.63 Billion by 2035, growing at a CAGR of 4.15% from 2026-2035.
The U.S. Biocides Market accounts for roughly 82.40% of North American demand and anchors the regional outlook. Federal registration of antimicrobial pesticides is mandatory, which favors established suppliers with deep regulatory files. Water treatment, paints and coatings, oil and gas operations and wood preservation form the main outlets. Large utilities are adopting chlorine dioxide to limit regulated trihalomethanes while using existing infrastructure. Housing starts and infrastructure spending sustain treated lumber use. Food processors rely on peracetic acid for no-rinse sanitation. Growth stays steady rather than rapid because the installed base is mature. Suppliers compete on service depth, registration coverage and dosing technology.
⮞In April 2026, the American Coatings Association reported that U.S. paint and coatings product shipments reached USD 33.20 Billion in 2024. Water-based formulations require in-can preservation, which ties coatings output directly to biocide consumption.
Biocides Market Segment Analysis:
-
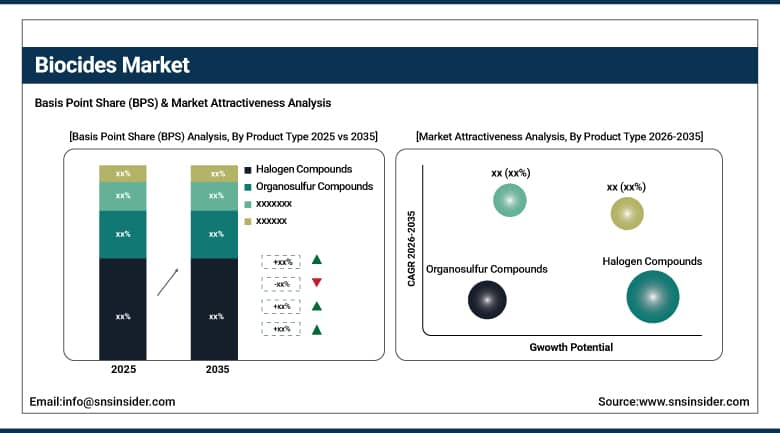
By Product Type, the Halogen Compounds segment dominated the Biocides Market with approximately 27.22% share in 2025, while the Organosulfur Compounds segment is the fastest growing with a CAGR of approximately 5.05%.
-
By Application, the Paints and Coatings segment dominated the Biocides Market with approximately 25.83% share in 2025, while the Water Treatment segment is the fastest growing with a CAGR of approximately 6.25%.
-
By Mode of Action, the Oxidizing Biocides segment dominated the Biocides Market with approximately 55.23% share in 2025, and is also the fastest growing with a CAGR of approximately 4.98%.
-
By Distribution Channel, the Direct Sales segment dominated the Biocides Market in 2025, while the Online segment is the fastest growing with a CAGR of approximately 5.75%.
By Product Type, Halogen Compounds Dominate Biocides Market; Organosulfur Compounds to Register Fastest Growth.
Chlorine and bromine chemistries lead because they kill microbes through oxidation at low cost and act within minutes. Utilities, cooling tower operators and pool managers already understand dosing and monitoring for these products and buy them at scale. Disinfection byproduct limits can often be met through pH and contact time control instead of a change in chemistry. Bromine performs better at high pH, which suits cooling systems. Producers with captive chlor-alkali assets also hedge feedstock swings, keeping prices competitive.
Organosulfur biocides are chlorine-free and non-oxidizing, which suits water systems where corrosion is a concern. Compounds such as 2-mercaptobenzothiazole limit algae and bacterial fouling in recirculating and evaporative circuits serving heavy engineering, automotive plants and air conditioning. Tighter European controls on isothiazolinones and glutaraldehyde steer users toward substitutes and raise compliance costs for older actives. Buyers seeking gentler corrosion profiles and approved alternatives therefore lift organosulfur demand faster than demand for the established halogen base across industrial water systems.
⮞In February 2026, Euro Chlor reported that chlorine production across the EU-27, Norway, Switzerland and the United Kingdom totaled 7.79 Million tonnes in 2025. The output base underpins supply of hypochlorite and other halogen disinfectants used across the region.
By Application, Paints and Coatings Dominate Biocides Market; Water Treatment to Register Fastest Growth.
Coatings meet microbes at every stage, from bulk raw materials and storage tanks to process water and the finished film. Biocides protect the product in the can and later inhibit fungal and algal growth on the dried surface. The shift from oil-based to water-based paints raises exposure to airborne and waterborne microbes and therefore the dosage required. Construction activity and automotive interior and exterior parts add volume. Formulators also treat wash water and wastewater from production lines, which broadens consumption.
Urbanization, industrialization and rising wastewater investment are pushing water treatment ahead of other applications. Biocides prevent biofouling, film formation and bacterial or algal contamination in cooling towers, pools and spas, paper mills and municipal drinking water. Stricter public health and environmental rules encourage water recycling, which relies on continuous dosing in closed loops. Ballast water programs and effluent from chemicals, oil and gas, mining and textiles add further demand, particularly across emerging economies that are expanding treatment capacity quickly.
⮞In August 2025, the Brazilian paint manufacturers association Abrafati reported that paint sales in Brazil reached 670.00 Million liters in the first half of 2025. Volumes of this size require in-can preservation, which keeps coatings a steady buyer of biocides in Latin America.
By Mode of Action, Oxidizing Biocides Dominate Biocides Market and Also to Register Fastest Growth.
Oxidizing products deliver immediate microbial kill and a favorable cost per kilogram of active ingredient, which keeps them the default choice for disinfection. Municipal drinking water relies on chlorination, while pools, cooling towers and food plants use bromine, hypochlorite and peracetic acid for rapid sanitation. Because these actives break down into simple residues they suit large volume applications where speed and economy matter. Familiarity among operators and compatibility with existing dosing equipment sustain wide preference across end uses.
Oxidizers are growing faster than non-oxidizing alternatives because regulation and infrastructure spending favor them. Large utilities are adopting chlorine dioxide since it limits regulated trihalomethanes and works with existing plants. Peracetic acid is spreading in food processing and wastewater because its byproducts are benign and no dechlorination step is needed. Non-oxidizing products face tighter approval scrutiny and serve mainly as supplements for biofilm control in closed loops, which restrains their expansion compared with oxidizing actives across large volume uses.
⮞In June 2025, the European Commission approved methylisothiazolinone for in-can preservatives under Implementing Regulation (EU) 2025/1257. The decision keeps a widely used non-oxidizing preservative available to coatings makers under defined labeling conditions.
By Distribution Channel, Direct Sales Dominate Biocides Market; Online to Register Fastest Growth.
Biocides are technical products sold with dosing programs, regulatory documentation and on-site service. Large buyers such as utilities, paper mills, refineries and coatings plants negotiate supply contracts directly with producers to secure consistent quality, safety data and registration support. Direct relationships allow suppliers to bundle monitoring equipment, training and performance guarantees with chemicals. Hazardous goods handling, bulk tanker delivery and long-term pricing agreements also favor manufacturer-to-customer channels over intermediaries, particularly for oxidizing products shipped in volume to industrial sites.
Online ordering is expanding as smaller buyers seek convenience and price transparency. Pool operators, small food businesses, laboratories and regional formulators increasingly purchase standard grades through digital marketplaces and manufacturer web stores, with delivery of small packs within days. Digital catalogs publish safety data sheets and usage guidance, which shortens procurement cycles. Producers and distributors are investing in e-commerce portals to reach fragmented customers without field sales cost, and repeat ordering tools lift reorder frequency from a low base.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
43.60 |
|
North America |
United States |
82.40 |
|
Europe |
Germany |
27.70 |
|
Latin America |
Brazil |
61.20 |
|
Middle East and Africa |
Saudi Arabia |
38.50 |
Asia Pacific Biocides Market Insights
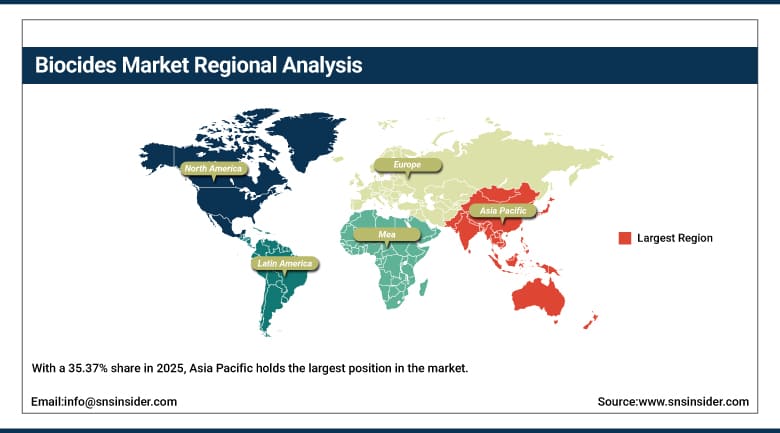
With a 35.37% share in 2025, Asia Pacific holds the largest position in the market. China is the biggest producer and consumer of biocides and accounts for 43.60% of regional demand, helped by abundant raw materials that keep prices below those in Europe and the United States. Water treatment and cleaning products drive volume, and rising pulp and paper output under stricter effluent rules adds consumption. Paint and coatings demand follows construction and urbanization, while India, Japan and South Korea contribute through water infrastructure and industrial hygiene programs. Growing food processing and personal care sectors also broaden demand for preservatives.
The region is also the quickest to expand, advancing at a CAGR of 4.66% over 2026-2035. Zero-discharge cooling water requirements in China keep closed loops under continuous dosing, while India's rural tap water programs create new dosing stations. Japan has tightened Legionella monitoring in building water systems. Producers continue to add capacity in China, including at Nanjing, which shortens supply chains for local formulators and supports rising adoption of both oxidizing and specialty products. Government funding for sanitation and industrial parks keeps new projects flowing, and local suppliers are scaling output to serve them.
⮞In January 2025, South Korea's Ministry of Environment approved 15 biocidal products under the K-BPR framework and confirmed that unapproved products are barred from sale from July 2026. The rule pushes suppliers to complete registrations and favors firms with approved portfolios.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Biocides Market Insights
North America, defined here as the United States and Canada with Mexico reported under Latin America, held 28.14% of the market in 2025. The United States contributes the bulk of purchases through large municipal utilities, power plants, refineries and coatings producers. Oil and gas operators dose biocides in drilling, fracturing and produced water to control sulfate-reducing bacteria and souring, and record crude output keeps those programs active. Strict federal registration rules favor established suppliers with extensive data packages and discourage low-cost entrants. Municipal water systems also expand dosing programs to meet federal disinfection rules in older cities.
Canada adds demand from pulp and paper mills, mining and oil sands operations, where cold climates and large process water volumes call for continuous microbial control. Wood preservation is a further outlet because treated lumber supports housing and utility pole programs. Suppliers are responding with chlorine dioxide generators, peracetic acid blends and non-chlorinated alternatives that meet tightening discharge limits. Customer preference for bundled service contracts keeps major chemical groups close to the end user. Environmental permitting for effluent is tight, so users value products that degrade rapidly and leave low residues in discharge streams.
⮞In March 2026, the U.S. Energy Information Administration reported that U.S. crude oil production reached a record 13.60 Million barrels per day in 2025. Higher output increases the volume of produced and injection water that must be treated, which supports biocide demand in upstream operations.
Europe Biocides Market Insights
Europe held 19.70% of the market in 2025 and operates under one of the most demanding approval regimes in the world. The Biocidal Products Regulation requires every active substance and product type to be reviewed, and high registration costs have prompted consolidation among regional suppliers. Germany leads country-level demand with strong chemicals, paper and coatings sectors, followed by the United Kingdom and France. Enforcement has also cut sales of products judged harmful to health or the environment, which pushes manufacturers to redesign formulations. Industrial users in paper and textiles are also reviewing biocide programs to align with environmental permits.
Water safety and food hygiene sustain steady consumption. Cooling towers and building water systems need Legionella control, and food processors rely on peracetic acid and quaternary ammonium sanitizers to meet hygiene standards. Substitution is the dominant theme as users move from restricted isothiazolinones and aldehydes toward approved or lower-hazard chemistries. Suppliers with local production and complete regulatory dossiers are best positioned, and smaller players have exited the United Kingdom water treatment segment as compliance costs rose. Retail brands increasingly request lower-hazard claims, which accelerates reformulation in personal care and household products.
⮞In December 2025, the European Food Safety Authority and the European Centre for Disease Prevention and Control reported 6,558 foodborne outbreaks across the EU in 2024. The figure keeps food plant sanitation programs and surface disinfectants a priority for processors.
Latin America and Middle East and Africa Biocides Market Insights
Latin America, which includes Mexico, accounted for 9.32% of the market in 2025, led by Brazil with 61.20% of regional demand. Brazil's paint industry, pulp mills and expanding sanitation sector drive consumption, and its regulations permit chlorine dioxide and peracetic acid in potable water. Argentina, Mexico and Colombia add demand from food processing, mining and municipal treatment. Currency swings and import dependence raise prices for specialty actives, so buyers favor lower-cost halogen products while sanitation reform gradually lifts spending on professional treatment programs. Rising packaged food output in fast-growing urban centers adds preservative use.
⮞The Brazilian water and sewage concessionaires association ABCON reported in its 2026 sanitation agenda that only 52.00% of generated sewage in Brazil is treated. Federal Law 14.026 sets universal service targets for 2033, which points to heavy investment in treatment plants and the chemicals that operate them.
In 2025, the Middle East and Africa had a share of 7.47% of the market, where Saudi Arabia alone accounted for 38.50% of the regional demand. The largest application in the Gulf countries is seawater desalination, which needs biofouling prevention technology in intake and membrane processes, while petrochemical and oil & gas plants increase demand in cooling and process water treatment. In South Africa, there is mining and municipal demand. Large-scale government water projects under national development plans offer long-term contracts; however, limited local manufacturing makes the region dependent on imports from Europe and Asia.
⮞In June 2026, Saudi Arabia's National Transformation Program reported that desalination capacity exceeded 16.00 Million cubic meters per day by the end of 2025. Capacity at this scale requires continuous treatment of intake and process water, which anchors regional biocide demand.
Market Dynamics:
Growth Drivers: Water treatment investment and rising wood-based product output are lifting biocide consumption.
Water treatment & sanitation expenditure accounts for the most incremental volume. Water supply networks and sewage/waste water treatment facilities in addition to desalinization installations which rely on oxidative bactericides in combination with a supplementary non-oxidative program in terms of biofilm elimination are being constructed by the respective authorities and industries. Concerns about health and hygiene due to various water and foodborne diseases have driven further penetration of the sector in food preparation, cleaning and personal hygiene segments. The support by regulations of more effective and safe actives will benefit existing players and drive the exit of those who are not registered. Institutional cleaning market provides additional volume contribution.
Preservation of wood and construction material is another constant volume contributor. Various types of construction materials such as treated timber, plywood, panels and furniture elements require fungicide/pesticide protection from decay, fungi and pests. Treating wood with preservative agents provides premium pricing up to 20.00% compared to untreated products. Construction of homes in North America and infrastructure in Asia Pacific maintains constant demand. Marine and ground contact treatment requires double biocides application increasing the amount of actives per one cubic meter of the material.
⮞In December 2025, the Food and Agriculture Organization reported that global wood-based panel production rose 5.00% to 393.00 Million cubic meters in 2024. Larger panel output enlarges the volume of material exposed to decay and mold, which supports demand for wood preservatives.
Restraints: Registration costs, health concerns and raw material price swings are limiting supplier flexibility.
The compliance cost is the first challenge. Active ingredients are evaluated according to the European Biocidal Products Regulation, federal registration in the U.S., and the new national schemes in South Korea, and all require toxicology, efficacy and environmental data. Small producers cannot finance these studies and drop backing up the older actives. There are concerns regarding the safety of sensitizers, aldehydes and halogenated by-products, and consumers try to limit dosages or substitute chemistry, cutting volume growth. Changing formulations based on the active ingredient restrictions takes several years and involves additional testing of stability and effectiveness.
Price fluctuations of input costs are another challenge. The price of halogens, iodine, phenols and quaternary ammonium raw materials depends on energy and feedstock prices, and there are announcements about significant increases in prices. Competing tender customers in paint, water treatment and personal care do not accept these increases. Exchange rates and logistics interruptions complicate procurement for the dependent on imports countries. Costs for research, necessary to register bio-based or low hazard alternatives, are high, and long evaluation periods slow down return on the new products. Volatile input costs complicate the long-term contract pricing.
Opportunities: Desalination, water reuse and bio-based chemistries are opening new revenue pools for suppliers.
The most promising market is water infrastructure outside of North America. Pretreatment biocides are required for desalination plants, reuse and rural tap water initiatives in the Gulf, North Africa, South Asia and China. Zero discharge cooling obligations in industrial parks drive a steady flow of business. The providers of on-site treatment, monitoring and maintenance contracts have the opportunity to capture these multi-year programs, especially in cases where utilities prefer combined technical services. Reverse osmosis plant tenders by municipalities often call for antifouling chemicals for several years in advance.
Biocides that are plant-based, enzyme-based and biodegradable are becoming interesting for formulators, as well as those based on nanotechnology and requiring smaller doses due to the pressure on brand owners to reduce chemical footprint. Non-chlorinated disinfectants for hospitals and the transition from oil-based to water-based paints create opportunities in the automotive and construction coatings. Customized biocide solutions for specific chemistry of process water help specialty companies to distinguish themselves from their competitors and increase margins. Hospitals and food processing companies look for disinfectants with reduced residue and less odor.
⮞In June 2025, the Moroccan government reported a target of 1.70 Billion cubic meters a year of desalination capacity by 2030. Delivering that capacity will require large pretreatment and antifouling programs, creating a multi-year opening for biocide suppliers.
Recent Developments:
-
March 2026, LANXESS announced price increases of up to 30.00% for selected Microbial Control products, effective immediately. The company cited higher energy, raw material and logistics costs, which shows that biocide producers are passing cost pressure through to formulators and water treatment customers.
-
July 2025, Pritzker Private Capital completed its acquisition of Buckman. The completion places a major supplier of microbial control programs for pulp and paper, water treatment and oil and gas under new private ownership and marks a notable ownership change in the specialty biocides supplier base.
-
October 2026, Arxada launched Proxel BCP, a preservative for home care formulations introduced at SEPAWA 2026. The product extends the company's in-can Proxel range into household cleaning applications and shows suppliers adapting preservation systems to consumer product demand.
-
June 2025, Solenis agreed to acquire NCH Corporation, with closing expected by the end of 2025. The agreement combines two broad suppliers of water and hygiene chemistry and signals continued consolidation among specialty chemical providers serving industrial and institutional buyers.
Biocides Market Key Players:
-
LANXESS
-
Arxada
-
THOR
-
Ecolab
-
Solenis
-
Buckman
-
Kemira
-
Clariant
-
Albemarle
-
Vink Chemicals
Biocides Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 10.43 Billion |
| Market Size by 2035 | USD 15.81 Billion |
| CAGR | CAGR of 4.25% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Halogen Compounds, Organosulfur Compounds, Metallic Compounds, Quaternary Ammonium Compounds, Phenolics, Organic Acids, Nitrogen-Based Compounds, Glutaraldehyde, and Others) • By Application (Paints and Coatings, Water Treatment, Wood Preservation, Food and Beverage, Personal Care, and Others) • By Mode of Action (Oxidizing Biocides and Non-Oxidizing Biocides) • By Distribution Channel (Direct Sales, Distributors, and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | LANXESS, Arxada, THOR, Ecolab, Solenis, Buckman, Kemira, Clariant, Albemarle, Vink Chemicals |

Frequently Asked Questions
The key players in the Biocides Market include THOR, Ecolab, Kemira, Clariant and Albemarle, among others.
Desalination and water reuse projects, rural drinking water programs and bio-based or low-dose chemistries offer the strongest opportunities. Water-based coatings and non-chlorinated disinfectants for medical settings add further openings for suppliers with approved portfolios.
Rising investment in drinking water, wastewater and industrial water treatment is the major growth factor, supported by stricter hygiene standards and demand for preserved water-based paints.
The Halogen Compounds segment dominated the Biocides Market in 2025 with approximately 27.22% share, supported by the low cost and fast oxidizing action of chlorine and bromine in water and food applications.
Asia Pacific dominated the Biocides Market in 2025 with approximately 35.37% share, supported by large production capacity, water infrastructure programs and expanding coatings and paper output.
