
Biodiesel Market Report Scope & Overview:
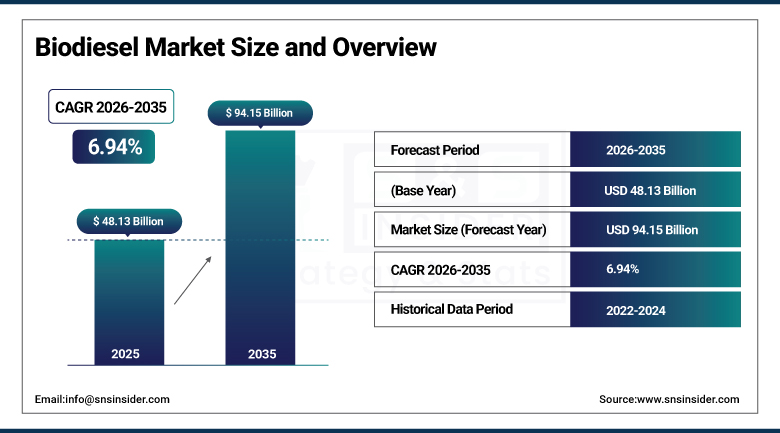
The Biodiesel Market was valued at USD 48.13 Billion in 2025 and is expected to reach USD 94.15 Billion by 2035, growing at a CAGR of 6.94% from 2026-2035.
Biodiesel Market is growing at a stable pace as government increases blending requirements and fleets seek a less carbon intensive diesel that works with current engine technology. The revenue generated in this market includes sales of fatty acid methyl ester biodiesel and hydrotreated vegetable oil as well as co-processed diesel produced as a biomass-based fuel, and does not include bioethanol, biogas and sustainable aviation fuel. Vegetable oils form the leading source material, although used cooking oil and animal fats are becoming increasingly popular among producers seeking to improve their carbon intensity scores. The mandate action in Indonesia, Brazil, Germany and the USA influences operations in plants and the movement of products. Europe accounts for the largest revenue share currently, followed by APAC region.
⮞In July 2026, Neste reported a comparable sales margin of USD 1,223 per ton for its Renewable Products segment in the second quarter, compared with USD 361 per ton a year earlier. The company said its Rotterdam expansion is still progressing and that renewable production capacity should reach 6.80 million tons annually in 2027.
To Get more information On Biodiesel Market - Request Free Sample Report
Biodiesel Market Trends
-
Raising blend mandates, such as Indonesia's B50 for public-service diesel and Brazil's step up to B15, to lock in higher guaranteed demand.
-
Shifting feedstock purchases toward used cooking oil and animal fats to meet lower carbon intensity requirements.
-
Adding hydrotreated vegetable oil units beside or in place of conventional trans-esterification plants.
-
Expanding output at existing sites rather than building new plants, including U.S. projects that double capacity.
-
Testing B100 and high-blend fuel in trucks and backup generators through retrofit kits and pilot programs.
U.S. Biodiesel Market Outlook
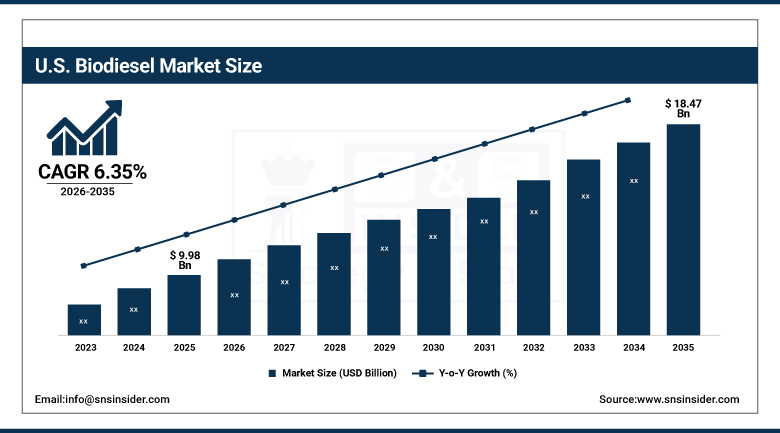
The U.S. Biodiesel Market was valued at USD 9.98 Billion in 2025 and is expected to reach USD 18.47 Billion by 2035, growing at a CAGR of 6.35% from 2026-2035.
The U.S. Biodiesel Market is expanding healthily due to federal tax credits, RVO levels, and various state low carbon initiatives that are increasing the demand for biomass-based diesel. Soybeans are the top feedstock, with a record soybean crop making the feedstocks cheaper for crushers and biodiesel producers. The Section 45Z clean fuels production credit has been a significant boost to the economics of biodiesel plants following some years of regulatory uncertainty, as well as high renewable identification number prices in 2026, improving margins. Biodiesel plants have been restarted and expanded in existing facilities, with feedstocks and trade policies being the key risk factors.
⮞In October 2026, Continental Refining Company said a capital expansion at its biodiesel facility in Somerset, Kentucky, which began in August, is expected to double output capacity, with completion targeted for 15 November. The company is also adding a rail spur to the Norfolk Southern main line so that it can receive and ship biofuel nationwide.
Biodiesel Market Segment Analysis
-
By Feedstock, the Vegetable Oils segment dominated the Biodiesel Market with approximately 63.28% share in 2025, while the Used Cooking Oil segment is the fastest growing with a CAGR of approximately 10.73%.
-
By Production Process, the Trans-Esterification (FAME) segment dominated the Biodiesel Market with approximately 67.42% share in 2025, while the Hydrotreated Vegetable Oil (HVO) segment is the fastest growing with a CAGR of approximately 12.07%.
-
By Blend Level, the B5 and Below segment dominated the Biodiesel Market with approximately 46.19% share in 2025, while the B100 segment is the fastest growing with a CAGR of approximately 10.94%.
-
By Application, the Road Transportation segment dominated the Biodiesel Market with approximately 66.81% share in 2025, while the Industrial Uses segment is the fastest growing with a CAGR of approximately 12.46%.
By Feedstock, Vegetable Oils Dominates the Biodiesel Market and Used Cooking Oil Grows Fastest
Vegetable oils dominated the market in 2025 due to the high availability of soybean, rapeseed, palm, and sunflower oils that have been available in large quantities. These oils also have known chemical composition that meets specifications such as EN 14214 and ASTM D6751, and this is done through simple processes. The crushing facilities in the US, Brazil, Argentina, Germany, and Indonesia crush the seeds into oil in proximity to the plants. This makes the logistics easy, making crushing and refining feasible. Regulations and government policies are made keeping in mind these plants, and agricultural policies are made to help increase production from them.
Used cooking oil is advancing fastest owing to the fact that consumers and policymakers are attributing reduced carbon intensities for fuels from waste, and many policies in Europe and Asia use it towards the advanced criteria. Used cooking oil collection systems from restaurants, food processing plants, and even homes are expanding, while new facilities are being developed especially for used cooking oil. Pretreatment is the biggest bottleneck because of the need to clean out free fatty acids and other impurities before the conversion process, hence more pretreatment lines are being added. The amount of feedstock depends on the collected quantities, making prices remain high.
⮞In August 2024, M11 Industries, a subsidiary of M.K. Agrotech, started operations at a 450-tonne-per-day used cooking oil biodiesel plant in Padubidri, Karnataka, built with an investment of INR 350 crore. The company described it as India's largest biodiesel plant, and the output is intended for oil marketing companies.
By Production Process, Trans-Esterification (FAME) Dominates the Biodiesel Market and Hydrotreated Vegetable Oil (HVO) Grows Fastest
Trans-esterification led the market in 2025 as it is the well-established pathway for the production of fatty acid methyl ester, operates under moderate pressure and temperature conditions, and requires much less capital expenditure per unit of capacity than hydrotreating. Triglycerides are converted to esters and glycerin in the presence of methanol and a catalyst, and glycerin serves as a byproduct which generates additional income. Many thousands of facilities in the U.S., Europe, Brazil, and Southeast Asia utilize this pathway, and equipment manufacturers provide standard designs for various raw materials. Regulations in many countries mandate methyl ester blends, making current facilities safe from losing their customers despite the development of new technologies.
Hydrotreated vegetable oil is growing fastest as it is a paraffinic fuel which can be used straight as fuel and even blended in any ratio and is effective in cold climates and is readily accepted by most engine producers as fuel. It is possible for refiners to convert their current facilities to produce HyVOL or construct new hydrotreating facilities; these facilities are also capable of producing sustainable aviation fuel thus enhancing the revenues from this business. The initial capital investment required is relatively high compared to the methyl ester process and hydrogen must be supplied, but the demands arising from the implementation of Germany’s RED III and the US credits ensure profitability.
By Blend Level, B5 and Below Dominates the Biodiesel Market and B100 Grows Fastest
Low blends lead because they match the legacy mandates in many countries and can be used in any diesel engine without warranty concerns. Fuel suppliers and terminals handle them easily because the product is mixed at the refinery or depot, and tank, pipeline, and filter issues are limited. Many fuel specifications, including the European diesel standard, permit blends of up to 7 percent in regular pump diesel, so a large volume reaches consumers without a separate label. Mandated pools and voluntary blending keep this segment large, although regulators are raising blend rates in several markets, which gradually moves volume into higher blend levels.
B100 is growing fastest from a small base as fleets use retrofit kits and dedicated supply to cut tailpipe carbon emissions. Neat biodiesel needs heated fuel lines, filters, and cold-weather management, so adoption depends on dedicated fueling points and equipment approvals. Bus operators, waste haulers, and private truck fleets are early users, and plant owners are running their own vehicles on their output to demonstrate performance. Blends from B6 to B20 serve mixed fleets and rail operators, while blends from B21 to B99 are used in specialized fleets and generators, making up the remaining parts of the segment.
⮞In April 2026, Optimus Technologies and Sunoil Biodiesel B.V. formed a commercial partnership to speed up B100 use in Dutch heavy-duty fleets. Sunoil, which runs waste-based biodiesel plants in Emmen and Kampen, will fit the Vector System to trucks in its own private fleet, marking the technology provider's entry into the European market.
By Application, Road Transportation Dominates the Biodiesel Market and Industrial Uses Grows Fastest
Road transportation takes the largest share because trucks, buses, and cars consume most of the world's diesel, and blending mandates are applied to pump diesel. Biodiesel blended at refineries, terminals, and depots flows through existing pipelines and stations, so uptake does not need new vehicles or infrastructure. Long-haul trucking and public transit fleets are especially important, since they buy large volumes under contract and report emission reductions to customers. Fuel standards, tax credits, and low-carbon fuel programs are most developed for this use, which keeps road demand stable even as growth shifts toward other applications.
Industrial uses are growing fastest as mines, construction sites, ports, rail operators, and marine fleets switch off-road equipment to biodiesel and hydrotreated vegetable oil to meet corporate emission targets. Fuel stored for long periods needs stability additives, and engine makers are certifying equipment for higher blends, which opens the way for wider adoption. Power generation, including backup and remote-site engines at data centres, forms a separate application, and other uses such as heating make up the balance. These buyers pay less attention to pump price and more to emissions and supply reliability, which supports premium contracts and steady growth.
⮞In May 2026, Bridge Data Centres and EcoCeres announced completion of an inaugural hydrotreated vegetable oil backup fuel pilot at data centre campuses in Asia Pacific. The pilot covered generator startup, load transfer, and sustained operation under data centre conditions, and the companies said all performance and emissions targets were met.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Europe |
Germany |
26.24% |
|
Asia Pacific |
Indonesia |
41.57% |
|
North America |
United States |
91.81% |
|
Middle East & Africa |
Saudi Arabia |
33.96% |
|
Latin America |
Brazil |
61.99% |
North America Biodiesel Market Insights
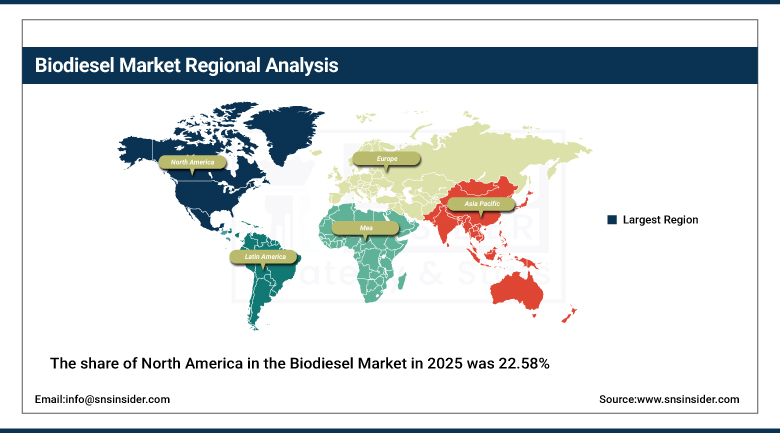
The share of North America in the Biodiesel Market in 2025 was 22.58% or USD 10.87 billion, and it is expected to grow at a CAGR of 6.32% over 2026-2035. The United States accounts for 91.81% of the total regional share, representing USD 9.98 billion of the rounded value of North America. The demand is driven by the Renewable Fuel Standard Program, Low Carbon Programs in states, and federal tax credits. Thus, the biomass-based diesel has stable demand. Growth will be moderate due to the dependence of plant capacity utilization on the policy timing, price of feedstock, and renewable diesel competition.
There are nine bio-refineries owned by Chevron Renewable Energy Group, of which two are located in Mason City and Newton in Iowa, while there are three biodiesel plants owned by Ag Processing, processing refined soybean oil, showing integration of crushers and producers in the Midwest region. Soybean oil continues to be the predominant feedstock, whereas animal fat and used cooking oil are important in coastal regions. Canada makes its contributions through canola and waste oil biodiesel under federal and provincial clean fuels regulations.
⮞In June 2026, the Mississaugas of the Credit Business Corporation and HOPA Ports announced a partnership to restart a biodiesel production facility in Hamilton, Ontario, to prevent its permanent closure. The facility, described as critical to biodiesel supply in Ontario, is expected to resume operations later in summer 2026.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Biodiesel Market Insights
Europe represented 41.27% share in the Biodiesel Market in 2025 at USD 19.86 Billion and is thus the largest regional market and is expected to grow with a CAGR of 5.72% from 2026 to 2035. Europe is under the Renewable Energy Directive and the final implementation of RED III by Germany will contribute around 1.50 million tonnes of yearly renewable diesel demand in 2026. Growth is slow as compared to the global growth due to the maturity of blending and double counting policies in favor of waste-based biodiesel, leaving no room for methyl esters from oil crops.
Germany is the largest national market, supported by rapeseed crushing capacity and established blending infrastructure, with Louis Dreyfus Company producing rapeseed-based biodiesel in the country. In Austria, Münzer Bioindustrie, which identifies itself as the country's largest biodiesel producer with annual production exceeding 200,000 tonnes, manufactures biodiesel from used cooking oil and other waste materials for the transport sector. The Netherlands, France, Spain, and Italy contribute additional biodiesel production through established crushing facilities, refineries, and waste-based feedstock producers.
Asia Pacific Biodiesel Market Insights
The Asia Pacific held a 26.74% share of the Biodiesel Market in 2025, valued at USD 12.87 billion, and is also the fastest-growing region, with a projected CAGR of 9.28% during 2026–2035. In Indonesia, the B50 biodiesel mandate was implemented from July 1, 2026, increasing the blending requirement to 50% across the country. The initial 2026 production allocation was approximately 15.65 million kiloliters, which was subsequently revised to 16.7 million kiloliters to support the B50 rollout across PSO and non-PSO sectors. In Southeast Asia, palm oil remains the primary feedstock for biodiesel production.
Indonesia represents the largest domestic market in this study, with the integrated palm oil firms such as Musim Mas having biodiesel as one of its products and converting crude palm oil into fuels within the supply chain itself. India is planning to use used cooking oil in an effort to reduce diesel imports with plants already working in Karnataka. Malaysia, Thailand, and China increase their capacities via palm and waste oil producers, whereas Japan and Vietnam are developing pretreatment and capacities.
MEA & Latin America Biodiesel Market Insights
In 2025, the Middle East & Africa had 3.04% share in the Biodiesel Market, valued at USD 1.46 Billion and forecasted to grow at a CAGR of 3.92% during the period 2026-2035. The contribution by Saudi Arabia in the region's market was 33.96%, whereas production in other regions was from small used cooking oil facilities like Lootah Biofuels operating in UAE, who sell B5 in their own outlets in Dubai. The mandates are not numerous and exports to Europe & Asia play a major role.
⮞In January 2025, Wakud described its Khazaen Economic City biorefinery as Oman's first biodiesel biorefinery and the first in the world to run entirely on solar power. The plant recycles used cooking oil, exports biodiesel to Europe and Asia, and supplies local energy companies and public sector organizations, according to chief executive Maher bin Mohammed al Habsi.
The Latin American region had a market share of 6.37% for the Biodiesel market in 2025, valued at USD 3.07 Billion and is expected to witness a CAGR of 7.04% between 2026 to 2035. The country with the largest share in the region is Brazil with 61.99% of the market share, after the blend mandate was increased from B14 to B15 in August 2025 and plans for B16 in 2026. The predominant raw material used is Soybean Oil and in 2023, Cargill acquired 3 Granol soybean crushing & biodiesel production units in Brazil.
⮞In March 2026, Caramuru Alimentos reported that net revenue from its biofuels segment rose 18.50 percent to R$ 2.50 billion in 2025, supported by a 6.5% rise in volume sold and an 11.20% rise in average price. The company produces biodiesel in Sorriso, Mato Grosso, and expects the B16 blend to be implemented in 2026.
Market Dynamics
Growth Drivers: Rising Blending Mandates and Low-Carbon Fuel Incentives
Higher blending mandates act as the first driving factor since a mandate turns biodiesel demand into an assured volume. Production facilities can enter into long-term contract agreements and expansion of production facility after the mandate trajectory becomes clear. The second factor is incentives for low-carbon fuels. High renewable identification number prices in 2026 have made US margins more attractive, the section 45Z credit incentivizes fuels according to their carbon intensity, and Europe gives an additional boost to waste fuel. They offer compensation to producers for reducing emissions, which benefits used cooking oil, animal fats, efficient production facilities, and prompts voluntary buying of biodiesel by fleet owners. Companies report their supply chain emissions, and the demand for low-carbon fuel certificates increases among trucking, logistics, and mining industries.
⮞In September 2026, Wilmar's group head of biofuels, Rahul Kale, said at APPEC 2026 in Singapore that any increase in Indonesia's mandatory blend beyond B50 will require new production capacity. He added that utilization of existing plants is already approaching very high levels under the current B50 mandate.
Restraints: Feedstock Cost Volatility and Policy Uncertainty and Competition from Renewable Diesel
Constraints come from the cost and availability of feedstocks, since the cost of biodiesel production comes largely from the feedstock. Vegetable oil prices fluctuate with climate, exporting policies, and food demand, while waste oils depend on the collection volumes. Producers unable to pass through cost will shut down production facilities, as occurred at one Arkansas producer in June 2025, due to high input costs and uncertainties regarding policies. Older and smaller plants that lack access to inexpensive pretreated feedstock are the most vulnerable, but even larger plants require careful management of hedging and inventories, leading to slower capacity expansion and lower profits when margins are low.
Second constraint consists of the policy uncertainty and competition with other fuels. Since demand is driven by the mandates and credits, delay in regulation and alteration in credits affect the margins instantly, leading producers to cut back production awaiting more information. In addition, regulators in some countries set limitations on the crop-based fuels to ensure food availability, which constrains the growth of methyl esters. Hydrotreated vegetable oil and renewable diesel compete for the same feedstock and credits as methyl ester, but plants built for methyl ester are not flexible enough to satisfy advanced fuels demand globally.
Opportunities: Waste-Based Feedstock Supply Chains and Hydrotreating for Sustainable Aviation Fuel
Waste-based feedstock supply chains offer a large opportunity because used cooking oil, animal fats, and processing residues earn lower carbon intensity scores and premium prices. Collection programs for restaurants, food factories, and households, together with traceability and certification systems, can unlock volumes that are not yet recovered. Pretreatment lines allow plants built for crop oils to accept lower-grade material, and suppliers that secure long-term collection contracts gain a cost and carbon advantage. Producers that document origin and sustainability can sell into markets where buyers pay for verified emission reductions, which supports healthier margins and rewards early movers.
Hydrotreating capacity that also makes sustainable aviation fuel gives producers a second revenue stream. The same hydroprocessed esters and fatty acids pathway yields renewable diesel, aviation fuel, and naphtha, so operators can shift output toward the product with the best margin. Aviation fuel mandates in Europe and incentives elsewhere are creating demand that crop-based methyl ester cannot serve, and technology licensors are signing new projects in several countries. Methyl ester producers can partner on feedstock pretreatment or convert part of their capacity, keeping existing assets productive while meeting advanced fuel targets.
Recent Developments:
-
August 2026: Aemetis, Inc. (Universal Biofuels) secured allocations to supply more than 18 million liters of biodiesel to India's three government-owned Oil Marketing Companies over a three-month period. The contracts are expected to generate approximately USD 17 million in revenue, strengthening the company's biodiesel supply operations in India.
-
August 2026: Kotyark Industries Limited secured a biodiesel supply contract worth INR 173.45 crore from Indian Oil Corporation (IOCL), Bharat Petroleum Corporation (BPCL), and Hindustan Petroleum Corporation (HPCL). The allocation forms part of a combined procurement tender valued at INR 1,397.72 crore, covering biodiesel supplies during the 2026 delivery period.
-
October 2026: Continental Refining Company (CRC) commenced a capital expansion of its biodiesel production facility in Somerset, Kentucky, in August 2026. The project is expected to double production capacity by November 15, 2026. The company is also adding a rail connection to improve biodiesel distribution and transportation capabilities.
-
May 2026: Malaysia announced the phased introduction of B15 biodiesel production through 19 licensed plants beginning June 1, 2026. The rollout includes an initial B15 production phase, followed by B20, with the government considering further increases to B50 over the following two to three years.
Biodiesel Market Key Players are:
-
Neste Oyj
-
Archer-Daniels-Midland Company
-
Cargill, Incorporated
-
Wilmar International Limited
-
Chevron Renewable Energy Group
-
Verbio SE
-
FutureFuel Corp.
-
Incobrasa Industries Ltd.
-
Ag Processing Inc. (AGP)
-
Münzer Bioindustrie GmbH
-
Musim Mas Group
-
Louis Dreyfus Company B.V.
-
Caramuru Alimentos S.A.
-
Continental Refining Company
-
Enilive S.p.A. (Eni S.p.A.)
-
Bunge Limited
-
TotalEnergies SE
-
Mewah International Inc.
-
Renewable Energy Group
-
Preem AB
Biodiesel Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 48.13 Billion |
| Market Size by 2035 | USD 94.15 Billion |
| CAGR | 6.94% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Feedstock: Dominant – Vegetable Oils (63.28% share in 2025); Fastest-Growing – Used Cooking Oil (CAGR 10.73%) • By Production Process: Dominant – Trans-Esterification (FAME) (67.42% share in 2025); Fastest-Growing – Hydrotreated Vegetable Oil (HVO) (CAGR 12.07%) • By Blend Level: Dominant – B5 and Below (46.19% share in 2025); Fastest-Growing – B100 (CAGR 10.94%) • By Application: Dominant – Road Transportation (66.81% share in 2025); Fastest-Growing – Industrial Uses (CAGR 12.46%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Neste Oyj, Archer-Daniels-Midland Company, Cargill, Incorporated, Wilmar International Limited, Chevron Renewable Energy Group, Verbio SE, FutureFuel Corp., Incobrasa Industries Ltd., Ag Processing Inc. (AGP), Münzer Bioindustrie GmbH, Musim Mas Group, Louis Dreyfus Company B.V., Caramuru Alimentos S.A., Continental Refining Company, Enilive S.p.A. (Eni S.p.A.), Bunge Limited, TotalEnergies SE, Mewah International Inc., Renewable Energy Group, Preem AB |

Frequently Asked Questions
Key players include Archer-Daniels-Midland Company, Cargill, Incorporated, Chevron Renewable Energy Group, Ag Processing Inc, and Münzer Bioindustrie GmbH, among others.
Waste-based feedstock supply chains for used cooking oil and animal fats, together with hydrotreating capacity that also produces sustainable aviation fuel, represent the primary opportunities.
Growth is primarily driven by rising blending mandates and low-carbon fuel incentives that convert policy targets into predictable biodiesel volumes.
By Feedstock, Vegetable Oils dominated the market with approximately 63.28% share in 2025, reflecting abundant supply and well-established conversion chemistry.
Europe dominated the market with approximately 41.27% share in 2025, driven by the Renewable Energy Directive, mature blending systems, and strong demand for waste-based fuel.
