
Bioplastic Packaging Market Report Scope & Overview:
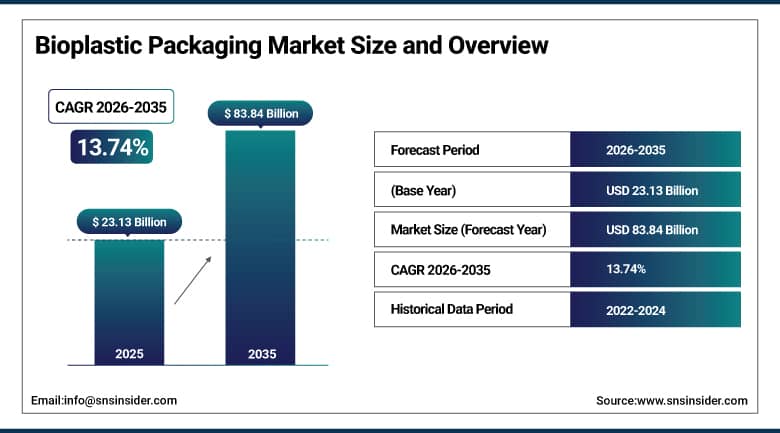
The Bioplastic Packaging Market was valued at USD 23.13 Billion in 2025 and is expected to reach USD 83.84 Billion by 2035, growing at a CAGR of 13.74% from 2026-2035.
The Bioplastic Packaging Market covers bio-based and biodegradable materials used to manufacture films, trays, bottles, pouches, cups, bags, labels, protective inserts, and compostable serviceware across food, beverage, personal care, pharmaceutical, and consumer goods supply chains. Core feedstocks include polylactic acid, polyhydroxyalkanoates, starch blends, bio-based polyethylene, bio-based polyethylene terephthalate, and cellulose-based polymers, each tuned for a mix of barrier performance, compostability, and drop-in compatibility with existing filling and conversion lines. Brand owners are increasingly treating material choice as a compliance and balance-sheet decision rather than a purely cosmetic sustainability signal, which is drawing packaging converters, resin producers, and retailers into a tightly linked value chain. Demand is broadening beyond niche specialty retail into mainstream quick-service food packaging, e-commerce mailers, and premium personal care lines, positioning bioplastic packaging as a structurally important segment of the wider global packaging industry rather than an experimental adjacent category.
In October 2023, Versalis S.p.A. completed the acquisition of the remaining 64% stake in Novamont S.p.A., lifting its ownership from 36% to full control and folding Novamont's Mater-Bi biodegradable and compostable resin lines, used widely in shopping bags, organic-waste liners, and flexible food packaging, into a larger integrated petrochemical-to-bioplastics platform. The transaction illustrates a broader pattern in the market, where established chemical majors are absorbing specialized bioplastics innovators to secure proprietary formulations and production know-how rather than building comparable capability organically, a dynamic that is expected to accelerate as regulatory deadlines under Europe's packaging and packaging waste rules draw closer and scale becomes a decisive competitive advantage.
To Get More Information On Bioplastic Packaging Market - Request Free Sample Report
Bioplastic Packaging Market Trends:
-
Accelerating shift toward biodegradable and compostable resins as EU and North American single-use plastic restrictions tighten.
-
Rapid scale-up of bio-based drop-in polymers such as bio-PE and bio-PET that fit existing filling and conversion equipment.
-
Growing use of flexible bioplastic pouches and films to serve e-commerce mailers and on-the-go food service formats.
-
Rising investment in enzymatic recycling and advanced composting infrastructure to close the loop on bio-based packaging waste.
-
Expanding adoption of bioplastic packaging within premium cosmetics and personal care lines seeking sustainability differentiation.
U.S. Bioplastic Packaging Market Outlook:
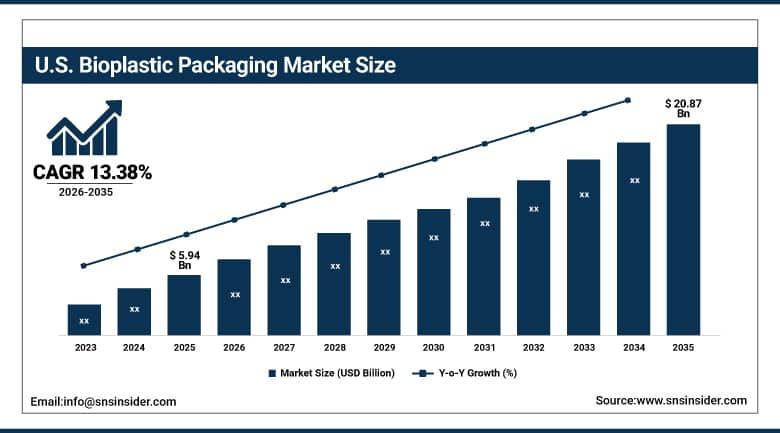
The U.S. Bioplastic Packaging Market was valued at USD 5.94 Billion in 2025 and is expected to reach USD 20.87 Billion by 2035, growing at a CAGR of 13.38% from 2026-2035.
The U.S. continues to be a hotbed for capacity expansion of bio-based resins, thanks to its own PLA manufacturing capabilities and expanding converter network catering to food service, retail and institutional composting programs. Extended Producer Responsibility legislation within the states of California, Colorado and Oregon will compel brands to re-evaluate their packaging portfolios in terms of incorporating recyclable or compostable substrates, whereas sustainability initiatives of national retailers and quick service restaurant chains will drive enduring purchasing demand. Capacity growth within the country is focused on the Midwest and Gulf Coast region, as this will allow producers the opportunity to mix in feedstocks derived from agriculture and petrochemical facilities.
In February 2025, NatureWorks LLC entered a multi-year supply agreement with Mitsubishi Chemical Group to expand Ingeo PLA production capacity earmarked for export markets, a move that reinforces the dual role U.S. producers now play as both domestic suppliers and global capacity anchors for Asia-Pacific demand. The agreement reflects how American PLA producers are using long-term offtake commitments to justify capital investment decisions, effectively linking U.S. manufacturing expansion to overseas market growth. This cross-border capacity strategy is becoming a template for other domestic bioplastics producers weighing whether to add capacity purely for the home market or to position U.S. plants as export platforms serving faster-growing regions.
Bioplastic Packaging Market Segment Analysis:
-
By Material Type, the Biodegradable segment dominated the Bioplastic Packaging Market with approximately 63.45% share in 2025, while the Non-Biodegradable segment is the fastest growing with a CAGR of approximately 15.82%.
-
By Packaging Type, the Flexible segment dominated the Bioplastic Packaging Market with approximately 61.20% share in 2025, while the Rigid segment is the fastest growing with a CAGR of approximately 14.65%.
-
By Application, the Food & Beverages segment dominated the Bioplastic Packaging Market with approximately 41.30% share in 2025, while the Cosmetic & Personal Care segment is the fastest growing with a CAGR of approximately 16.10%.
By Material Type, Biodegradable dominates, and Non-Biodegradable grows fastest
Biodegradable materials, including PLA, PHA, and starch-based blends, led the market in 2025 because they directly address compostability mandates being written into packaging waste regulations across Europe and parts of North America. Food service operators and institutional buyers have gravitated toward biodegradable trays, cutlery, and films because they can be diverted into existing municipal or industrial composting streams without requiring new sorting infrastructure. Resin producers have responded by broadening PHA and PLA blend portfolios to close historical gaps in heat resistance and barrier performance, narrowing the cost and functionality difference with conventional plastics.
Non-biodegradable bio-based polymers, chiefly bio-PE and bio-PET, are growing fastest because they are chemically identical to their fossil-based counterparts and can be dropped directly into existing bottling, filling, and recycling infrastructure. Beverage brands in particular favor bio-PET for large-format bottles since it preserves recyclability claims while reducing reliance on virgin fossil feedstock. This drop-in compatibility lowers capital risk for converters, allowing faster volume ramp-up than biodegradable alternatives that often require new composting or handling logistics to fully realize their environmental benefit.
By Packaging Type, Flexible dominates, and Rigid grows fastest
Flexible bioplastic packaging, which includes pouches, sachets, wraps, and films, accounted for the highest market share in 2025 owing to low material density, flexibility in applications for foods and personal care products, and suitability for on-the-go consumption habits. Converters have favored flexible formats because they need less amount of resins compared to others and are highly suitable for meeting e-commerce shipping efficiency objectives because the lighter the package, the lower the cost and carbon emission involved in shipping. Biodegradable multilayer flexible formats, equipped with bio-based barrier technology, have reached sufficient levels of maturity to satisfy shelf-life demands for food categories that deteriorate easily.
Trays, bottles, tubs, and clamshells belong to the category of rigid bioplastic packaging, which is gaining popularity faster because of the rising regulatory pressures to replace single-use rigid plastics with biobased and compostable alternatives in food service and retail. Technological advancements in blends of PLA and PHA have made rigid bioplastics durable enough to be used in hot-fill and microwaveable applications that could only be met by conventional plastic containers. Private label packaging campaigns involving bio-based rigid trays for produce and bakery products have supported this trend.
By Application, Food & Beverages dominates, and Cosmetic & Personal Care grows fastest
The Food & Beverages segment had the highest market share in terms of applications in 2025 because of high volume requirements from fast food, retailing groceries, and food manufacturing businesses, as well as high regulatory interest in wastage of single-use food packaging. Compostable cups, trays, and wrapping have been making the companies' sustainability pledges evident and have been pushing big restaurant chains and grocery retailers to establish standards for bioplastic usage among their suppliers. High volume requirements enable resin makers to achieve reduced prices per unit due to learning curves.
The Packaging for Cosmetic & Personal Care Products segment has been growing at the fastest rate because luxury cosmetic and personal care product brands have started using bio-based materials in tubes, jars, and dispensers in order to highlight their sustainability credentials in a category where packaging design is important for brands. Small production volumes and higher prices make this application more forgiving in relation to additional expenses of bio-based resins compared to other segments, and brands can implement bioplastics before price equilibrium between bioplastics and conventional plastics in this segment is achieved.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
78.40 |
|
Europe |
Germany |
32.60 |
|
Asia Pacific |
China |
45.75 |
|
Middle East & Africa |
United Arab Emirates |
28.90 |
|
Latin America |
Brazil |
61.35 |
Europe Bioplastic Packaging Market Insights
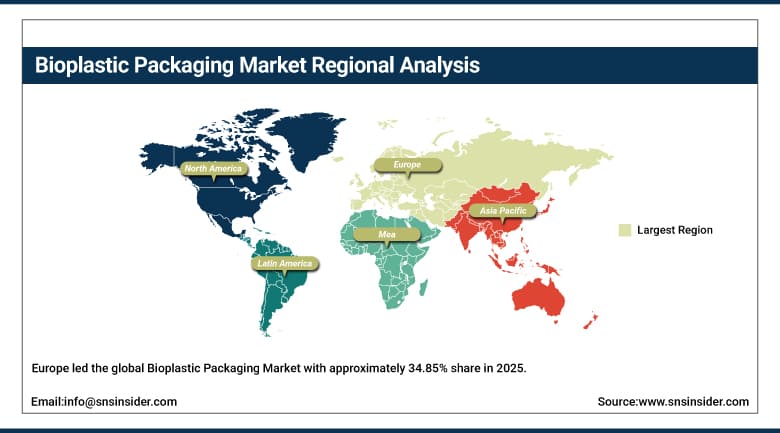
Europe led the global Bioplastic Packaging Market with approximately 34.85% share in 2025, underpinned by some of the world's strictest packaging waste regulations and a deeply established compostable materials industry centered in Italy, Germany, and France. The European Commission's Regulation (EU) 2025/40 on packaging and packaging waste entered into force on 11 February 2025 and will generally apply from 12 August 2026, tightening requirements across the full packaging life cycle and giving converters a firm compliance deadline to plan capital investment around. Producers such as Novamont, TotalEnergies Corbion, and Biome Bioplastics have built dense regional supply chains supplying compostable bags, food service ware, and agricultural films.
Germany anchors regional demand with a well-developed industrial composting network and strong retailer commitments to reduce single-use plastic across grocery and food service channels, while Italy retains deep manufacturing expertise following decades of leadership in compostable shopping bag mandates. France's extended producer responsibility framework and packaging labeling requirements are reinforcing demand for certified compostable formats. Continued regulatory tightening under the EU packaging and packaging waste rules is expected to keep Europe as the largest single regional market through the early years of the forecast period, even as Asia Pacific narrows the volume gap.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Bioplastic Packaging Market Insights
The Asia Pacific region represents the most rapidly growing region of the bioplastic packaging market, expected to grow with a CAGR of about 16.90% throughout the forecast period of 2026-2035, owing to the rapid build-up of capacities in China, Thailand, and India due to increased urban consumption of packaged foods and goods purchased online. China's domestic resin manufacturers have built up capacities of PLA and PBAT rapidly to support exports and fast growing internal demand due to China's bans on single-use plastics implemented in major cities.
Thailand is a manufacturing center in the region because of the availability of sugarcane and cassava as feedstocks which can be used to produce bio-based polymers competitively. India's own ban on single-use plastics along with setting itself up as a cheaper manufacturing base for exports to the region is contributing to new capacity in the country. In addition, Japan is leading in high-performing bio-based barrier films used in food packaging.
Increasing consumption by the middle class population, growing consciousness of pollution due to plastics in the coastal and riverside regions, and favorable industrial policies of the government supporting local bioplastics manufacturing are contributing to sustaining the region's growth above the average rate. Large multinational
North America Bioplastic Packaging Market Insights
North America held the third-largest share of the global market in 2025, supported by a mature compostable food service packaging segment and state-level extended producer responsibility laws that are pushing brand owners toward certified compostable and recyclable materials. The United States accounted for the substantial majority of regional demand, with domestic PLA and bio-PE capacity concentrated around agricultural feedstock supply in the Midwest and petrochemical infrastructure along the Gulf Coast. Canada's federal single-use plastics restrictions and growing municipal composting infrastructure are contributing incremental regional demand.
Corporate sustainability commitments from major U.S. retailers and quick-service restaurant chains continue to be the primary demand driver, converting packaging specifications toward bio-based and compostable alternatives across cups, trays, and cutlery. Investment in domestic PLA capacity, including new manufacturing lines announced by NatureWorks, is intended both to serve growing home-market demand and to position North American plants as export platforms supplying faster-growing regions overseas, reinforcing the region's role as a key production base as well as a consumption market.
MEA & Latin America Bioplastic Packaging Market Insights
The Middle East & Africa bioplastic packaging market remains at an early stage of development but is gaining traction as the United Arab Emirates and Saudi Arabia introduce single-use plastic bans and invest in downstream packaging manufacturing as part of broader economic diversification strategies. Regional demand is currently concentrated in food service and retail packaging within Gulf Cooperation Council states, supported by growing hospitality and tourism sectors that are adopting compostable serviceware to meet sustainability commitments tied to major international events and hospitality brand standards.
Latin America is anchored by Brazil, home to Braskem's large-scale bio-based polyethylene production drawing on the country's extensive sugarcane feedstock base, which supplies both domestic converters and export markets across the Americas and Europe. Brazilian producers are also expanding research into converting other agricultural residues beyond sugarcane into bioplastic feedstock, aiming to diversify input sources and create new revenue opportunities for rural producers. Mexico and Colombia are adding smaller-scale converting capacity to serve regional food and beverage packaging demand.
Market Dynamics:
Growth Drivers: Regulatory Restrictions on Single-Use Plastics
Tightening regulation is the single largest driver of bioplastic packaging adoption, with the European Union's Regulation (EU) 2025/40 on packaging and packaging waste, in force since 11 February 2025 and generally applicable from 12 August 2026, setting binding requirements across the packaging life cycle that extend well beyond earlier single-use plastics directives. Comparable measures are advancing across North American states and several Asia-Pacific markets, creating a compounding set of compliance deadlines that brand owners cannot address through voluntary sustainability initiatives alone. This regulatory convergence is forcing packaging specification changes at a pace that voluntary corporate commitments alone would not have achieved.
Because these rules carry defined compliance dates and, in several jurisdictions, financial penalties or extended producer responsibility fees tied to non-compostable or non-recyclable packaging, procurement teams are treating material transition timelines as a fixed cost of doing business rather than a discretionary sustainability investment. This has shifted purchasing conversations from brand marketing teams toward supply chain and legal functions, accelerating supplier qualification cycles for bioplastic converters and creating more predictable multi-year demand visibility that is, in turn, supporting capital investment decisions across the resin and converting value chain.
Restraints: Cost Premium and Feedstock Constraints
Bioplastic resins generally carry a cost premium over conventional polyolefins, driven by smaller production scale, higher feedstock costs, and, in the case of PHA, more complex fermentation-based manufacturing processes that have yet to reach the economies of scale enjoyed by petrochemical producers. This premium remains a meaningful barrier for cost-sensitive categories such as commodity retail bags and bulk food packaging, where margins are thin and buyers are reluctant to absorb material cost increases without a corresponding regulatory mandate or consumer willingness to pay.
Feedstock availability adds a further constraint, since PLA and bio-PE production depend on agricultural crops such as corn, sugarcane, and cassava that compete with food and animal feed markets for arable land and are exposed to weather-driven price volatility. Emerging feedstocks based on agricultural residues and non-food biomass are still scaling and have not yet resolved this tension at commercial volumes. Compostable packaging also requires access to industrial composting infrastructure that remains inconsistent across many municipalities, limiting the practical end-of-life benefit of biodegradable formats in regions lacking adequate collection and processing systems.
Opportunities: Drop-In Bio-Based Polymers and E-Commerce Packaging
Bio-based "drop-in" polymers like bio-PE and bio-PET are one of the biggest opportunities because they enable brand owners to cut down fossil-fuel based content without any change in filling machines, recyclability in the existing system, or look of the packaging material. The beverage and personal care brands have started to incorporate bio-based content into their existing PET and PE packaging to achieve the incremental step towards decarbonizing their manufacturing process. It creates the scope of scalability in the short term through growth without relying on the new end-of-life infrastructure for fully biodegradable plastics.
The growing trend of e-commerce provides another opportunity in terms of the use of lightweight flexible bioplastic mailers, void-fill, and protective packaging because of its lightness and availability in new compostable mailer formats. It meets the sustainability commitment of retailers as well as reduces shipping costs. There is also venture funding towards developing new barrier coatings like seaweed-based films to replace plastic-lined paper packaging materials, indicating future opportunities for developing more advanced materials.
Recent Developments:
-
October 2025- TIPA Compostable Packaging, together with its European subsidiary Bio4Pack, acquired SEALPAP, adding recyclable paper-based packaging capabilities to TIPA's compostable flexible-packaging portfolio.
-
February 2025- NatureWorks LLC entered a multi-year supply agreement with Mitsubishi Chemical Group to expand Ingeo PLA production capacity dedicated to Asia-Pacific export markets.
-
October 2023- Versalis S.p.A. completed the acquisition of the remaining 64% stake in Novamont S.p.A., raising its ownership from 36% to 100% and taking full control of the Mater-Bi resin business.
-
August 2023- Danimer Scientific launched an expanded line of bio-based resins engineered specifically for flexible packaging applications, broadening its product portfolio beyond rigid formats.
-
May 2024- Kelpi raised £4.35 million in funding to commercialize seaweed-derived barrier coatings for paper and cardboard packaging, targeting plastic-lined paper replacement applications.
Bioplastic Packaging Market Key Players:
-
BASF SE
-
Novamont S.p.A. (Versalis)
-
NatureWorks LLC
-
Braskem S.A.
-
Amcor plc
-
Mondi plc
-
Sealed Air Corporation
-
Smurfit WestRock plc
-
International Paper Company
-
Constantia Flexibles Group GmbH
-
Tetra Pak International S.A.
-
Huhtamaki Oyj
-
TIPA Corp Ltd.
-
Danimer Scientific, Inc.
-
TotalEnergies Corbion
-
Biome Bioplastics Limited
-
Plantic Technologies Limited
-
Mitsubishi Chemical Group Corporation
-
ProAmpac LLC
-
Coveris Holdings S.A.
Bioplastic Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 23.13 Billion |
| Market Size by 2035 | USD 83.84 Billion |
| CAGR | CAGR of 13.74% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Material Type (Biodegradable and Non-Biodegradable) • by Packaging Type (Flexible and Rigid) • by Application (Food & Beverages, Consumer Goods, Pharmaceuticals, Cosmetic & Personal Care, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | BASF SE, Novamont S.p.A. (Versalis), NatureWorks LLC, Braskem S.A., Amcor plc, Mondi plc, Sealed Air Corporation, Smurfit WestRock plc, International Paper Company, Constantia Flexibles Group GmbH, Tetra Pak International S.A., Huhtamaki Oyj, TIPA Corp Ltd., Danimer Scientific, Inc., TotalEnergies Corbion, Biome Bioplastics Limited, Plantic Technologies Limited, Mitsubishi Chemical Group Corporation, ProAmpac LLC, Coveris Holdings S.A. |
Frequently Asked Questions
Key players in the Bioplastic Packaging Market include BASF SE, Novamont S.p.A., NatureWorks LLC, Braskem S.A., and Amcor plc, among others.
Key opportunities lie in bio-based drop-in polymers such as bio-PE and bio-PET that require no change to existing filling and recycling infrastructure, growth in compostable e-commerce mailers and protective packaging, and emerging next-generation barrier materials such as seaweed-derived coatings.
Tightening single-use plastics regulation, most notably the EU's Regulation (EU) 2025/40 on packaging and packaging waste, is the major growth factor, compelling brand owners to transition toward compostable and bio-based packaging materials on fixed compliance timelines.
By Material Type, the Biodegradable segment dominated the Bioplastic Packaging Market with approximately 63.45% share in 2025.
Europe dominated the Bioplastic Packaging Market with approximately 34.85% share in 2025, driven by stringent packaging waste regulation and an established compostable materials manufacturing base.
