
Biorefinery Market Report Scope & Overview:
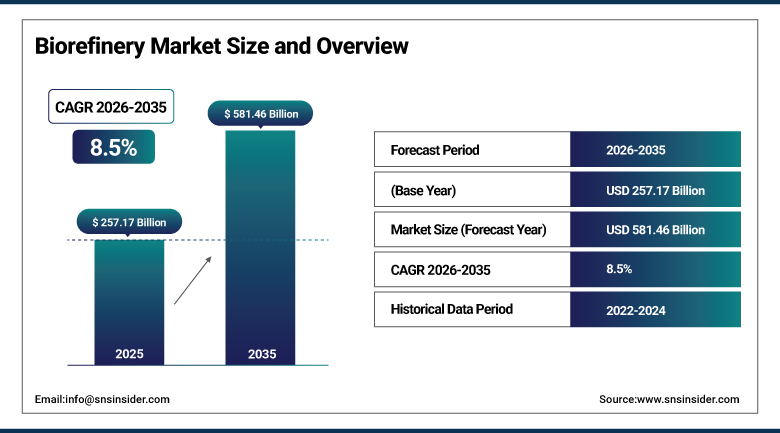
The Biorefinery Market was valued at USD 257.17 billion in 2025 and is projected to reach USD 581.46 billion by 2035, expanding at a CAGR of 8.5% during the forecast period.
Biorefineries consist of integrated plants that incorporate various biomass conversion technologies to produce biofuels, energy, heat, and valuable chemicals. With more awareness about global climate change issues and decreasing conventional fossil fuels, there is increasing investment in building biorefinery facilities, aided by stringent environmental policies and government mandates requiring blending of biofuels. The second generation of biorefinery technology also continues to receive considerable investment and subsidies from the government because there is a desire for diversification of fuels without posing a challenge to agriculture. According to the U.S. Department of Energy’s Bioenergy Technologies Office in January 2025, lignocellulosic biomass can be used in the production of up to 50 billion gallons of biofuels per year in the United States alone.
The European Biogas Association has indicated that by 2025, the total amount of biomethane produced in Europe was 7 billion cubic meters per year, showing the practical action taken by the industry to meet the increasing demand for energy security and sustainability.
To Get more information Biorefinery Market - Request Free Sample Report
Biorefinery Market Trends
- Rising investment in second-generation biorefinery capacity using non-food agricultural and forestry residues
- Growing development of third-generation algae-based biorefinery technology for higher-value product streams
- Increasing enzymatic hydrolysis efficiency improvements reducing lignocellulosic biomass conversion costs
- Rising government mandates and subsidies promoting biofuel blending across major transportation fuel markets
- Growing integration of multiple feedstock processing capability within single, flexible biorefinery facilities
- Expanding production of bio-based chemicals and materials alongside traditional biofuel and bioenergy output
The U.S. Market Outlook
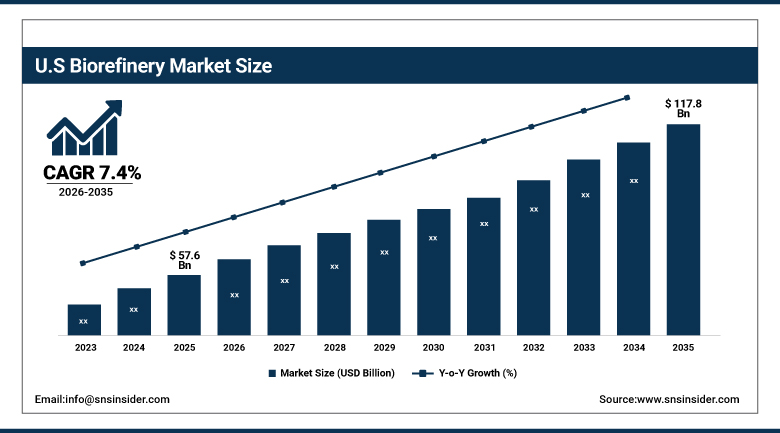
The U.S. biorefinery market was valued at USD 57.6 billion in 2025 and is projected to reach USD 117.8 billion by 2035, growing at a CAGR of 7.4% during 2026-2035.
There is the advantage of a highly developed first-generation ethanol manufacturing infrastructure present within the market of the United States, with further growing federal and state investment in the construction of second-generation biofuel and bio-based chemicals manufacturing capacity. According to the U.S. Department of Energy, biorefinery capacity utilization within the country was 78.3 percent in 2024, indicating that there is efficient use of the existing capacity despite ongoing new capacity investment. Federal renewable fuel standard mandates continue to anchor domestic ethanol and biodiesel demand, while growing state-level low-carbon fuel standard programs, particularly in California, are creating additional incentive for advanced second-generation and material-driven biorefinery product development beyond conventional transportation fuel applications.
According to International Energy Agency renewable energy data, biorefineries contributed approximately 15.8% of global renewable energy production during a recent quarter, with U.S. facilities representing a substantial share of this output given the country's extensive existing ethanol and biodiesel production infrastructure.
Biorefinery Market Segment Analysis
- By Type, the second generation segment dominated the biorefinery market with approximately 38.8% share in 2025, while the third generation segment is the fastest growing with a CAGR of approximately 11.4%.
- By Feedstock, the starch & sugar crops segment dominated the biorefinery market with approximately 38.6% share in 2025, while the lignocellulosic biomass segment is the fastest growing with a CAGR of approximately 10.8%.
- By Product, the energy-driven segment dominated the biorefinery market with approximately 54.3% share in 2025, while the material-driven segment is the fastest growing with a CAGR of approximately 10.6%.
By Type, Second Generation Dominates the Biorefinery Market While Third Generation Registers the Fastest Growth
Second Generation dominated the Biorefinery Market in 2025 due to the fact that significant government investment and subsidies continue to promote cellulosic ethanol fuel production using non-food plant biomass such as agricultural residues and wood residuals, reflecting policymaker priority on enhancing energy security and diversifying fuel sources without competing with food production, a concern that limits first-generation biofuel expansion.
Third Generation is the fastest-growing segment in the Biorefinery Market due to the fact that algae-based feedstocks offer substantially higher per-acre biomass yield and the potential for higher-value co-products, including specialty lipids and proteins, than conventional land-based crops. There is increasing research and pilot-scale investment in algae cultivation and conversion technology as the segment moves from early-stage demonstration toward initial commercial-scale deployment.
By Feedstock, Starch & Sugar Crops Dominates the Biorefinery Market While Lignocellulosic Biomass Registers the Fastest Growth
Starch & Sugar Crops dominated the Biorefinery Market in 2025 due to the fact that sugarcane and corn feedstocks benefit from established, cost-effective conversion processes and decades of global production infrastructure, sustaining strong demand from first-generation ethanol producers across major markets including the United States, Brazil, and the European Union.
Lignocellulosic Biomass is the fastest-growing segment in the Biorefinery Market due to the fact that this feedstock category offers widespread availability and lower feedstock costs compared to food-based alternatives, while continuous technological advancement in pretreatment and enzymatic hydrolysis processes continues to improve conversion efficiency and reduce the cost gap with more established feedstock types.
By Product, Energy-Driven Dominates the Biorefinery Market While Material-Driven Registers the Fastest Growth
Energy-Driven dominated the Biorefinery Market in 2025 due to the fact that biofuel and bioenergy production remains the largest and most established biorefinery output category, driven by increasing demand for sustainable energy solutions and stringent environmental regulations promoting renewable fuel blending mandates across major transportation fuel markets worldwide.
Material-Driven is the fastest-growing segment in the Biorefinery Market due to the fact that biorefinery operators are increasingly diversifying into bio-based chemicals, bioplastics, and specialty materials that command higher margins than commodity biofuel production, allowing integrated facilities to improve overall economics by processing biomass into multiple valuable product streams rather than energy output alone.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
78.0% |
|
Europe |
Germany |
27.0% |
|
Asia Pacific |
China |
39.0% |
|
Middle East & Africa |
South Africa |
18.0% |
|
Latin America |
Brazil |
52.0% |
North America Biorefinery Market Insights
North America's market benefits from an extensive existing ethanol and biodiesel production base, supported by federal renewable fuel standard mandates and growing state-level low-carbon fuel standard programs driving continued capacity investment.
Biorefinery capacities in Canada are continually growing based on forestry residue and agricultural waste, using the advantage of the huge Canadian forest products industry by-product supplies for increasing second-generation biofuel production. Biorefinery capacity in Mexico is still relatively low compared to that of the U.S. and Brazil, although increasing biofuel policies in the region are slowly building investor interests in production capacity.
Europe Biorefinery Market Insights
The European market is influenced by the goals set out in the EU Renewable Energy Directive and the growing capacity of biomethane production, where Germany, France, and the Netherlands are key investors in biorefineries technologies both conventional and advanced.
Investment in biorefinery technologies in France and the Netherlands is growing along with Germany, through financial means from the EU level for advanced biofuels and bio-based chemicals.
Asia Pacific Biorefinery Market Insights
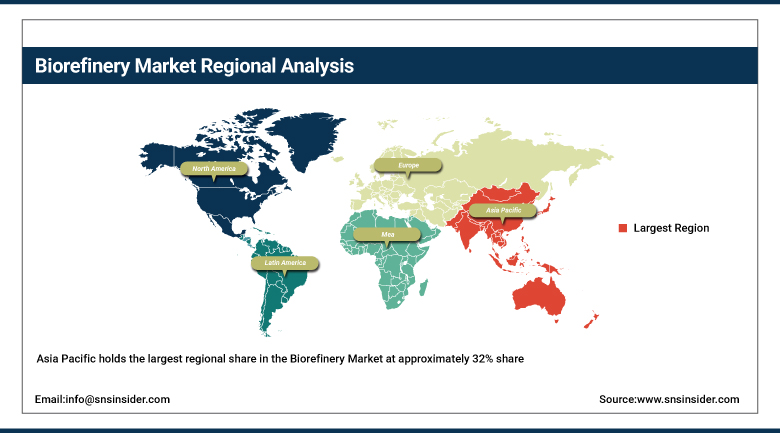
Asia Pacific holds the largest regional share in the Biorefinery Market at approximately 32% share, attributed majorly to increasing demand for limiting fossil fuel reliance and expanding domestic biofuel production capacity across China, India, and Southeast Asian markets.
The growth in Chinese biorefineries is growing steadily through biofuel blending mandates at the national level along with increased use of agricultural residue-based biorefineries in India. However, the growth in Indian biorefineries is largely through sugarcane-based ethanol biorefineries in support of the biofuel blending mandate of the country. Biorefineries in the Southeast Asian region, through palm oil and agricultural residue-based biorefineries, have continued to grow in Malaysia, Indonesia, and Thailand.
Get Customized Report as per Your Business Requirement - Enquiry Now
Middle East & Africa Biorefinery Market Insights
The Middle East & Africa region is growing steadily as South African and select Gulf state biorefinery pilot projects advance, though the region remains at an earlier stage of biorefinery infrastructure development relative to more established global markets.
South African biorefinery pilot projects continue to explore sugarcane and forestry residue feedstock utilization, targeting both domestic renewable fuel supply and export potential as regional infrastructure investment expands over the coming decade.
Latin America Biorefinery Market Insights
Latin America is the fastest-growing region in the Biorefinery Market, led overwhelmingly by Brazil, which operates one of the world's largest sugarcane-based ethanol production industries and continues to expand advanced biorefinery capacity incorporating both energy and material-driven product diversification.
Argentine and Colombian biorefinery investment continues to grow, supported by both countries' substantial agricultural feedstock availability and expanding regional biofuel blending mandate programs following Brazil's established policy framework.
Market Dynamics
Growth Drivers: Climate policy and energy security concerns sustaining renewable feedstock investment
The increasing global recognition of the effects of climate change as well as the diminishing supplies of traditional fossil fuel sources have continued to push investments into biorefinery infrastructures, with the support of strong environmental laws and decarbonization goals in various major economies around the world. The increasing need for energy security on account of the environmental and geopolitical reasons has continued to encourage governmental and corporate investments in domestic biorefineries. Regulatory incentives and biofuel blending mandates across major transportation fuel markets, including the United States, Brazil, and the European Union, continue to provide durable, policy-reinforced demand for biorefinery output independent of broader commodity price cycles.
Continuous technological advancement in biomass pretreatment and enzymatic hydrolysis efficiency is steadily improving the cost competitiveness of second-generation and lignocellulosic feedstock conversion relative to established first-generation production methods. Growing corporate sustainability commitments among major consumer goods and chemical companies continue to drive demand for bio-based feedstock alternatives to petroleum-derived materials, creating additional offtake demand for biorefinery material-driven product output beyond traditional bioenergy applications. Growing venture capital and government grant funding directed toward advanced biofuel and bio-based chemical startups continues to accelerate the pace of technology commercialization, particularly for third-generation algae-based and gas fermentation conversion approaches still moving from pilot to commercial scale.
Restraints: High establishment costs and feedstock supply chain complexity limiting expansion
High initial costs due to the high cost of constructing a biorefinery facility have made it difficult for small or less developed markets to access such a facility, given the high level of capital investment needed in setting up biomass-conversion facilities that can handle more than one stream of feedstock and products. Relying on complicated feedstock supply chains and availability poses risks to biorefinery companies, especially those that depend on agricultural residues.
Volatile agricultural commodity pricing for first-generation feedstocks including corn and sugarcane continues to create input cost uncertainty that can compress biorefinery operating margins during periods of elevated crop prices driven by broader food market dynamics. Land use change concerns associated with expanding dedicated energy crop cultivation continue to generate environmental and food security scrutiny in some markets, occasionally slowing regulatory approval and public acceptance of new first-generation biorefinery capacity expansion.
Opportunities: Algae-based technology and bio-based material diversification widening addressable demand
Continued advancement of third-generation algae-based biorefinery technology presents a significant long-term opportunity, given algae's substantially higher per-acre biomass yield potential and capacity for higher-value specialty co-products relative to conventional land-based crop feedstocks. Growing diversification into bio-based chemicals, bioplastics, and specialty materials presents an opportunity for biorefinery operators to improve overall facility economics by capturing higher-margin material-driven product revenue alongside conventional bioenergy output.
Expanding lignocellulosic biomass conversion capability, supported by continued enzymatic hydrolysis efficiency improvements, presents an opportunity to unlock the substantial biofuel production potential available from agricultural residues without competing with food crop production. Growing interest in sustainable aviation fuel production, which relies heavily on advanced biorefinery conversion technology, presents a substantial emerging opportunity as airlines and regulators worldwide increasingly commit to blending mandates for lower-carbon aviation fuel alternatives. Growing interest among oil and gas majors in co-locating renewable fuel production alongside existing refining infrastructure presents an opportunity for biorefinery technology providers to access established distribution networks and blending infrastructure without requiring entirely new supply chain development.
Recent Developments
- 2025: the U.S. Department of Energy's Bioenergy Technologies Office reported that lignocellulosic feedstocks could potentially support production of 50 billion gallons of biofuels annually in the United States.
- 2024: the European Commission's Joint Research Centre reported that enzymatic hydrolysis efficiency for lignocellulosic biomass had increased by 35% over the prior two years, reflecting continued conversion technology improvement.
- 2024: POET LLC expanded its second-generation cellulosic ethanol production capacity in the United States, targeting increased agricultural residue feedstock utilization.
- 2024: Chevron Renewable Energy Group expanded its renewable diesel production capacity in the United States, incorporating diverse waste oil and agricultural residue feedstock streams.
- 2024: Gevo Inc. expanded its sustainable aviation fuel production partnership agreements, targeting growing airline industry demand for lower-carbon aviation fuel alternatives.
Biorefinery Market Key Players are:
- POET LLC
- Archer-Daniels-Midland Company
- Neste Corporation
- Raízen S.A.
- Valero Energy Corporation
- Cargill Incorporated
- DuPont Industrial Biosciences
- Novozymes A/S
- Total Corbion PLA
- BASF SE
- Braskem S.A.
- Chevron Renewable Energy Group
- Green Plains Inc.
- Gevo Inc.
- LanzaTech Inc.
- Clariant AG
- UPM-Kymmene Corporation
- Stora Enso Oyj
- Marquis Energy LLC
- Abengoa Bioenergy
Biorefinery Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 257.17 Billion |
| Market Size by 2035 | USD 581.46 Billion |
| CAGR | CAGR of 8.5% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (First Generation, Second Generation, Third Generation) • By Feedstock (Starch & Sugar Crops, Lignocellulosic Biomass, Algae, Organic & Agricultural Residues, Used Cooking Oil & Vegetable Oils, Others) • By Product (Energy-Driven, Material-Driven) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | POET LLC, Archer-Daniels-Midland Company, Neste Corporation, Raízen S.A., Valero Energy Corporation, Cargill Incorporated, DuPont Industrial Biosciences, Novozymes A/S, Total Corbion PLA, BASF SE, Braskem S.A., Chevron Renewable Energy Group, Green Plains Inc., Gevo Inc., LanzaTech Inc., Clariant AG, UPM-Kymmene Corporation, Stora Enso Oyj, Marquis Energy LLC, Abengoa Bioenergy. |
Frequently Asked Questions
Leading companies include POET LLC, Archer-Daniels-Midland Company, Neste Corporation, Raízen S.A., and Valero Energy Corporation, among other major integrated energy and agricultural processing companies.
Opportunities include continued advancement of third-generation algae-based biorefinery technology, growing diversification into bio-based chemicals and specialty materials, and expanding lignocellulosic biomass conversion capability.
Growth is driven by increased global climate change awareness and declining fossil fuel reserves, growing energy security concerns, regulatory biofuel blending mandates, and continuous technological advancement improving conversion efficiency.
Second Generation dominates by type with approximately 38.8% share.
Asia Pacific is the largest regional market with approximately 32% share, led by China.
