
Bottled Water Market Report Scope & Overview:
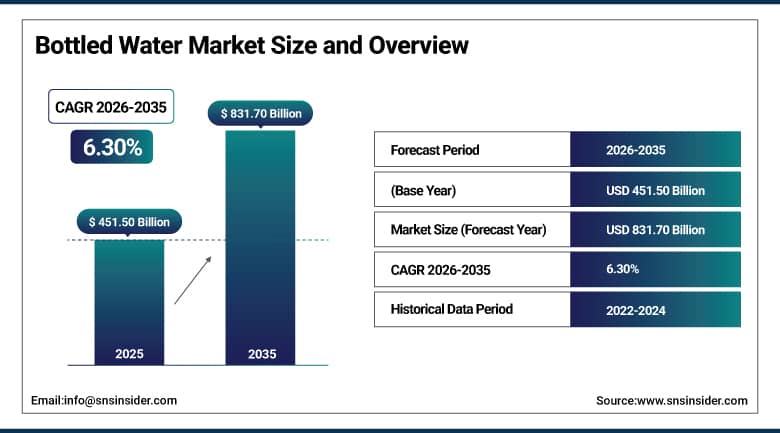
The global Bottled Water Market was valued at USD 451.50 Billion in 2025 and is expected to reach USD 831.70 Billion by 2035, growing at a CAGR of 6.30% from 2026 to 2035.
The growth of the Bottled Water Market is fueled by consumer demand for convenient, safe, and portable drinking water. Consumer inclination towards bottled water against sweetened drinks is due to the increase in urbanization and their awareness regarding health and lifestyle changes. Consumers are also more concerned about water quality and availability which is driving the demand for bottled water products. Innovative products such as sparkling water, mineral water, and functional water are providing new options for consumers, along with adding premium features to bottled water products. Availability through the expansion of superstores, convenience stores, foodservices, and online stores is another factor which is boosting the demand for bottled water. Additionally, disposable income, tourism, and foodservice operations are also contributing to demand in this market.
BlueTriton Brands and Primo Water completed their merger in 2024, creating a USD 6.5 billion North American hydration powerhouse bringing together nearly two dozen water brands including Poland Spring and Pure Life, with the combined entity focusing on cost synergies through shared bottling and logistics alongside a unified approach to sustainability reporting, reflecting the accelerating pace of consolidation among leading bottled water suppliers as retail sales of bottled water have grown from USD 17 billion in 2018 to USD 25 billion more recently.
To Get More Information On Bottled Water Market - Request Free Sample Report
Bottled Water Market Trends
-
Growing tightening of municipal water quality standards across both developed and emerging economies continues accelerating packaged water adoption.
-
Rising demand for electrolyte-enhanced, vitamin-fortified, alkaline, and immunity-positioned functional water continues to reshape category innovation priorities.
-
Expanding capacity additions and modernization programs continue concentrating near large demand centers to reduce logistics costs and protect service levels.
-
Increasing bio-based PET materials and cutting-edge barrier coatings continue striving to close the sustainability gap without sacrificing cost competitiveness.
-
Growing premium and luxury bottled water categories continue harnessing successful differentiation strategies that elevate basic hydration to wellness-centric choices.
U.S. Bottled Water Market Outlook
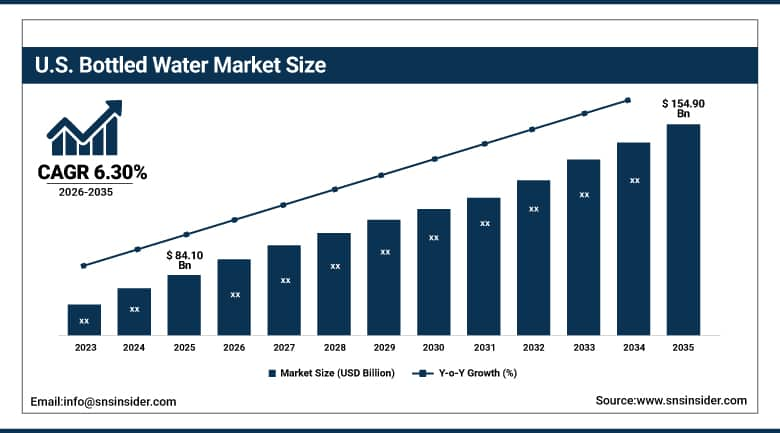
The U.S. Bottled Water Market was valued at USD 84.10 Billion in 2025 and is projected to reach USD 154.90 Billion by 2035, growing at a CAGR of 6.30% during 2026-2035.
The growth of the U.S. Bottled Water Market is mainly due to the growing consumer inclination towards the convenient and healthy option of consuming water. Health consciousness is making consumers inclined to move away from carbonated soft drinks and sugary drinks and opt for bottled water. The growing demand for purified water, mineral water, sparkling water, and functional water is helping the industry in product diversification and premiumization. The growing lifestyle trends such as hectic lives, urbanization, and growing on-the-go consumption habits are adding up to the demand. Wide availability through supermarkets, convenience stores, restaurants, vending machines, and online retail portals is making the product accessible. Moreover, growing outdoor activities and travel are helping in the growing consumption of the product.
Niagara Bottling announced a USD 160 million manufacturing and warehousing facility in Fulton County, New York in April 2026, targeting operations in early 2027 and reinforcing continued investment in North American production footprints as packaging and compliance requirements continue tightening across the domestic bottled water industry.
Bottled Water Market Segment Analysis
-
By Product Type, Purified/Still Water led the Bottled Water Market with a 41.90% share in 2025, while Functional Water is the fastest-growing product type segment with a CAGR of 10.18% from 2026-2035.
-
By Packaging Type, PET Bottles led the Bottled Water Market with a 79.90% share in 2025, while Metal Cans is the fastest-growing packaging type segment with a CAGR of 8.60% from 2026-2035.
-
By Distribution Channel, Off-Trade led the Bottled Water Market with a 89.70% share in 2025, while On-Trade is the fastest-growing distribution channel segment with a CAGR of 7.40% from 2026-2035.
-
By Price Range, Mass Market led the Bottled Water Market with a 88.74% share in 2025, while Premium is the fastest-growing price range segment with a CAGR of 6.50% from 2026-2035.
By Product Type, Purified/Still Water Dominated the Market While Functional Water Is the Fastest-Growing Segment
The Purified/Still Water segment led the Bottled Water Market with a revenue share of 41.90% in 2025, driven by its widespread consumer preference for natural-tasting, calorie-free hydration and its availability across various retail and distribution channels. Still water continues to be preferred for daily hydration, making it a staple in households, offices, and public spaces, sustaining this product type's dominant position across the broader bottled water market worldwide.
The Functional Water segment is expected to register the fastest CAGR of 10.18% during the forecast period 2026-2035, supported by increased demand for electrolyte-enhanced, vitamin-fortified, alkaline, and immunity-positioned hydration solutions. Growing consumer interest in wellness-centric lifestyle choices continues to reinforce this segment's above-average growth trajectory relative to conventional still and sparkling water categories.
By Packaging Type, PET Bottles Dominated the Market While Metal Cans Is the Fastest-Growing Segment
The PET Bottles segment led the Bottled Water Market with a revenue share of 79.90% in 2025, reflecting PET's considerably lighter weight relative to metal cans and glass bottles, which minimizes fuel consumption and transportation costs across the distribution chain. PET bottles continue to offer manufacturers cost efficiency and distribution scalability, sustaining this packaging type's dominant position across the broader bottled water market worldwide despite growing sustainability scrutiny.
The Metal Cans segment is expected to register the fastest CAGR of 8.60% during the forecast period 2026-2035, driven by growing interest in aluminum cans as both eco-friendly and affordable packaging options relative to conventional plastic alternatives. Rising environmentally conscious consumer preference for recyclable packaging continues to reinforce this segment's above-average growth trajectory relative to established PET and glass bottle formats.
By Distribution Channel, Off-Trade Dominated the Market While On-Trade Is the Fastest-Growing Segment
The Off-Trade segment led the Bottled Water Market with a revenue share of 89.70% in 2025, reflecting the robust network of retail outlets including supermarkets, hypermarkets, and convenience stores providing multiple accessible touchpoints for bottled water purchases. Off-trade channels continue to offer consumers accessible single-serve or bulk pack purchasing options for both at-home and on-the-go consumption, sustaining this channel's dominant position across the broader bottled water market worldwide.
The On-Trade segment is expected to register the fastest CAGR of 7.40% during the forecast period 2026-2035, driven by hotels, restaurants, bars, and cafes providing meaningful opportunities for premium and functional water brands to gain visibility among affluent, experience-focused consumers. Growing hospitality sector premiumization continues to reinforce this segment's above-average growth trajectory relative to the more established off-trade retail channel.
By Price Range, Mass Market Dominated the Market While Premium Is the Fastest-Growing Segment
The Mass Market segment led the Bottled Water Market with a revenue share of 88.74% in 2025, driven by volume strategies targeting price-sensitive consumers across both developed and emerging markets. Mass market pricing continues to command the overwhelming majority of bottled water consumption globally, sustaining this price range's dominant position across the broader bottled water market worldwide.
The Premium segment is expected to register the fastest CAGR of 6.50% during the forecast period 2026-2035, fueled by growing consumer interest in health, wellness, and sustainability, with many consumers increasingly seeking high-quality, mineral-rich, or specialty waters offering perceived health benefits. Rising eco-conscious buyer preference for brands prioritizing sustainable packaging and ethical practices continues to reinforce this segment's above-average growth trajectory relative to mass market pricing.
Regional Insights
|
Region |
Country |
Share (2025) |
|---|---|---|
|
Asia Pacific |
China |
34.60% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
22.80% |
|
Middle East & Africa |
UAE |
20.60% |
|
Latin America |
Brazil |
24.60% |
Asia Pacific Bottled Water Market Insights
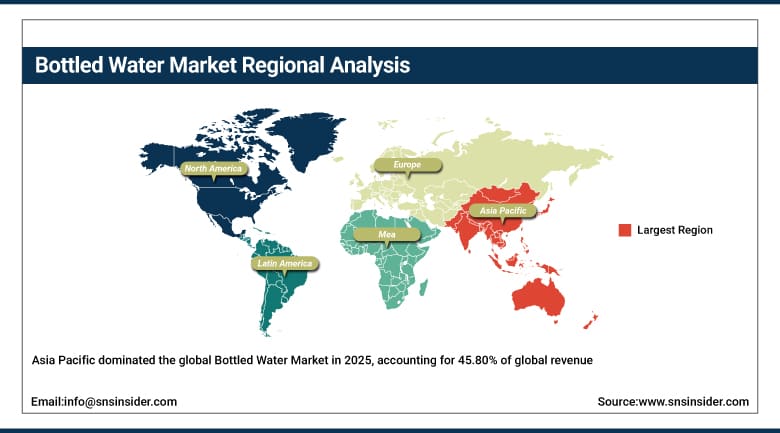
Asia Pacific dominated the global Bottled Water Market in 2025, accounting for 45.80% of global revenue, driven by rising health and wellness awareness, increasing demand for convenient hydration, and continuous product innovation. Rapid urbanization and population growth across China, India, and Indonesia are expanding the consumer base, while rising disposable incomes are supporting greater spending on packaged beverages. Expanding modern retail networks and e-commerce platforms are improving product accessibility across the region. Growing consumer preference for purified, mineral, sparkling, and functional water products is further supporting market expansion. Asia Pacific is also expected to register the fastest CAGR during 2026–2035, reinforcing its leading position in the global market.
China accounted for approximately 34.60% of the Asia Pacific market in 2025, supported by its massive consumer base and rapidly expanding domestic bottled water manufacturing capacity, led by companies including Nongfu Spring. India, Japan, and Indonesia are also contributing meaningfully to regional growth, with rising demand for safe drinking water reinforcing sustained regional consumption.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Bottled Water Market Insights
North America held a significant share of the global Bottled Water Market in 2025, supported by advanced production infrastructure, extensive distribution networks, and a strong presence of leading bottled water suppliers. Intense competition across mass-market and premium segments is encouraging product innovation and brand diversification. Continued industry consolidation and major merger activity among leading regional operators are strengthening market concentration and operational scale. Established retail channels, rising consumer demand for convenient hydration, and growing preference for premium and functional water products further reinforce North America’s strategic importance in the global bottled water industry.
The United States accounted for approximately 84.60% of the North American market in 2025, reflecting its large health-conscious consumer base and concentration of leading bottled water brands. Canada is contributing to regional growth through steady bottled water adoption and growing consumer interest in functional and premium hydration alternatives.
Europe Bottled Water Market Insights
Europe held a meaningful share of the global Bottled Water Market in 2025, supported by stringent environmental regulations and strong consumer preference for naturally sourced, mineral-rich water. Accelerating adoption of recycled and eco-friendly packaging is encouraging manufacturers to invest in sustainable bottling solutions. The region’s established premium mineral water heritage across major producing countries continues to support steady consumption. Rising health consciousness, tourism, hospitality activity, and demand for premium bottled water are further strengthening regional demand, while advanced retail infrastructure ensures broad product availability across European markets.
Germany led the European market with a 22.80% regional share in 2025, supported by its strong mineral water production base and concentration of leading bottled water brands including Gerolsteiner. France, Italy, and Switzerland are also contributing meaningfully to regional growth, supported by globally renowned premium mineral water brands headquartered across the region.
Middle East & Africa and Latin America Bottled Water Market Insights
The Middle East & Africa region is exhibiting steady growth as high disposable income and premium retail infrastructure investment continue expanding across the Gulf states. Latin America is similarly benefiting from expanding modern retail penetration and growing consumer interest in naturally sourced, functional hydration products.
The UAE led the Middle East & Africa market with a 20.60% regional share in 2025, supported by strong luxury consumer spending and expanding premium retail penetration. Brazil represented 24.60% of the Latin American market in 2025, driven by expanding bottled water consumption, with Mexico also contributing to regional growth through rising demand for safe, convenient drinking water.
Growth Drivers: Health Consciousness and Functional Water Innovation Driving Market Growth
The Bottled Water Market is being driven primarily by growing health awareness, environmental concerns, and a shift away from sugary drinks. The rising demand for premium and functional water, along with eco-friendly packaging and increasing urbanization, continues to boost bottled water market share, as the increasing awareness about health and wellness among consumers has compelled them to switch from the consumption of sugary beverages toward healthier hydration alternatives.
Growing tightening of municipal water quality standards across both developed and emerging economies continues accelerating packaged water adoption. Rising demand for electrolyte-enhanced, vitamin-fortified, alkaline, and immunity-positioned functional water continues to reshape category innovation priorities. Expanding capacity additions and modernization programs continue concentrating near large demand centers, reinforcing sustained industry investment across major consuming markets.
Restraints: Sustainability Criticism and Plastic Pollution Concerns Limiting Market Expansion
Despite favorable underlying demand, the market faces meaningful restraints related to persistent sustainability criticism, with major bottled water companies estimated to contribute hundreds of millions of pounds of plastic to landfills annually despite public sustainability pledges. Rising public awareness of the role played by bottled water companies in the plastic pollution crisis continues to pressure companies to demonstrate credible, verifiable environmental performance rather than aspirational marketing claims.
Regulatory scrutiny of water extraction practices, including concerns over aquifer depletion and unauthorized water sourcing from protected natural areas, continues to create reputational and operational risk for major bottled water producers. Growing competitive intensity among an expanding roster of suppliers, particularly amid aggressive consolidation activity, also continues to compress margins across mass-market bottled water categories.
Opportunities: Functional Hydration Expansion and Sustainable Packaging Investment Creating New Growth Avenues
Substantial opportunity exists in continued development of functional water formulations incorporating electrolytes, vitamins, and immunity-positioned ingredients capable of commanding premium pricing beyond conventional still and sparkling formats. Companies that successfully commercialize differentiated, health-benefit-oriented water products stand to capture significant share of category growth as consumers increasingly seek more than basic hydration.
Growing investment in bio-based PET materials and cutting-edge barrier coatings presents a further significant growth avenue, as manufacturers strive to close the sustainability gap without sacrificing cost competitiveness. Expanding capacity investment near large demand centers across emerging markets in Asia Pacific and Latin America also represents meaningful untapped opportunity for bottled water manufacturers.
Recent Developments:
-
2026: Suntory PepsiCo inaugurated a USD 300 million bottled water plant in Tay Ninh, Vietnam, with annual capacity of about 1.244 billion liters.
-
2024: Danone introduced vitamin-infused water targeting the fitness segment, contributing to a 15% sales boost.
-
2024: PepsiCo unveiled its first plant-based bottle for Aquafina, reducing packaging emissions by 20%.
-
2024: Coca-Cola expanded its smart water lineup with advanced hydration technology, boosting functional water sales by 25%.
Bottled Water Companies are:
-
Nestlé S.A.
-
Danone S.A.
-
PepsiCo, Inc.
-
The Coca-Cola Company
-
Primo Brands Corporation
-
FIJI Water Company LLC
-
Gerolsteiner Brunnen GmbH & Co. KG
-
VOSS Global Inc.
-
National Beverage Corp.
-
Keurig Dr Pepper Inc.
-
Suntory Beverage & Food Limited
-
Bisleri International Pvt. Ltd.
-
Niagara Bottling LLC
-
Highland Spring Group
-
Icelandic Glacial Inc.
-
Spadel S.A.
-
Vichy Catalan Corporation
-
Ferrarelle S.p.A.
Bottled Water Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 451.50 Billion |
| Market Size by 2035 | USD 831.70 Billion |
| CAGR | CAGR of 6.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Purified/Still Water, Sparkling Water, Mineral Water, Functional Water) • By Packaging Type (PET Bottles, Glass Bottles, Metal Cans) • By Distribution Channel (Off-Trade, On-Trade) • By Price Range (Mass Market, Premium) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Nestlé S.A., Danone S.A., PepsiCo, Inc., The Coca-Cola Company, Primo Brands Corporation, Nongfu Spring Co., Ltd., FIJI Water Company LLC, Gerolsteiner Brunnen GmbH & Co. KG, VOSS Global Inc., National Beverage Corp., Keurig Dr Pepper Inc., Suntory Beverage & Food Limited, Bisleri International Pvt. Ltd., Ganten Group, Niagara Bottling LLC, Highland Spring Group, Icelandic Glacial Inc., Spadel S.A., Vichy Catalan Corporation, Ferrarelle S.p.A. |
Frequently Asked Questions
The Bottled Water Market is expected to grow at a CAGR of 6.30% from 2026 to 2035.
The Bottled Water Market was valued at USD 451.50 Billion in 2025.
The market is driven by growing health awareness, environmental concerns, and a shift away from sugary drinks toward healthier hydration alternatives.
The Purified/Still Water segment dominated the Bottled Water Market in 2025, accounting for approximately 41.90% market share.
The Asia Pacific region dominated the Bottled Water Market in 2025, accounting for approximately 45.80% market share.
