
Cladding Systems Market Report Scope & Overview:
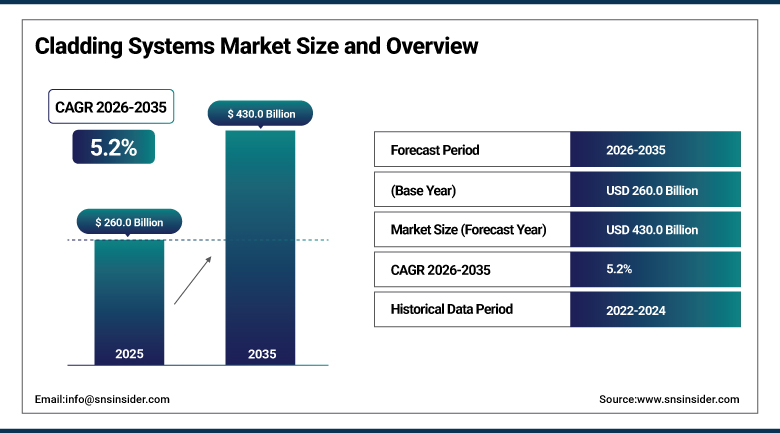
The Cladding Systems Market was valued at USD 260.0 Billion in 2025 and is expected to reach USD 430.0 Billion by 2035, growing at a CAGR of 5.2% from 2026–2035.
Expansion of the Cladding Systems Market is attributed to increased constructions, urbanization and growing need for robust and energy efficient building facades. Increased construction activities in residential, commercial and industrial infrastructure is contributing towards the uptake of modern cladding systems. With increasing importance being accorded to thermal insulation, weather resistance, fire resistance and energy efficiency, there are incentives for builders to substitute traditional building facades with advanced solutions. Building renovations and retrofits are providing additional impetus to growth due to the need to improve existing facades both functionally and aesthetically. In addition, innovations in lightweight composite panels, ventilated facades, fiber cement and sustainable materials are providing additional avenues for expansion.
In early 2025, Centria unveiled an insulated metal panel with integrated solar technology, embedding photovoltaic capability directly into a building's exterior wall system rather than treating solar panels as a separate rooftop addition. The product reflects a broader shift in how architects and developers think about a building's envelope: not just protection from the elements, but active infrastructure that can generate power, manage insulation, and meet increasingly strict energy codes all at once.
To Get more information Cladding Systems Market - Request Free Sample Report
Cladding Systems Market Trends
-
Fire-safety-focused, non-combustible cladding materials continue gaining specification share as building codes tighten worldwide following high-profile cladding fire incidents that exposed the real-world risk of certain composite panel constructions.
-
Ventilated, rainscreen cladding systems are becoming a mainstream specification rather than a premium option, valued for the moisture management and energy performance advantages they offer over traditional face-sealed systems.
-
Prefabricated and modular cladding panels continue reducing on-site labor requirements and installation time, an increasingly important advantage as skilled construction labor remains difficult to source in many major markets.
-
Building envelope retrofits are becoming a larger share of overall cladding demand as aging building stock in developed markets faces growing pressure to meet modern energy-efficiency and fire-safety standards without full reconstruction.
-
Composite panel manufacturers are advancing mono-material and more easily recyclable constructions, aimed at improving end-of-life recyclability without sacrificing the weather performance the category is known for.
U.S. Cladding Systems Market Outlook
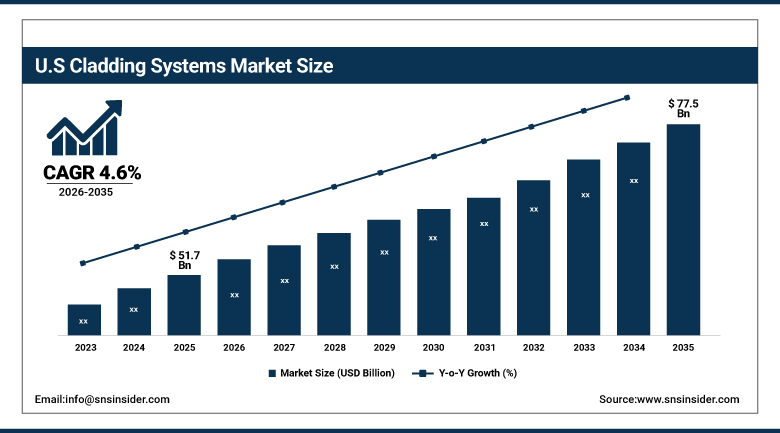
The U.S. Cladding Systems Market was valued at approximately USD 51.7 Billion in 2025 and is expected to reach approximately USD 77.5 Billion by 2035, growing at a CAGR of approximately 4.6%.
Demand in the United States is shaped heavily by federal and state green-building initiatives alongside strict fire and building-performance codes that favor non-combustible and high-performance cladding across residential, commercial, and institutional construction. A large existing building stock is making renovation economics nearly as important a driver as new construction, particularly in older urban markets where full reconstruction rarely pencils out financially. Metal and composite panel systems continue gaining share as manufacturers offer more energy-efficient and code-compliant product lines.
OmniMax International invested in a new manufacturing facility in North America in 2025, expanding domestic production capacity for metal cladding systems to meet growing demand from both new construction and the wave of building envelope retrofits driven by tightening state and federal energy codes.
Cladding Systems Market Segment Analysis
-
By Material, the Metal segment dominated the Cladding Systems Market with approximately 26.4% share in 2025, while the Composite Panels segment is the fastest growing with a CAGR of approximately 6.9%.
-
By Type, the Walls segment dominated the Cladding Systems Market with approximately 64.0% share in 2025, while the Roofs segment is the fastest growing with a CAGR of approximately 6.4%.
-
By Application, the Non-Residential segment dominated the Cladding Systems Market with approximately 58.0% share in 2025, while the Residential segment is the fastest growing with a CAGR of approximately 6.2%.
-
By Installation Type, the Non-Ventilated Cladding segment dominated the Cladding Systems Market with approximately 54.0% share in 2025, while the Ventilated/Rainscreen Cladding segment is the fastest growing with a CAGR of approximately 7.4%.
-
By Building Type, the New Construction segment dominated the Cladding Systems Market with approximately 61.0% share in 2025, while the Renovation & Retrofit segment is the fastest growing with a CAGR of approximately 6.8%.
By Material, metal dominates, composite panels grow fastest
Metal cladding held the largest share of the material segment in 2025, with aluminum, steel, zinc, and copper systems favored wherever weather resistance, corrosion protection, and non-combustible performance are central to a project's specification. Its long service life and broad availability across price points keep metal cladding the default choice across a wide range of building types.
Composite panels are growing fastest as their lighter weight, design flexibility, and improving fire-safety formulations continue winning share from traditional materials on major commercial and institutional projects. Manufacturers investing in mono-material and more easily recyclable composite constructions are helping the category address the sustainability and fire-safety concerns that once limited its broader adoption.
By Type, walls dominates, roofs grows fastest
Wall cladding accounted for the large majority of the type segment in 2025, reflecting its central role in defining a building's visual identity and weather protection across nearly every construction project. The sheer surface area walls represent relative to roofs keeps this the dominant application by a wide margin.
Roof cladding is growing fastest as insulated metal panel systems and integrated solutions, including panels with embedded solar technology, continue expanding what a roof cladding system can accomplish beyond basic weatherproofing. That expanded functionality is pulling roof cladding investment upward faster than the broader, more mature wall cladding category.
By Application, non-residential dominates, residential grows fastest
The non-residential segment comprised the biggest share of the market in 2025 on account of the high volume of material used and the high cost of performance-based cladding in large commercial and institutional structures. The non-residential market segment had a bigger revenue contribution than its market share of total building area due to the high volume of material used in large commercial and institutional structures.
The residential segment is the fastest growing market segment on the back of renovation-induced growth along with the building of new homes. The energy-efficiency incentive schemes offered to homeowners are further driving residential cladding installations, especially in countries with old housing stock.
By Installation Type, non-ventilated dominates, ventilated/rainscreen grows fastest
Non-ventilated cladding held the larger share of the installation-type segment in 2025, remaining the simpler, lower-cost installation method for projects that don't require the enhanced moisture management ventilated systems provide. Its lower upfront installation complexity keeps it the practical default for a meaningful share of residential and smaller commercial projects.
Ventilated, rainscreen cladding is growing fastest as building codes and energy-performance standards increasingly favor the air gap and moisture management this installation method provides. Better long-term durability and reduced risk of moisture-related structural damage are proving persuasive enough to building owners and code authorities that rainscreen specification is becoming close to standard on major commercial and institutional projects.
By Building Type, new construction dominates, renovation & retrofit grows fastest
New construction accounted for the largest share of the building-type segment in 2025, reflecting the scale of ongoing global construction activity across residential, commercial, and institutional sectors. Every new building represents a cladding specification decision, keeping new construction the largest single demand driver.
Renovation and retrofit work is growing fastest as aging building stock across developed markets faces increasing pressure to meet modern energy-efficiency and fire-safety standards without full reconstruction. Government-backed building energy-efficiency programs in multiple regions are directly reinforcing this shift, providing financial incentives that make cladding retrofits a more attractive investment for building owners than they were a decade ago.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Asia Pacific |
China |
42.0% |
|
North America |
United States |
84.0% |
|
Europe |
Germany |
24.0% |
|
Latin America |
Brazil |
37.0% |
|
Middle East & Africa |
Saudi Arabia |
30.0% |
North America Cladding Systems Market Insights
North America represents a substantial cladding systems market, with the United States accounting for the large majority of regional demand thanks to strict fire and building-performance codes alongside federal and state green-building initiatives. That regulatory environment supports strong demand for non-combustible and high-performance cladding across residential, commercial, and institutional construction.
Canada contributes additional demand through its own housing and commercial construction sectors, while the region's mature building stock makes renovation economics nearly as important a driver as new construction. Cross-border supply relationships tie much of North American demand together, with major manufacturers typically serving both markets through shared production networks.
Europe Cladding Systems Market Insights
Europe represents a mature, regulation-driven cladding systems market, shaped by energy-conservation standards including Germany's Energy Saving Ordinance and the Buildings Energy Act framework, which applies nearly zero-energy building standards to new construction. Germany anchors regional demand, home to a large construction sector and several major cladding manufacturers.
The United Kingdom, France, and the Netherlands contribute meaningful volume as well, each enforcing strict fire-safety cladding regulations following high-profile building fire incidents in recent years. That regulatory tightening has pushed the region decisively toward non-combustible and rigorously tested cladding materials.
Asia Pacific Cladding Systems Market Insights
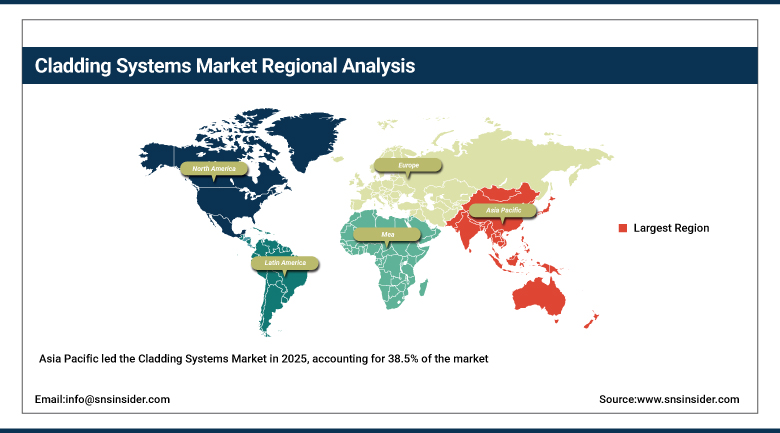
Asia Pacific led the Cladding Systems Market in 2025, accounting for 38.5% of the market, and is expected to register the fastest regional growth through 2035. China’s massive construction volume, combined with rapid urbanization and infrastructure development across the region, drives demand. Rising government investments in urban development, expanding commercial and residential construction, and increasing adoption of modern building materials further reinforce Asia Pacific’s leading position.
India's expanding construction sector is drawing significant new investment in modern cladding systems, while Japan and South Korea represent more mature, quality-focused markets with established cladding specification standards. Southeast Asian markets are following a similar urbanization-driven growth trajectory as regional construction activity continues expanding.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Cladding Systems Market Insights
The Middle East and Africa represent a smaller but rapidly developing cladding systems market, with Saudi Arabia driving demand through massive urban development and infrastructure investment tied to its broader economic diversification strategy. Growth elsewhere in the region remains tied closely to the pace of broader construction and urban development activity.
Latin America is a growing market led by Brazil, where expanding commercial and residential construction continues driving demand for modern cladding systems. Mexico and Colombia contribute meaningful secondary demand, tied to their own growing construction sectors and urbanization trends.
Market Dynamics
Growth Drivers: Urbanization and energy-efficiency regulation fueling adoption
Rapid urbanization and infrastructure development across emerging markets are one of the clearest forces behind rising cladding systems demand, as growing urban populations drive sustained new construction activity across residential, commercial, and institutional sectors. That demographic tailwind gives the cladding market a demand base that should keep expanding for years across the fastest-urbanizing regions.
Tightening energy-efficiency and building-performance regulation adds a second major driver, as governments across developed and emerging markets alike push building owners toward higher-performance envelope systems that reduce energy consumption. Cladding, as a building's primary weather and thermal barrier, sits directly at the center of these regulatory requirements.
Restraints: Fire-safety compliance costs and material price volatility limiting margin stability
Tightening fire-safety regulation, while ultimately improving building safety, has added real compliance cost and complexity for manufacturers and installers who must now navigate more rigorous testing and certification requirements than the industry faced a decade ago. That compliance burden falls disproportionately on smaller manufacturers without dedicated regulatory affairs capability.
Raw material price volatility, particularly for metals and specialty resins used in composite panels, adds a further layer of margin pressure for manufacturers and, ultimately, the building owners who buy from them. Manufacturers without long-term material supply contracts are particularly exposed to these swings, which can compress margins even when finished-product demand remains steady.
Opportunities: Building envelope retrofits and integrated solar cladding opening new growth avenues
Expanding building envelope retrofit activity offers manufacturers a genuine path to capturing steady, maintenance-driven demand independent of new construction cycles, as aging building stock across developed markets faces mounting pressure to meet modern energy and fire-safety standards. Manufacturers that build strong retrofit-focused product lines and installation partnerships are positioned to capture a growing share of this expanding category.
Integrated solar cladding and other active building envelope technologies represent a second significant opportunity, letting manufacturers offer systems that generate power and manage insulation simultaneously rather than treating each function as a separate building component. Companies that successfully commercialize this integrated approach are positioned to capture premium pricing from developers chasing both energy performance and aesthetic differentiation.
Recent Developments:
-
2025: Kingspan Group continued expanding its insulated metal panel manufacturing capacity across multiple regions, aimed at meeting rising demand for energy-efficient building envelope systems.
-
2025: Several major cladding manufacturers advanced fire-safety-focused non-combustible product lines, responding to tightening building codes following high-profile cladding fire incidents in multiple countries over the past decade.
-
2025: Composite panel manufacturers continued developing mono-material and more easily recyclable panel constructions, aimed at improving end-of-life recyclability without sacrificing the weather performance composite panels are known for.
-
2025: Rainscreen and ventilated cladding system specifications continued gaining share in commercial and institutional building codes across North America and Europe, driven by moisture management and energy performance requirements.
Cladding Systems Market Key Players
-
Kingspan Group
-
Saint-Gobain
-
Arconic Corporation
-
Etex Group
-
Tata Steel
-
James Hardie Industries
-
ROCKWOOL Group
-
Swisspearl Group
-
Nichiha Corporation
-
CSR Limited
-
Boral Limited
-
3A Composites / ALUCOBOND
-
Alucoil
-
FunderMax
-
Trespa International
-
Louisiana-Pacific Corporation (LP Building Solutions)
-
Alcoa Corporation
-
Hunter Douglas
-
Sika AG
-
Mitsubishi Chemical Group (ALPOLIC)
Cladding Systems Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 260.0 Billion |
| Market Size by 2035 | USD 430.0 Billion |
| CAGR | CAGR of 5.2% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material (Metal, Composite Panels, Glass, Fiber Cement, Brick & Stone, Wood, Vinyl, Stucco & EIFS, Others) • By Type (Walls, Roofs, Others) • By Application (Residential, Non-Residential) • By Installation Type (Ventilated/Rainscreen Cladding, Non-Ventilated Cladding) • By Building Type (New Construction, Renovation & Retrofit) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Kingspan Group, Saint-Gobain, Arconic Corporation, Etex Group, Tata Steel, James Hardie Industries, ROCKWOOL Group, Swisspearl Group, Nichiha Corporation, CSR Limited, Boral Limited, 3A Composites / ALUCOBOND, Alucoil, FunderMax, Trespa International, Louisiana-Pacific Corporation (LP Building Solutions), Alcoa Corporation, Hunter Douglas, Sika AG, Mitsubishi Chemical Group (ALPOLIC) |
Frequently Asked Questions
Key players include Kingspan Group, Saint-Gobain, Arconic Corporation, Etex Group, and Tata Steel, among others.
Key opportunities include building envelope retrofits, energy-efficient construction, fire-safe materials, integrated solar cladding, ventilated systems, and urbanization-driven construction.
Rapid urbanization and infrastructure development across emerging markets combined with tightening energy-efficiency and building-performance regulation worldwide.
Metal dominated with approximately 26.4% share in 2025, while Composite Panels is the fastest growing segment with a CAGR of approximately 6.9%.
Asia Pacific dominated the Cladding Systems Market in 2025 and is also the fastest-growing region.
