
Cognitive Supply Chain Market Report Scope & Overview:
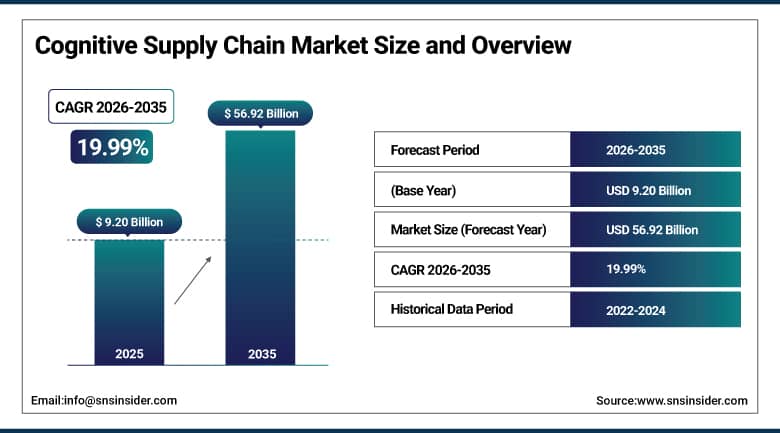
The Cognitive Supply Chain Market was valued at USD 9.20 Billion in 2025 and is expected to reach USD 56.92 Billion by 2035, growing at a CAGR of 19.99% from 2026-2035.
The Cognitive Supply Chain Market is growing as manufacturers, retailers and logistics companies adopt systems that learn from data, reason about trade-offs and recommend or execute decisions with limited human input. Cognitive platforms combine machine learning, natural language processing, sensor data and optimization engines to forecast demand, balance inventory, assess supplier risk and re-plan when disruptions occur. Tariff changes, geopolitical shocks and volatile freight markets have exposed the limits of static planning tools. Software vendors are now adding autonomous agents to planning, procurement and transportation workflows. Cloud delivery is making these tools available to mid-sized firms, and consulting firms are building practices around implementation. North America is the largest region, while Asia Pacific is expected to grow fastest.
⮞In October 2025, the World Trade Organization raised its estimate of 2025 world merchandise trade volume growth to 2.4% from 0.9% and lowered its 2026 forecast to 0.5% from 1.8%. The swings in trade conditions reinforce the case for planning systems that adapt quickly.
To Get More Information On Cognitive Supply Chain Market - Request Free Sample Report
Cognitive Supply Chain Market Trends
-
Autonomous artificial intelligence agents are being added to procurement, planning and logistics workflows.
-
Digital twins of networks are used to test scenarios before disruptions occur.
-
Vendors are consolidating planning, execution and visibility into unified platforms.
-
Companies are using generative artificial intelligence interfaces to query supply chain data in plain language.
-
Real-time visibility data from carriers and sensors is feeding predictive models.
U.S. Cognitive Supply Chain Market Outlook
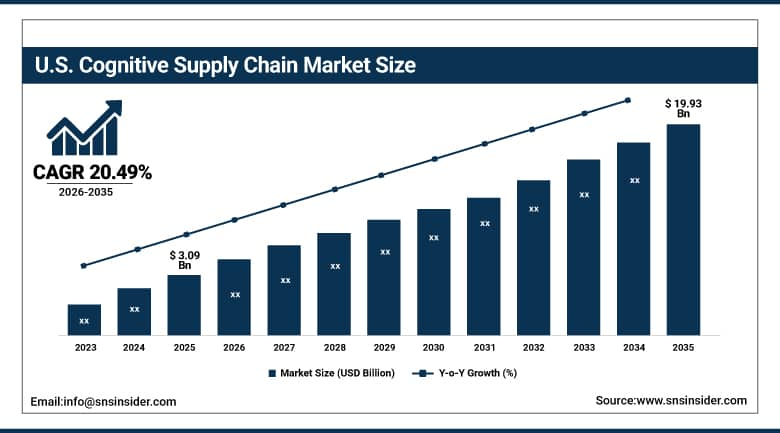
The U.S. Cognitive Supply Chain Market was valued at USD 3.09 Billion in 2025 and is expected to reach USD 19.93 Billion by 2035, growing at a CAGR of 20.49% from 2026-2035.
The U.S. Cognitive Supply Chain Market is the largest national market, supported by a concentration of software vendors, large retailers, manufacturers and logistics operators that invest heavily in planning and visibility technology. Companies face tariff changes, labor shortages and uneven freight conditions, and they use cognitive tools to forecast demand, rebalance inventory and choose among carriers and suppliers. Retail and e-commerce firms need fast fulfillment decisions across stores and warehouses, while manufacturers manage complex multi-tier supplier networks. Cloud platforms and generative artificial intelligence interfaces are lowering the skill needed to use advanced analytics. Growth is strong as spending shifts from experiments to production use, and large retailers and manufacturers are consolidating vendors into fewer platforms.
⮞In July 2026, the Port of Los Angeles handled 1,002,734 twenty-foot equivalent units in June, its busiest June in 118 years and up 12% from a year earlier. The volumes show the scale and volatility that U.S. importers must plan around, and the figures support steady investment in forecasting tools.
Cognitive Supply Chain Market Segment Analysis
-
By Component, the Software segment dominated the Cognitive Supply Chain Market with approximately 56.72% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 18.40%.
-
By Technology, the Artificial Intelligence and Machine Learning segment dominated the Cognitive Supply Chain Market with approximately 34.18% share in 2025, while the Digital Twin segment is the fastest growing with a CAGR of approximately 20.50%.
-
By Application, the Demand Forecasting segment dominated the Cognitive Supply Chain Market with approximately 29.74% share in 2025, while the Supplier Intelligence segment is the fastest growing with a CAGR of approximately 21.16%.
-
By Deployment, the On-Premise segment dominated the Cognitive Supply Chain Market with approximately 63.80% share in 2025, while the Cloud segment is the fastest growing with a CAGR of approximately 23.27%.
By Component, Software Dominates the Cognitive Supply Chain Market and Services Grows Fastest
Software holds the larger share because planning engines, optimization models, control towers and analytics applications are the core of every cognitive supply chain deployment. Enterprises license platforms for demand sensing, inventory optimization, transportation management and supplier risk, and they typically expand to additional modules once the first use case succeeds. Vendors add machine learning, natural language interfaces and autonomous agents to existing suites, which raises the value of each license. Recurring subscription models create predictable revenue and encourage customers to stay within a single vendor ecosystem.
Services are growing fastest because cognitive systems require data preparation, integration with legacy planning systems, model tuning and change management that few companies can handle alone. Consulting firms and system integrators help clients design target operating models, clean master data and train planners to trust machine recommendations. Managed services are increasingly used for ongoing model monitoring and exception handling. Demand for such support rises as firms move beyond pilots to enterprise deployments, and long-term service agreements provide a stable revenue stream for integrators and software vendors alike, with outcome-based pricing becoming more common.
⮞In August 2026, Kinaxis reported second-quarter total revenue of USD 158.80 million, up 16%, with software-as-a-service revenue of USD 106.50 million, up 20%. The company said about 10% of its installed base held a paid or trial subscription to its agent products.
By Technology, Artificial Intelligence and Machine Learning Dominates the Cognitive Supply Chain Market and Digital Twin Grows Fastest
Artificial intelligence and machine learning form the foundation of cognitive supply chains because they power forecasting, anomaly detection, route optimization and recommendation engines. Models learn from sales history, weather, promotions, supplier performance and transit times to improve accuracy over time. Vendors increasingly embed these capabilities directly in planning and execution software, so customers adopt them without building their own data science teams. Generative models add natural language interfaces that let planners query data and request scenarios in plain words, which broadens use beyond analysts and speeds up decisions in daily planning meetings.
Digital twins are growing fastest as companies build virtual replicas of their supply networks, warehouses and factories to test scenarios before committing resources. A twin can simulate the effect of a port closure, a supplier failure or a demand surge, and recommend alternative sourcing or routing. Combined with Internet of Things sensor feeds, twins give near real-time visibility into inventory and asset conditions. Robotic process automation and other technologies complement these tools by handling repetitive tasks such as order entry, invoice matching and shipment status updates, freeing planners for exceptions that need judgment.
⮞In April 2026, project44 said its platform captures more than one billion events per day and that its Freight Procurement Agent delivers 4.1% freight cost mitigation with a 75% shorter sourcing cycle. The figures illustrate the scale of data feeding autonomous logistics agents.
By Application, Demand Forecasting Dominates the Cognitive Supply Chain Market and Supplier Intelligence Grows Fastest
Demand forecasting is the largest application because every other planning decision depends on an accurate view of what customers will buy. Cognitive models combine point-of-sale data, promotions, pricing, weather, events and external signals to forecast at a granular level and update frequently. Better forecasts reduce stockouts, excess inventory and markdowns, which delivers measurable financial benefit. Retailers, consumer goods makers and manufacturers have all invested in demand sensing, and the use of machine learning has improved results compared with traditional statistical methods, particularly for new products and short-lived promotions that have little sales history.
Supplier intelligence is growing fastest as companies seek early warning of risks in multi-tier supply networks. Platforms monitor financial health, geopolitical exposure, sustainability performance, delivery history and news to flag problems before they disrupt production. Procurement teams use the insights to qualify alternative sources, negotiate contracts and meet new due diligence rules. Inventory management, logistics and transportation management applications also draw on cognitive tools, with algorithms selecting carriers, balancing stock across locations and responding to delays in real time, which reduces expedited freight and lost sales.
⮞In September 2025, the United Nations Conference on Trade and Development forecast that ton-miles in maritime trade would grow 5.9% in 2025 as vessels rerouted around the Cape of Good Hope, against volume growth of only 0.5%. The longer routes raise the value of planning tools that manage transit risk.
By Deployment, On-Premise Dominates the Cognitive Supply Chain Market and Cloud Grows Fastest
On-premise installations account for the larger share because many large manufacturers and enterprises run established planning and execution systems on their own infrastructure and are cautious about moving sensitive data. Regulated industries and companies with strict data residency rules prefer to keep control of core records, and years of customization make migration complex. Vendors continue to support these customers with upgrades that add machine learning features, and hybrid architectures allow selected analytics to run in the cloud while master data remains in house, which eases the path toward later migration.
Cloud deployment is growing fastest as vendors move their products to subscription platforms that update continuously and scale as data volumes rise. Mid-sized companies value the lower upfront cost, quick implementation and access to shared network data from carriers, suppliers and customers. Artificial intelligence features are released first in the cloud, which gives customers a reason to switch. Security certifications and regional hosting options have addressed many concerns, and cloud platforms make it easier to connect trading partners on a common data layer, reducing the time needed to onboard suppliers and carriers.
⮞In July 2026, Manhattan Associates reported second-quarter cloud subscription revenue of USD 126.70 million, up 26%, and remaining performance obligations of USD 2.47 billion, up 23%. The results show the pace of customer migration to cloud supply chain platforms.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.81% |
|
Europe |
Germany |
26.90% |
|
Asia Pacific |
China |
38.20% |
|
Latin America |
Brazil |
51.40% |
|
Middle East and Africa |
United Arab Emirates |
33.60% |
North America Cognitive Supply Chain Market Insights
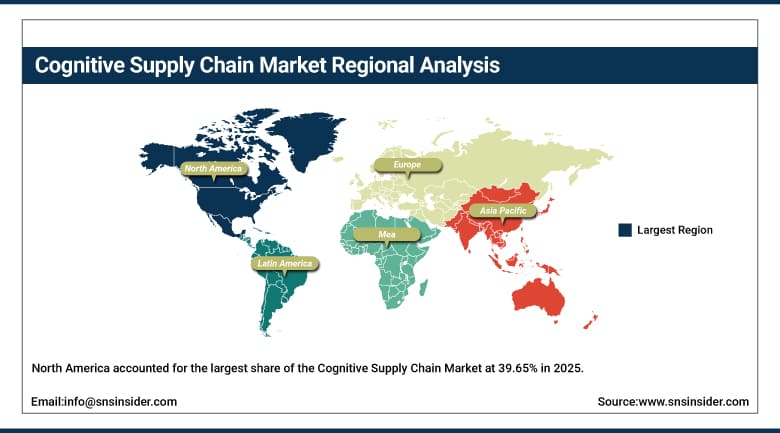
North America accounted for the largest share of the Cognitive Supply Chain Market at 39.65% in 2025, led by the United States, with Canada contributing through its manufacturing and resource sectors. The region is home to the main software vendors, hyperscale cloud providers and a large base of retailers, manufacturers and third-party logistics companies. Companies face tariff changes, labor constraints and demand volatility, and these pressures have led many to invest in planning systems that respond to change. Venture-backed start-ups add new agent-based tools, and large vendors respond through acquisitions and partnerships with cloud providers.
Vendor competition is very fierce, and consolidation is resulting in increased size in terms of a platform that incorporates planning, implementation, and visibility. More and more organizations are opting for solutions that link forecast with procurements and transport, and they test autonomous agents in very limited capacity initially before increasing their scope. Growth is robust, but legacy systems have substantial numbers installed, and thus any upgrades may take several years to be completed due to a well-defined budgeting process based on tangible results achieved from these applications.
⮞In October 2025, C.H. Robinson reported that shipments handled per person per day in its North American surface transportation segment were up 40% since the end of 2022, and that third-quarter operating income rose to USD 220.80 million from USD 180.10 million. The company attributed the gains to automation and artificial intelligence in pricing and operations.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Cognitive Supply Chain Market Insights
Europe is a large market with strong industrial and automotive sectors, leading software vendors and demanding regulation on sustainability and supply chain due diligence. Companies in Germany, France, the United Kingdom, the Netherlands and the Nordic countries use cognitive tools to manage complex cross-border networks, reduce emissions and meet reporting obligations. The region has a long history of enterprise planning software, and many manufacturers are upgrading to cloud platforms with embedded machine learning, supported by strong engineering talent and close ties between suppliers and automakers.
Supply chain legislation on human rights, forced labor and carbon reporting is increasing demand for supplier intelligence and traceability tools. Energy costs and disruption to shipping routes have also pushed firms to scenario planning. Data protection rules and concerns about technological sovereignty favor vendors offering regional hosting. Industrial policy supports automation, digital twins and smart manufacturing programs. Growth is steady, supported by compliance needs, though cautious corporate budgets, language differences across markets and fragmented systems can slow large rollouts, so vendors emphasize prebuilt connectors.
Asia Pacific Cognitive Supply Chain Market Insights
Asia Pacific is the fastest growing region, with a projected CAGR of 22.37% from 2026-2035, driven by its role as the center of global manufacturing, the rapid growth of e-commerce and large investment in logistics infrastructure. China, India, Japan, South Korea and Southeast Asian countries host dense supplier networks that benefit from better visibility and forecasting. Manufacturers are diversifying production across countries, which increases coordination complexity and creates demand for cognitive planning tools, particularly for coordinating sourcing across several countries.
Governments are supporting smart manufacturing, digital ports and national logistics platforms, and technology companies are building domestic supply chain software. E-commerce leaders operate sophisticated fulfillment networks and are pioneers in algorithmic inventory placement and delivery routing. Cloud adoption is accelerating, and small and medium suppliers are joining digital platforms to meet the requirements of global customers. Challenges include fragmented data standards, varying infrastructure and uneven technical skills, but the scale of activity supports the strongest growth among the major regions.
MEA and Latin America Cognitive Supply Chain Market Insights
Leadership in the Middle East and Africa Region comes from the United Arab Emirates, with logistics centers of Dubai being the gateway for doing trade in the region. Countries such as Saudi Arabia and Qatar have invested in logistics zones as well as in diversification of their industrial base. Digital initiatives for the supply chain are funded by the government. The uptake in the region has been on the increase, especially from big companies within the energy, logistics, and retail sectors, although most African nations have some challenges in terms of infrastructure and capability.
Latin America is led by Brazil, with Mexico, Chile, Colombia and Argentina also contributing, and Mexico is treated here as part of this region. Nearshoring has increased manufacturing activity in Mexico, which raises demand for planning and visibility tools, while Brazil's large domestic retail and agricultural sectors need route and inventory optimization over long distances. Currency volatility and infrastructure limits remain challenges, but cloud services and acquisitions by global vendors are expanding access to cognitive tools for regional companies, and large retailers are leading early adoption in forecasting and replenishment.
Growth Drivers: Supply Chain Disruption and Autonomous Agents Drive Growth in the Cognitive Supply Chain Market
Repeated disruptions from tariffs, shipping route changes, labor shortages and geopolitical conflict have shown that fixed plans quickly become obsolete. Companies want systems that sense changes early, evaluate options and recommend actions faster than manual planning allows. Cognitive tools improve forecast accuracy, reduce safety stock and shorten response times, and executives can link these gains directly to working capital and service levels. This measurable return has moved the technology from innovation budgets into core operating budgets, and boards now ask for clear plans to increase automation.
Autonomous agents add a new layer of demand. Vendors are launching agents that handle freight procurement, stockout response, slot booking and supplier communication, and they are connecting several agents into coordinated workflows. Generative interfaces reduce the effort needed to ask questions of supply chain data, which widens use across planners, buyers and managers. As early deployments show results, companies are increasing the scope of tasks they are willing to automate, which supports spending growth across the forecast period and encourages vendors to invest in safeguards and audit trails.
Restraints: Data Quality Gaps and Integration Costs Restrain Growth in the Cognitive Supply Chain Market
However, cognitive systems rely on good quality, reliable, and structured data, which is often available in disjointed systems within most businesses where there are discrepancies in the product database, supplier information, and location data. Cleansing and harmonization of the data is a time-consuming and costly process, and poor data quality reduces the reliability of any recommendations generated from the data. Connecting to legacy enterprise resource planning and warehouse systems increases the cost and risk associated with the project, which frequently results in projects exceeding budget estimates.
Trust and governance are further obstacles. Planners may be reluctant to follow machine recommendations they cannot explain, and executives worry about errors from autonomous actions in critical operations. Questions about data sharing with partners, cybersecurity and compliance with emerging artificial intelligence rules add complexity. High licensing and implementation costs, along with a shortage of skilled talent, slow adoption among mid-sized companies and in developing markets, which holds back the pace of market expansion and keeps many buyers in extended pilot phases.
Opportunities: Mid-Sized Company Adoption and Sustainability Analytics Create Opportunities in the Cognitive Supply Chain Market
Mid-sized companies represent a large untapped base. Cloud delivery, prebuilt industry models and managed services are lowering the cost and expertise needed to deploy cognitive tools, and vendors are packaging offerings for specific sectors such as food, healthcare and industrial distribution. Marketplaces and partner ecosystems help these companies connect with carriers, suppliers and customers on a shared data layer. Prebuilt industry models shorten deployment further. Vendors that simplify onboarding and demonstrate quick returns can win many new customers, particularly where local partners provide implementation support.
Sustainability and regulatory analytics provide another possibility. Reporting regulations on greenhouse gas emissions, supply chain due diligence, and traceability of products need data input from the suppliers. Cognitive analytics can assess footprint, identify risks, and suggest paths toward reduced carbon footprint. The investors and consumers seek information about responsibility in sourcing of their products, making data input not only a necessity but a business need. Platforms that combine cost efficiency, service, and sustainability objectives in an optimization solution will enable companies to achieve their goals without losing performance levels.
Recent Developments:
-
In July 2026, Descartes agreed to acquire Chile's Drivin, an artificial intelligence route optimization and dispatch company, for USD 30 million in cash plus up to USD 5 million in performance-based payments. The acquisition expands its reach into Latin America.
-
In July 2026, Freehand raised USD 75 million to deploy artificial intelligence agents that manage large-company supply chain spend, with Battery Ventures and NewRoad among the investors. The funding reflects investor interest in agent-based procurement.
-
In June 2026, Blue Yonder launched new retail, inventory and fulfillment artificial intelligence agents, including a fulfillment and sourcing agent in beta, and said it serves more than 3,000 customers. The release extends its platform with autonomous capabilities.
Cognitive Supply Chain Market Key Players
-
IBM
-
SAP
-
Oracle
-
Microsoft
-
Blue Yonder
-
o9 Solutions
-
Amazon Web Services
-
Honeywell
-
Siemens
-
project44
-
Manhattan Associates
-
Descartes Systems Group
-
Coupa Software
-
Infor
-
e2open
-
Google
Cognitive Supply Chain Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.20 Billion |
| Market Size by 2035 | USD 56.92 Billion |
| CAGR | CAGR of 19.99% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software and Services) • By Technology (Artificial Intelligence and Machine Learning, Internet of Things, Robotic Process Automation, Digital Twin, and Others) • By Application (Demand Forecasting, Inventory Management, Supplier Intelligence, Logistics and Transportation Management, and Others) • By Deployment (On-Premise and Cloud) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | IBM, SAP, Oracle, Microsoft, Blue Yonder, Kinaxis, o9 Solutions, Palantir Technologies, Amazon Web Services, Honeywell, Siemens, project44, Manhattan Associates, Descartes Systems Group, Coupa Software, Infor, e2open, Google |

Frequently Asked Questions
Key opportunities include cloud and managed offerings for mid-sized companies, supplier intelligence and sustainability analytics, and autonomous agents for procurement and logistics. Nearshoring and e-commerce growth in Asia Pacific and Latin America also widen the customer base.
The major growth factor is supply chain disruption from tariffs, shipping route changes and geopolitical shocks. Companies need systems that sense change early and recommend action faster than manual planning allows.
