
Construction Tapes Market Report Scope & Overview:
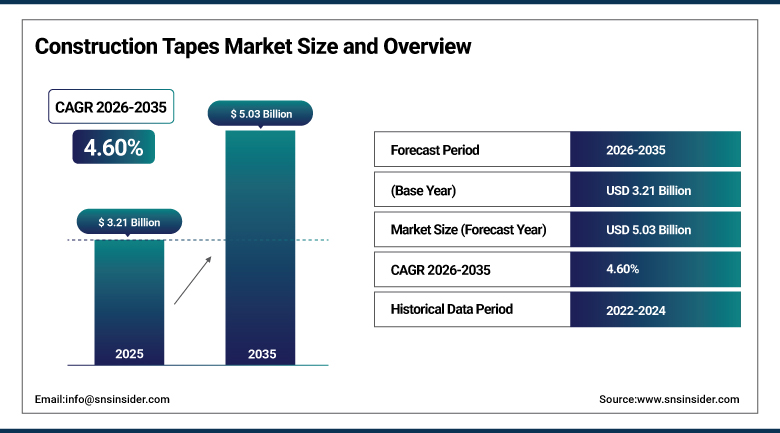
The Construction Tapes Market was valued at USD 3.21 Billion in 2025 and is expected to reach USD 5.03 Billion by 2035, growing at a CAGR of 4.60% from 2026-2035.
The Construction Tapes Market consists of tapes with adhesive properties which enable sealing, bonding, insulation, and protection of surfaces within construction operations; duct tapes for HVAC purposes, double-sided tapes for trim and window bonding, and specialty tapes for weather proofing, vapor barrier applications, and prefabricated constructions being typical examples. Growth in the market is based on continuous construction activities worldwide, increased awareness about the need for energy efficient sealing of the building envelope, and increasing adoption of prefabrication and modular construction practices which rely mainly on tape-based bonding and sealing as compared to conventional mechanical fastening. Innovations in terms of the advancement of backing materials and adhesives include replacement of traditional cloth and duct tape products with acrylic, polyurethane and butyl tapes that can seal windows, roofs, and concrete joints. Increased focus on sustainability-based product development has become a key aspect of competition in the industry.
In April 2025, Avery Dennison Performance Tapes introduced a new portfolio of pressure-sensitive adhesive tapes designed for building-envelope flashing and seaming applications, extending the company's construction tape offering beyond general-purpose bonding into specialized weatherproofing roles that command premium pricing.
To Get more information Construction Tapes Market - Request Free Sample Report
Construction Tapes Market Trends
-
Growing adoption of specialty tapes for weatherproofing, vapor barriers, and prefabricated modular construction methods.
-
Rising development of bio-based and recycled-content adhesive tapes in response to building material sustainability standards.
-
Expanding use of double-sided tapes for trim, window, and glass element bonding as a mechanical fastener alternative.
-
Continued advancement of acrylic, polyurethane, and butyl tape chemistries for higher-durability sealing applications.
-
Increasing manufacturer expansion into building-envelope-specific product lines such as flashing and seaming tapes.
U.S. Construction Tapes Market Outlook
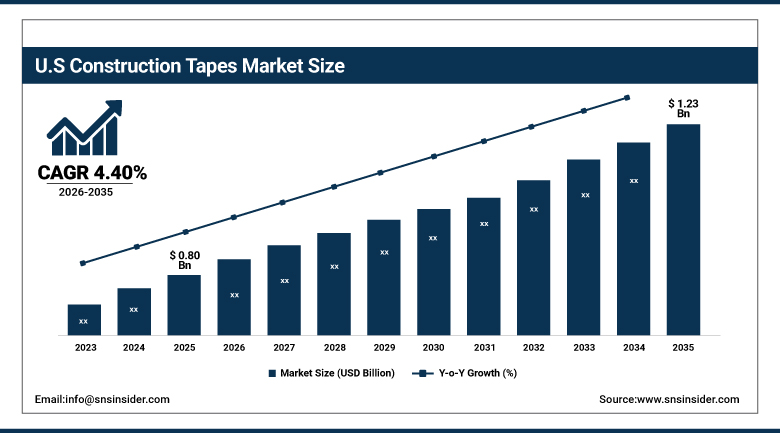
The U.S. Construction Tapes Market was valued at USD 0.80 Billion in 2025 and is expected to reach USD 1.23 Billion by 2035, growing at a CAGR of 4.40% from 2026-2035.
The United States continues to dominate the market for construction tapes with its active participation in non-residential and residential construction projects along with rising popularity of energy-efficient building envelope sealing systems linked to ever more restrictive energy codes in the construction industry. Leading domestic and international companies such as 3M, Avery Dennison and Intertape Polymer Group possess comprehensive distribution channels catering to both commercial construction contractors and residential construction contractors. Increasing use of prefabricated and modular construction techniques is driving up the demand for tapes that require less on-site manpower compared to mechanical fasteners.
In May 2023, Henkel opened its Technology Centre in Bridgewater, New Jersey, a 70,000-square-foot facility that showcases the company's full portfolio of adhesives, sealants, functional coatings, and specialty materials while providing a collaborative space for customers across more than 800 industry segments, including construction, to develop customized solutions.
Construction Tapes Market Segment Analysis
-
By Product Type, the Duct Tapes segment dominated the Construction Tapes Market with approximately 31.20% share in 2025, while the Double-Sided Tapes segment is the fastest growing with a CAGR of approximately 6.85%.
-
By Backing Material, the Cloth/Fabric segment dominated the Construction Tapes Market with approximately 34.50% share in 2025, while the Polyvinyl Chloride segment is the fastest growing with a CAGR of approximately 7.10%.
-
By Application, the Walls & Ceiling segment dominated the Construction Tapes Market with approximately 29.75% share in 2025, while the Flooring segment is the fastest growing with a CAGR of approximately 6.45%.
By Product Type, Duct Tapes dominate, and Double-Sided Tapes grow fastest
Duct tapes held the largest product-type share in 2025, reflecting their extensive and long-established use in HVAC installation and maintenance applications, where superior insulation and protective properties make them the default choice for sealing ductwork joints and connections across nearly every commercial and residential construction project.
Double-sided tapes are the fastest-growing product-type segment as they increasingly substitute for mechanical fasteners in bonding trims, window attachments, door panels, and glass elements, offering cleaner installation, reduced visible hardware, and compatibility with the lightweight materials increasingly favored in modern building design. Growing adoption in Europe and North America's window and curtain wall installation practices continues to reinforce this segment's above-average growth.
By Backing Material, Cloth/Fabric dominates, and Polyvinyl Chloride grows fastest
Cloth and fabric backing held the largest backing-material share in 2025, consistent with its long-established use in duct tape construction, where the reinforced fabric weave provides the tear resistance and flexibility required for HVAC sealing applications across a wide range of temperature and humidity conditions encountered on construction sites.
Polyvinyl chloride backing is the fastest-growing segment as its superior weather resistance, flexibility, and cost-effectiveness make it increasingly preferred for exterior sealing, vapor barrier, and flashing applications where sustained outdoor exposure demands greater durability than standard cloth-backed products can reliably provide. Continued advancement in PVC film formulations is further improving performance in low-temperature and UV-exposure conditions, broadening its addressable application range.
By Application, Walls & Ceiling dominates, and Flooring grows fastest
The walls & ceiling segment accounted for the highest market share in 2025 due to the large number of applications of drywall joint sealing, insulation, and vapor barriers, where tapes find an important use for the creation of airtight building envelopes demanded by stringent energy codes.
The flooring segment is expected to grow at the highest CAGR during the forecast period owing to the increasing usage of engineered flooring systems and modular subflooring that require special tapes for sealing the seams, moisture barrier installation, and bonding underlays. The demand for prefabricated floor systems in commercial and residential construction is driving the above-average growth of the segment.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
76.85 |
|
Europe |
Germany |
29.60 |
|
Asia Pacific |
China |
41.75 |
|
Middle East & Africa |
United Arab Emirates |
35.20 |
|
Latin America |
Brazil |
46.90 |
North America Construction Tapes Market Insights
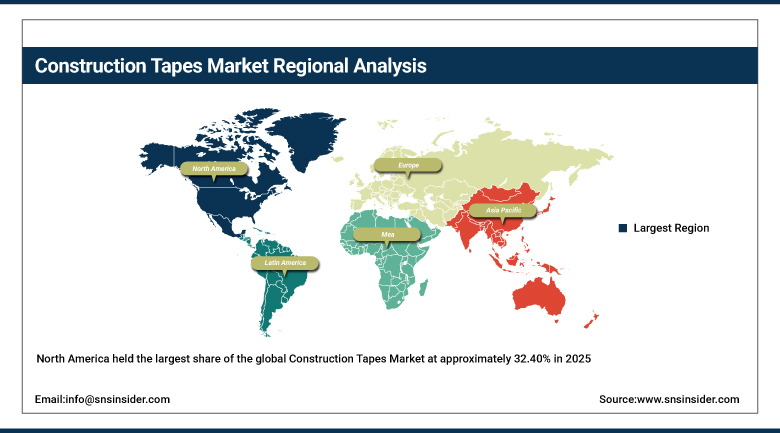
North America held the largest share of the global Construction Tapes Market at approximately 32.40% in 2025, driven by robust commercial and residential construction activity across the United States and Canada, alongside growing adoption of energy-efficient building envelope sealing practices tied to increasingly stringent building energy codes. The United States accounted for the substantial majority of regional demand, supported by extensive distribution networks operated by 3M, Avery Dennison, and Intertape Polymer Group.
Continued growth in prefabricated and modular construction methods, which rely heavily on tape-based bonding and sealing rather than traditional mechanical fasteners, is reinforcing regional demand. Canada contributes additional regional demand through its own construction sector, particularly in cold-climate building envelope sealing applications where tape performance under temperature extremes is a critical specification factor.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Construction Tapes Market Insights
Asia-Pacific is the most rapidly growing region in the Construction Tapes Market, expected to grow at a CAGR of around 6.60% during the forecast period from 2026 to 2035 on account of fast urbanization along with huge numbers of construction activities in countries like China, India, and Southeast Asia. The high base of domestic construction tapes production in China caters to the massive demand in the country, along with increased exports to other developing countries.
The rapidly growing construction industry in India, backed by infrastructure and housing projects by the government, has created huge incremental demand for construction tapes in HVAC, flooring, and wall sealing applications. Urbanization and construction activities in Southeast Asian nations are expected to continue the growth momentum of the region during the forecast period.
Europe Construction Tapes Market Insights
Europe represents a mature construction tapes market, shaped by stringent building energy efficiency directives that mandate airtight building envelope construction, driving sustained demand for sealing and vapor barrier tapes across renovation and new construction projects alike. Germany leads regional demand, supported by a well-established adhesive tape manufacturing base including Tesa SE and Henkel.
France, Italy, and the United Kingdom contribute significant additional regional demand through their own building energy renovation programs, while continued EU sustainability regulation is driving manufacturer investment in eco-friendly, low-VOC tape formulations across the region. Tesa's continued expansion of its European production facility to increase eco-friendly industrial tape capacity reflects this broader regional shift toward sustainability-compliant construction materials.
MEA & Latin America Construction Tapes Market Insights
The construction tapes market in Middle East & Africa is on the rise due to the Gulf Cooperation Council countries undertaking large-scale construction megaprojects within their economies as a way of diversifying their economies, and the main driver of the market in the region is the UAE, owing to the construction projects that exist in the region.
Latin America is dominated by Brazil, where there is consistent residential and commercial construction taking place in the region resulting in the need for both general purpose and specialty construction tapes, with the capacity of producing the adhesives growing within the region. Mexico is contributing to the demand through its own construction industry.
Market Dynamics
Growth Drivers: Energy-Efficient Building Envelope Construction
Increasingly stringent building energy codes across North America, Europe, and parts of Asia are driving sustained demand for construction tapes used in achieving airtight building envelopes, as vapor barrier, flashing, and seaming tapes have become essential components of energy-efficient wall, roof, and window assembly systems rather than optional sealing accessories. Building certification programs rewarding energy performance are reinforcing specification of higher-performance sealing tapes across new construction.
The parallel growth of prefabricated and modular construction methods is compounding this driver, as off-site construction techniques increasingly rely on tape-based bonding and sealing to join prefabricated wall, floor, and roof panels rather than traditional mechanical fastening methods that can compromise the pre-installed insulation and vapor barrier systems within prefabricated components. This structural shift toward off-site construction is expanding the addressable application base for specialty construction tapes beyond their traditional general-purpose sealing role.
Restraints: Raw Material Price Volatility and Substitute Sealing Methods
Manufacturers’ costs in adhesive tape production are still vulnerable to price fluctuations of petrochemical feedstocks used not only in backings but also in adhesives, thus resulting in the manufacturers’ margin vulnerability to periods of raw material prices that do not allow for immediate increase in the selling price of the finished product to construction contractors due to supply agreements.
Competing with alternative sealant technologies such as spray foam insulation, caulking, and mechanical fasteners poses challenges for tape use in some applications where contractors already have the processes set up for other sealing techniques. Overcoming the threat of substitution usually implies proving labor and time savings compared to alternative sealing options.
Opportunities: Sustainable Tape Formulations and Building Envelope Specialization
Growing demand for bio-based and recycled-content adhesive tapes presents a significant opportunity for manufacturers to differentiate on sustainability credentials while meeting tightening building material environmental standards, particularly in Europe where regulatory pressure on construction material environmental impact continues to intensify. Manufacturers successfully commercializing high-performance sustainable tape formulations are positioned to capture premium pricing from environmentally focused contractors and building certification programs.
Continued expansion into specialized building-envelope product lines, such as flashing, seaming, and window installation tapes, presents a further opportunity for manufacturers to move beyond commodity duct and masking tape products into higher-margin, performance-differentiated categories. Manufacturers that successfully establish specification relationships with architects and building envelope consultants are positioned to capture recurring demand as these specialized tape categories become standard components of modern building envelope design.
Recent Developments:
-
2025- Tesa SE established new offices in Mumbai and Bengaluru, India, to strengthen its presence and construction and industrial tape distribution across the Asia-Pacific region.
-
2024- Tesa SE expanded its European production facility to increase capacity for eco-friendly industrial and construction tapes in response to EU sustainability regulations.
-
May 2023- Nitto Denko Corporation rolled out PlanetFlags, a bio-based double-sided adhesive tape manufactured from recycled films.
Construction Tapes Market Key Players
-
3M Company
-
Henkel AG & Co. KGaA
-
Avery Dennison Corporation
-
Tesa SE
-
Sika AG
-
Nitto Denko Corporation
-
Intertape Polymer Group Inc.
-
Shurtape Technologies, LLC
-
The Dow Chemical Company
-
Saint-Gobain Performance Plastics
-
Canadian Technical Tape Limited
-
Berry Global, Inc.
-
Ahlstrom Corporation
-
H.B. Fuller Company
-
LINTEC Corporation
-
Scapa Group plc
-
DuPont de Nemours, Inc.
-
Lohmann GmbH & Co. KG
-
Mactac
-
Pro Tapes & Specialties, Inc.
Construction Tapes Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.21 Billion |
| Market Size by 2035 | USD 5.03 Billion |
| CAGR | CAGR of 4.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Duct Tapes, Double-Sided Tapes, Masking Tapes, and Others) • by Backing Material (Cloth/Fabric, Polyvinyl Chloride, Foil, and Others) • by Application (Walls & Ceiling, Flooring, HVAC, and Roofing) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | 3M Company, Henkel AG & Co. KGaA, Avery Dennison Corporation, Tesa SE, Sika AG, Nitto Denko Corporation, Intertape Polymer Group Inc., Shurtape Technologies, LLC, The Dow Chemical Company, Saint-Gobain Performance Plastics, Canadian Technical Tape Limited, Berry Global, Inc., Ahlstrom Corporation, H.B. Fuller Company, LINTEC Corporation, Scapa Group plc, DuPont de Nemours, Inc., Lohmann GmbH & Co. KG, Mactac, Pro Tapes & Specialties, Inc. |
Frequently Asked Questions
North America dominated the Construction Tapes Market with approximately 32.40% share in 2025, supported by robust construction activity and growing building envelope sealing adoption.
Key players in the Construction Tapes Market include 3M Company, Henkel AG & Co. KGaA, Avery Dennison Corporation, Tesa SE, and Sika AG, among others.
Key opportunities lie in developing bio-based and recycled-content tape formulations for sustainability-focused construction, and in expanding into specialized building-envelope product lines such as flashing and seaming tapes.
Increasingly stringent building energy codes requiring airtight building envelopes, combined with growing adoption of prefabricated and modular construction methods, are the major growth factors.
By Product Type, the Duct Tapes segment dominated the Construction Tapes Market with approximately 31.20% share in 2025.
