
Defense Cybersecurity Market Report Scope & Overview:
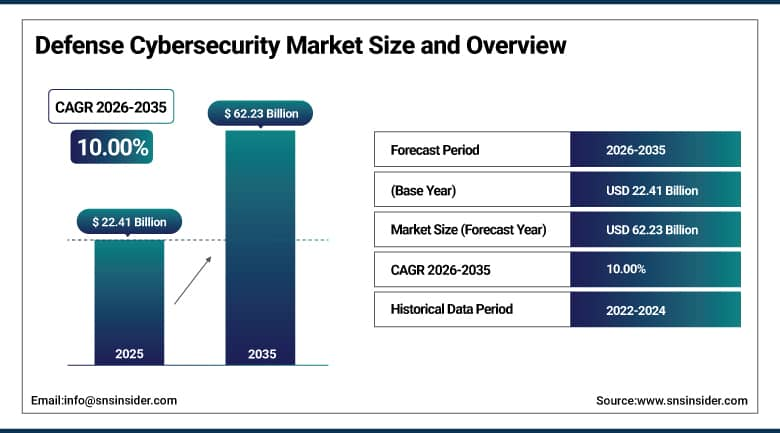
The Defense Cybersecurity Market was valued at USD 22.41 Billion in 2025 and is expected to reach USD 62.23 Billion by 2035, growing at a CAGR of 10.00% from 2026 to 2035.
Defense cybersecurity market is expanding at a tremendous rate due to increased cyber attacks in the defense industry and digital transformation and automation among defense firms worldwide. Defense cybersecurity involves technology that monitors, detects, alerts, and mitigates cyber attacks that affect defense organizations’ network, command & control, intelligence, tactical communications, and defense industrial base suppliers to provide operational assurance, continuity, and confidentiality of classified information. In addition to this, the expansion of the market is fueled by the increased use of cloud computing, C4ISR, connected weapons, and zero trust security systems that demand increased monitoring and encryption, greater investment by governments in cybersecurity platforms providing central visibility, and advanced nation-state sponsored cyber threats on national security infrastructure.
The defense cybersecurity sector is increasingly pivoting toward never-trust, always-verify zero-trust architectures across national security systems, reflecting a fundamental shift in how military organizations approach network security as interconnected information systems, cloud services, and software-defined capabilities expand the cyber risk profile at every layer of defense operations.
To Get More Information On Defense Cybersecurity Market - Request Free Sample Report
Defense Cybersecurity Market Trends
-
Rising adoption of zero-trust security architectures is reshaping defense network protection strategies, as military organizations shift away from perimeter-based security toward continuous verification models.
-
Growing integration of cloud computing, C4ISR systems, and connected weapons platforms is expanding the attack surface requiring stronger monitoring, encryption, and cyber testing across defense infrastructure.
-
Increasing demand for AI-driven threat detection and automated response capabilities is enabling defense organizations to identify and neutralize sophisticated cyber threats more rapidly than manual approaches allow.
-
Expanding cooperation between NATO and European defense organizations is driving coordinated investment in military cyber defense, secure cloud adoption, and cyber command development across allied nations.
-
Strategic partnerships among defense contractors, cybersecurity technology providers, and government agencies are supporting development of increasingly integrated, mission-critical cyber defense platforms.
U.S. Defense Cybersecurity Market Outlook
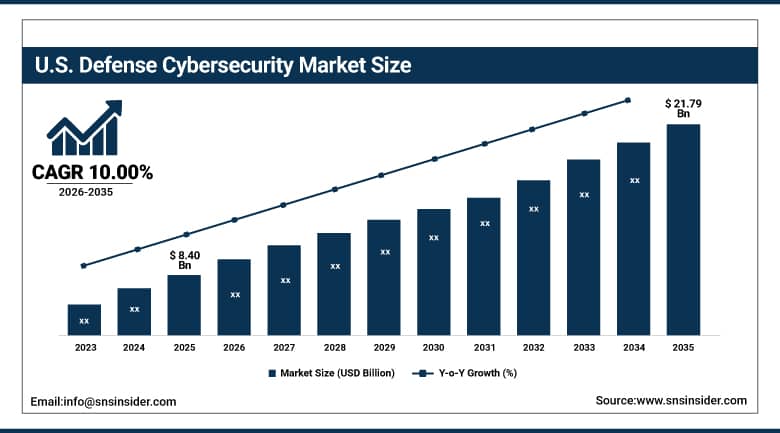
The U.S. defense cybersecurity market was valued at USD 8.40 Billion in 2025 and is projected to reach USD 21.79 Billion by 2035, growing at a CAGR of 10.00% during 2026–2035.
The top security defense organizations and contractors of the nation continue to increase their cybersecurity spending owing to the massive investments made by the government and the Pentagon in cloud security for defense and the fast adoption of automation in detecting cyber threats. The continuous modernization of the military cybersecurity network infrastructure together with the increasing sophistication of nation-state-backed cyber threats to defense industrial base suppliers increases the domestic demand for defense cybersecurity solutions.
The United States captures the leading position within North America's market, driven by large-scale government and Pentagon investments in cloud-based defense cybersecurity and rapid adoption of automation for cyber threat detection across military network protection infrastructure.
Defense Cybersecurity Market Segment Analysis
-
By Component, solutions dominated the market with a 68.20% share in 2025, while services is the fastest-growing component segment with a CAGR of 12.73% from 2026–2035.
-
By Security Type, network security dominated the market with a 42.60% share in 2025, while identity & access management is the fastest-growing security type segment with a CAGR of 11.49% from 2026–2035.
-
By Deployment Mode, on-premises dominated the market with a 54.60% share in 2025, while cloud is the fastest-growing deployment mode segment with a CAGR of 12.90% from 2026–2035.
-
By End User, armed forces dominated the market with a 58.00% share in 2025, while defense contractors is the fastest-growing end user segment with a CAGR of 11.65% from 2026–2035.
By Component, solutions dominated the defense cybersecurity market, while services is the fastest-growing segment.
Solutions formed the major part of the market, accounting for 68.20% market share in terms of revenue in 2025. Solutions continue to form the majority of the component types because of the rising adoption of network security, endpoint security, identity and access management, encryption, and security analytics solutions by defense organizations as governments keep on investing in advanced cybersecurity platforms.
The services segment is projected to register the fastest CAGR of 12.73% during the forecast period 2026-2035, due to rising demand for integration, consulting, and managed security services. Growing demand for cybersecurity consulting, system integration, security assessments, and managed detection and response services is driving rapid segment growth, as defense organizations increasingly seek specialized expertise to configure and maintain increasingly sophisticated cyber defense platforms.
By Security Type, Network Security Dominated The Defense Cybersecurity Market, While Identity & Access Management Is the fastest-growing segment.
The network security segment dominated the market with a revenue share of 42.60% in 2025. Network security remains the dominant category owing to its foundational role protecting military communication infrastructure, command systems, and classified networks from unauthorized access and intrusion, representing the essential first line of defense across virtually every defense cybersecurity deployment worldwide.
The identity and access management segment is forecasted to witness the highest CAGR of 11.49% through the period of 2026-2035. The growing adoption of the zero trust concept is driving the demand for sophisticated identity verification and access control mechanisms due to the emphasis on continuous authentication and least privilege access models by the defense organizations.
By Deployment Mode, on-premises dominated the defense cybersecurity market, while cloud is the fastest-growing segment.
The on-premises segment dominated the market with a revenue share of 54.60% in 2025. On-premises deployment remains the dominant category owing to classified network security requirements and data sovereignty considerations that continue to favor locally controlled infrastructure across the majority of sensitive military and intelligence system deployments worldwide.
The cloud segment is expected to witness the fastest CAGR of 12.90% during the forecast period 2026-2035. Wider use of cloud computing and secure cloud adoption across defense organizations is driving rapid segment growth, as military agencies increasingly migrate select workloads to government-accredited cloud environments offering improved scalability and centralized security management capability.
By End User, armed forces dominated the defense cybersecurity market, while defense contractors is the fastest-growing segment.
The armed forces section has been leading the market in terms of revenue share with 58.00%. Armed forces continue to dominate as the main end users due to their heavy dependence on secure networking, command and control systems, intelligence systems, cloud infrastructure, and critical information. Military branches, therefore, become the key procurers of defense cybersecurity solutions.
The defense contractors segment is projected to witness the fastest CAGR of 11.65% during the forecast period 2026-2035. Growing recognition that defense industrial base suppliers represent a critical and increasingly targeted attack vector is driving rising cybersecurity investment among contractors, as government procurement requirements increasingly mandate stringent cybersecurity compliance standards for companies handling classified or sensitive defense information.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
Japan |
36.80% |
|
Middle East & Africa |
UAE |
26.80% |
|
Latin America |
Brazil |
37.70% |
North America Defense Cybersecurity Market Insights
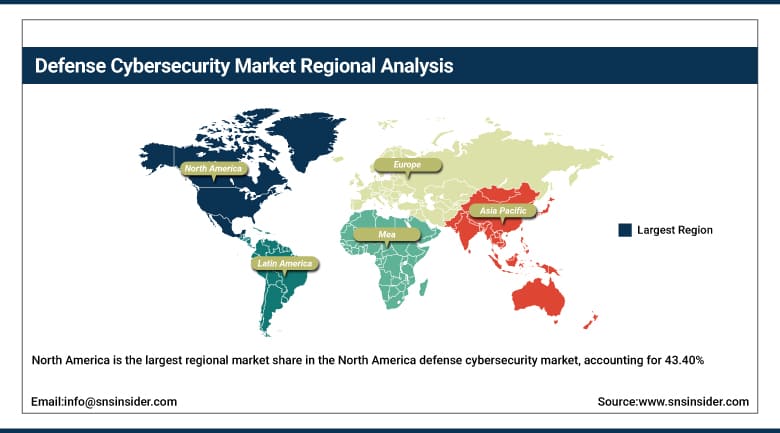
North America is the largest regional market share in the North America defense cybersecurity market, accounting for 43.40% of the market due to major companies like Booz Allen Hamilton, Cisco Systems, and Raytheon investing heavily in cybersecurity technologies for military purposes in their defense industries.
United States emerged as the largest country in the North America defense cybersecurity market in 2025 because of significant investments made by the government and Pentagon in cloud-based defense cybersecurity and military network protection infrastructure. Canada is contributing to regional growth through its own expanding defense technology investment and growing NATO-aligned cybersecurity cooperation.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Defense Cybersecurity Market Insights
The Europe defense cybersecurity market is expected to have a substantial market share during the forecast period due to rising investments in military cyber defense, secure cloud adoption, cyber command development, and enhanced cooperation between NATO and European defense organizations across member states.
Germany is one of the major markets in Europe owing to its strong defense industrial base and growing investment in military cyber command capabilities. Other countries such as the United Kingdom and France are also contributing to market growth through expanding NATO-aligned cyber defense cooperation and national cybersecurity modernization programs.
Asia Pacific Defense Cybersecurity Market Insights
Asia-Pacific is expanding at a fast CAGR of 11.4% as Japan, South Korea, and India enhance cyber doctrine, invest in sovereign clouds, and integrate satellite-based networks, driving the region's rapid emergence as a fast-growing defense cybersecurity market.
Japan is one of the main growth drivers in the Asia Pacific defense cybersecurity market, owing to its expanding cyber doctrine investment and growing sovereign cloud infrastructure development. South Korea and India are also contributing to regional growth through rising defense modernization investment and increasing integration of satellite-based network security capabilities.
Middle East & Africa and Latin America Defense Cybersecurity Market Insights
Middle East & Africa and Latin American regions are gradually expanding defense cybersecurity adoption as military modernization investment grows across both regions, supported by increasing regional government focus on national security infrastructure protection.
Brazil is set to be a prominent Latin American market fueled by growing domestic defense modernization investment. The Middle East & Africa region has UAE and Saudi Arabia investing heavily in advanced defense cybersecurity infrastructure as part of broader national security and military modernization strategies supporting the region's expanding defense procurement programs.
Market Dynamics
Growth Drivers: Rising cyberattack sophistication and defense digitalization driving market growth
The increased cases of cyberattacks in the defense industry and digitalization and automation within defense organizations around the world are just some of the main factors behind the growth in the Defense Cybersecurity Market. Defense platforms, command and control systems, logistics networks, and defense industrial base vendors are becoming increasingly reliant on information technology and software defined systems, increasing the cybersecurity risks at all levels of defense operations around the world.
Wider use of cloud, C4ISR, connected weapons, and zero-trust programs, which require stronger security, monitoring, encryption, and cyber testing, continues to drive sustained investment across defense organizations. Growing government investment in integrated cybersecurity platforms delivering centralized visibility and automated threat detection, increasing sophistication of nation-state-sponsored cyber threats, and expanding NATO and allied cooperation on cyber defense standards are further supporting demand across the forecast period.
Restraints: High implementation costs and legacy system integration challenges limiting market expansion
One of the challenges for the market is the considerable expense involved in putting in place cyber security architecture aligned with the zero trust model in existing defense systems that did not have such considerations at the time of their initial design.
Moreover, the integration of new cybersecurity technologies with the classified systems as well as weapons is subject to numerous security clearance procedures that may prolong the implementation process. The ongoing lack of properly trained personnel who can meet all requirements relating to cybersecurity and have proper security clearance hampers the ability of defense departments to implement advanced cyberdefense projects.
Opportunities: Expansion of zero-trust architecture and AI-driven threat detection creating new growth avenues
Rising tech adoption spurs need for advanced cyber defense, creating substantial opportunities for cybersecurity companies capable of delivering integrated, AI-enhanced threat detection and response platforms tailored to the unique requirements of classified military and defense industrial base networks.
There is a considerable growth opportunity in the continued expansion of managed security services helping defense organizations address persistent cybersecurity workforce shortages. The expansion of NATO-aligned cyber defense cooperation and military modernization investment in emerging markets across Asia Pacific and the Middle East is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
-
2025: Booz Allen Hamilton expanded its AI-driven cyber threat detection platform for defense customers, offering enhanced automated analysis capabilities for identifying sophisticated nation-state cyber threats.
-
2025: Palo Alto Networks launched an updated zero-trust security architecture designed for defense networks, providing continuous verification capabilities aligned with evolving Department of Defense cybersecurity mandates.
-
2026: Leidos expanded its cloud-based cybersecurity services for Department of Defense customers, strengthening its ability to support government-accredited cloud migration and security management initiatives.
-
2026: Northrop Grumman launched an updated cyber resilience platform focused on weapon systems protection, addressing growing concerns around cybersecurity vulnerabilities in increasingly software-defined military platforms.
Defense Cybersecurity Market Key Players are:
-
Lockheed Martin Corporation
-
Northrop Grumman Corporation
-
RTX Corporation (Raytheon Technologies)
-
BAE Systems plc
-
Thales Group
-
General Dynamics Corporation
-
Booz Allen Hamilton Inc.
-
Leidos Holdings, Inc.
-
CACI International Inc.
-
Science Applications International Corporation (SAIC)
-
L3Harris Technologies, Inc.
-
Cisco Systems, Inc.
-
IBM Corporation
-
Palo Alto Networks, Inc.
-
Elbit Systems Ltd.
-
Airbus Defence and Space
-
ManTech International Corporation
-
Peraton Inc.
-
Parsons Corporation
-
Fortinet, Inc.
Defense Cybersecurity Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 22.41 Billion |
| Market Size by 2035 | USD 62.23 Billion |
| CAGR | CAGR of 10.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Solutions, Services) • By Security Type (Network Security, Endpoint Security, Identity & Access Management, Cloud Security) • By Deployment Mode (On-Premises, Cloud, Hybrid) • By End User (Armed Forces, Defense Contractors, Government Agencies) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Lockheed Martin Corporation, Northrop Grumman Corporation, RTX Corporation (Raytheon Technologies), BAE Systems plc, Thales Group, General Dynamics Corporation, Booz Allen Hamilton Inc., Leidos Holdings, Inc., CACI International Inc., Science Applications International Corporation (SAIC), L3Harris Technologies, Inc., Cisco Systems, Inc., IBM Corporation, Palo Alto Networks, Inc., Elbit Systems Ltd., Airbus Defence and Space, ManTech International Corporation, Peraton Inc., Parsons Corporation, Fortinet, Inc. |
Frequently Asked Questions
The Defense Cybersecurity Market is expected to grow at a CAGR of 10.00% from 2026 to 2035.
The Defense Cybersecurity Market was valued at USD 22.41 Billion in 2025.
The market is driven by rising prevalence of cyberattacks in the defense sector and accelerating digital transformation and automation across global defense organizations.
The Solutions segment dominated the Defense Cybersecurity Market in 2025, accounting for approximately 68.20% market share.
