
Digital Avatar Market Report Scope & Overview:
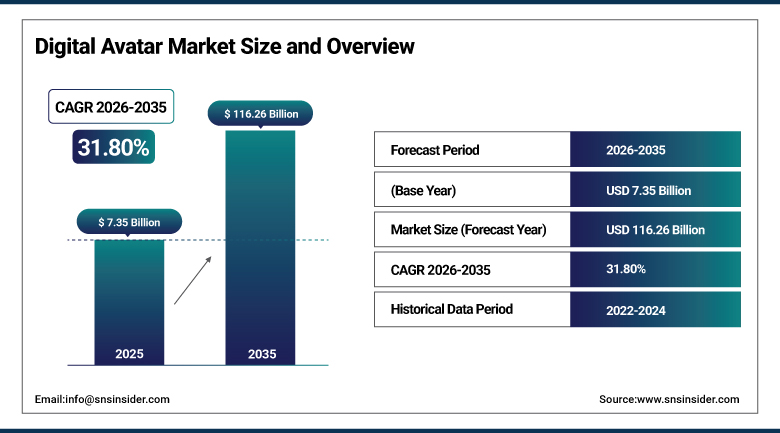
The Digital Avatar Market was valued at USD 7.35 Billion in 2025 and is expected to reach USD 116.26 Billion by 2035, growing at a CAGR of 31.80% from 2026-2035.
The Digital Avatar Market covers software, platforms and services that create digital representations of people, characters and brands, from realistic AI-generated presenters and conversational agents to stylized game characters and virtual influencers. Avatars are used for customer service, training, marketing video, entertainment, education and social platforms. Growth is supported by generative AI, real-time rendering, falling cost of video production and enterprise demand for scalable content, while deepfake risk, consent and likeness rights, and compute cost shape adoption.
⮞Real-time conversational avatars are reaching enterprise scale. On March 16, 2026, D-ID launched V4 Expressive Visual Agents, a new generation of digital humans for real-time conversations connected to large language models. The company said conversational turns run under 0.50 seconds with output up to 4K resolution, and that the product is available to 1,500 enterprise customers and subscribers on all plans.
To Get more information Digital Avatar Market - Request Free Sample Report
Digital Avatar Market Trends
- Shift from scripted presenter videos to real-time avatars linked to large language models
- Creation of realistic digital twins from short recordings of a real person
- Use of avatars in customer service, onboarding and employee training
- Growth of virtual influencers, virtual companions and branded characters
- Rising attention to consent, watermarking and likeness rights for synthetic humans
- Government use of avatars as public-facing spokespersons and service guides
U.S. Digital Avatar Market Outlook
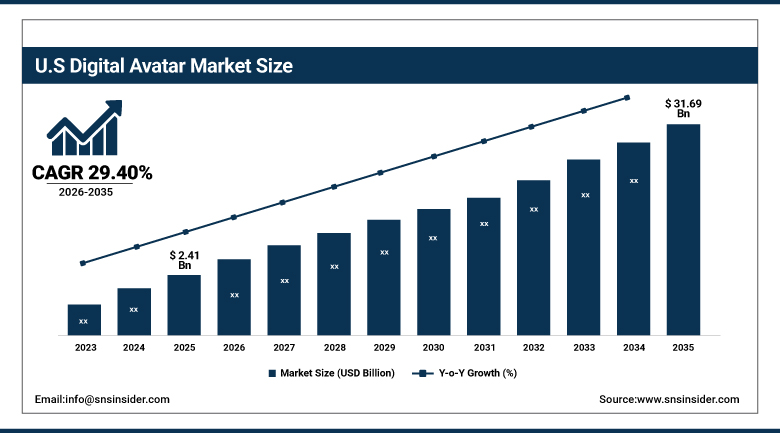
The U.S. Digital Avatar Market was valued at USD 2.41 Billion in 2025 and is expected to reach USD 31.69 Billion by 2035, growing at a CAGR of 29.40% from 2026-2035.
The U.S. Digital Avatar Market is the largest national market, supported by leading platform and chip companies, large venture funding for generative AI video, and early enterprise adoption in marketing, training and customer service. Gaming, media, retail and financial services deploy avatars to produce content faster and serve customers around the clock. Growth is moderated by evolving state rules on synthetic media, concern over deepfakes and the cost of real-time generation at scale.
⮞Avatar creation is becoming faster and cheaper. In its April 2026 release roundup, HeyGen described Avatar V, a model that builds a digital twin from a single 15-second recording, with upper-body movement, multi-look generation and consistency across camera angles. The company said the model keeps face, voice and presence stable in longer videos, which matters for training and marketing content.
Digital Avatar Market Segment Analysis
- By Type, interactive avatars segment dominated the Digital Avatar Market in 2025 with an estimated 60.00% share; non-interactive avatars segment is the fastest-growing segment, with an estimated CAGR of 33.50% during 2026–2035.
- By Technology, AI and machine learning segment dominated the Digital Avatar Market in 2025 with an estimated 41.00% share; computer vision segment is the fastest-growing segment, with an estimated CAGR of 34.50% during 2026–2035.
- By Application, virtual agents and assistants segment dominated the Digital Avatar Market in 2025 with an estimated 40.00% share; virtual companions and others segment is the fastest-growing segment, with an estimated CAGR of 36.00% during 2026–2035.
- By End Use, enterprise segment dominated the Digital Avatar Market in 2025 with an estimated 57.00% share; consumer segment is the fastest-growing segment, with an estimated CAGR of 33.80% during 2026–2035.
By Type, Interactive Avatars Dominates Digital Avatar Market; Non-Interactive Avatars to Register Fastest Growth.
Interactive avatars dominate the Digital Avatar Market because businesses use them for customer service, sales assistance, tutoring and onboarding, where a conversational presence replaces forms and call center scripts. They connect to language models and company knowledge bases, answer questions in many languages and run around the clock. Enterprises pay recurring fees per seat or per minute, which gives vendors larger contract values than one-time video generation and supports high revenue share. Integration with customer relationship systems and call center tools also makes these products sticky once deployed.
Non-interactive avatars are projected to register the fastest growth because marketing, training and communications teams produce large volumes of presenter videos that previously needed studios, actors and editing. Platforms now generate videos in dozens of languages from a script within minutes, and costs per video are falling. Short-form social video, product explainers and internal updates add volume, and new models that create a digital twin from a brief recording widen use among small businesses and individual creators. Templates, stock presenters and brand style controls also help companies keep a consistent look across large video libraries.
By Technology, AI and Machine Learning Dominates Digital Avatar Market; Computer Vision to Register Fastest Growth.
AI and machine learning dominate the Digital Avatar Market because generative models for faces, voices, gestures and dialogue form the core of nearly every avatar product. Diffusion and transformer models drive realism, while language models supply conversation. Platform companies spend heavily on training data and cloud compute, and licensing of models or application programming interfaces creates steady revenue for vendors that supply the base technology to developers and brands. Open model releases and cloud credits also let smaller developers build on the same technology, widening the supplier base.
Computer vision is projected to register the fastest growth as avatars gain the ability to see, read expressions and respond to users in real time through cameras. Face and body tracking let avatars mirror users in virtual meetings and games, and sentiment detection adjusts tone during support calls. Headsets and smartphones with better sensors, together with more efficient models that run on devices, are widening use in telepresence, retail try-on and virtual events. Lip sync, gesture generation and voice cloning are improving together, which makes finished avatars more convincing and easier to use.
By Application, Virtual Agents and Assistants Dominates Digital Avatar Market; Virtual Companions and Others to Register Fastest Growth.
Virtual agents and assistants dominate the Digital Avatar Market because banks, retailers, telecom operators, healthcare providers and public agencies use avatar-fronted chat and video to handle questions, bookings and onboarding. A friendly visual presence increases engagement compared with text, and companies save on staffing for routine tasks. Deployments on websites, kiosks and mobile apps are growing, and multilingual capability helps organizations serve diverse customers with a single product. Contact centers also use avatars to guide callers through identity checks and simple transactions, reducing handling time.
Virtual companions and other applications are projected to register the fastest growth as consumers use persistent avatars for conversation, coaching, language practice and entertainment. Mental wellness and language learning tools adopt avatars as tutors and guides, and gaming studios add intelligent characters. Subscription models and in-app purchases support revenue, though providers face scrutiny over safety for younger users and over dependence, which is leading to new policies and age controls. Brands also license virtual characters for advertising, and some creators earn income from stylized personas that interact with fans.
By End Use, Enterprise Dominates Digital Avatar Market; Consumer to Register Fastest Growth.
Enterprise use dominates the Digital Avatar Market because companies buy platforms for training, marketing, support and internal communications with multi-year contracts and multi-user licenses. Large employers use avatars to produce compliance and onboarding modules in many languages, and sales teams generate personalized videos. Security reviews, brand controls and integration with existing software favor established vendors, which keeps average contract values high compared with individual subscriptions. Procurement teams also value service levels, audit logs and admin controls, which large platform vendors provide as standard.
Consumer use is projected to register the fastest growth as creators, students and social media users adopt low-cost apps to make talking-head videos, stylized avatars and digital twins. Social platforms and messaging apps are adding avatar features, and games and virtual worlds let users build persistent identities. Lower subscription prices, mobile-first tools and viral content formats are drawing very large numbers of users, especially in Asia Pacific. Free tiers and short trials also help new users learn tools, and many of them later upgrade to paid plans for longer videos.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.00 |
|
Asia Pacific |
China |
37.00 |
|
Europe |
United Kingdom |
26.00 |
|
Latin America |
Brazil |
48.00 |
|
Middle East & Africa |
United Arab Emirates |
34.00 |
North America Digital Avatar Market Insights
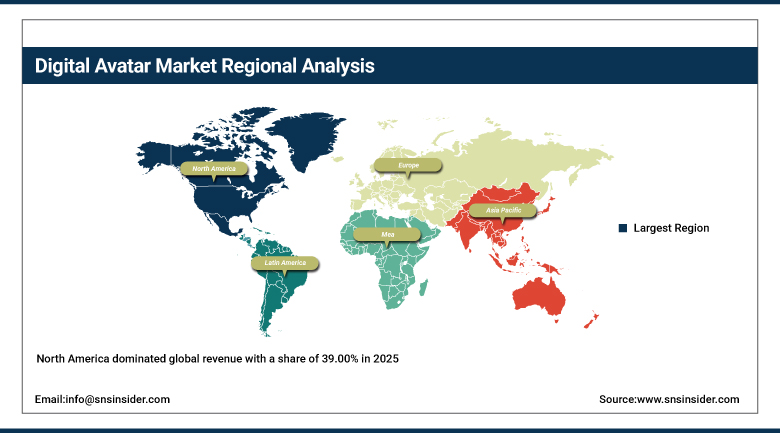
North America dominated global revenue with a share of 39.00% in 2025. The United States accounts for the major share of regional demand, with Canada adding volume through media, gaming and enterprise software. NVIDIA, Meta, Microsoft, Epic Games, HeyGen, D-ID, Soul Machines and UneeQ are among the companies serving the region. Canada adds demand through game studios, media production and enterprise software firms in Toronto, Montreal and Vancouver, while Mexico adds smaller volumes through contact centers and marketing agencies serving Spanish-speaking audiences.
Strong venture funding, leading chip and cloud providers, and early enterprise buyers support leadership. Marketing, learning and support teams in large companies adopt avatar video at scale, and game and media studios use digital humans for production. Rules on synthetic media, rising scrutiny of deepfakes and the cost of real-time compute moderate growth, but demand from customer service automation continues to widen. Universities, studios and technology companies in the region also research avatar realism and safety, and trade groups are working on standards for disclosure and consent that could shape rules elsewhere.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Digital Avatar Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 35.20% during 2026-2035. China leads regional demand, followed by Japan, South Korea, India and Southeast Asia, supported by very large mobile user bases, live-commerce culture and strong virtual idol and gaming industries. ByteDance, Tencent, Huawei Cloud, SenseTime, Cover Corp, Anycolor, DeepBrain AI and Samsung are among the major participants. Indonesia, Vietnam and Thailand add rising volumes through creators and e-commerce platforms, while Australia adds enterprise demand for training and support avatars delivered through cloud software.
Virtual hosts for live shopping, bank service avatars and virtual idols attract large audiences in the region, and local platforms bring avatar tools to millions of creators. Governments and enterprises in Korea, China and India are testing avatar-based public services and education. Content rules, language diversity and differing data laws complicate cross-border expansion, though strong consumer adoption supports fast growth. Telecom operators and super apps in the region also bundle avatar features with messaging and payments, which speeds adoption among consumers who already use these services every day.
Europe Digital Avatar Market Insights
Europe is the third-largest region. The United Kingdom, Germany, France, the Netherlands and the Nordic countries lead regional demand, supported by enterprise training, media and public-sector digital services. Synthesia and a growing set of local startups serve the region, together with global platform companies. Germany and France add large enterprise training volumes, the Netherlands and the Nordic countries add early adopter demand in finance and telecom, and Spain and Italy add demand through marketing agencies and media producers.
European buyers value compliance, and the EU Artificial Intelligence Act introduces transparency duties for synthetic media, which favors vendors that offer watermarking, consent management and secure hosting. Multilingual needs across many countries support demand for automatic dubbing and localization. Fragmented markets and cautious data protection practices slow some deployments, but corporate learning and marketing use are expanding quickly. Universities and research institutes in the region also work on speech, animation and ethics of synthetic media, and public funding for AI projects supports pilots in education and government services.
⮞On January 26, 2026, London-based Synthesia announced a USD 200.00 million Series E round led by Google Ventures at a valuation of about USD 4.00 billion. The company said it will use the funding to expand its AI video platform for business training and communications.
MEA & Latin America Digital Avatar Market Insights
In Latin America, Brazil leads, followed by Mexico, Argentina and Colombia, with regional demand growing at steady pace annually. Retailers, banks and telecom firms use avatars for service and marketing, and local startups are building emotional and conversational characters. Spanish and Portuguese models, growing creator communities and rising mobile use support adoption, while limited enterprise budgets and compute access moderate growth. Mexico, Argentina and Colombia add smaller volumes through banks, retailers and media, and universities and creator networks in the region are building local language voices and characters for Spanish and Portuguese audiences.
In the Middle East and Africa, the United Arab Emirates and Saudi Arabia lead demand, followed by Israel, Turkey and South Africa. Governments use avatars to humanize digital services and promote national AI strategies. On June 24, 2026, the UAE Presidential Court's International Affairs Office introduced an AI-generated spokesperson named Zayed, and on August 4, 2025, Dubai's digital services arm launched a virtual Emirati family. Saudi Arabia adds demand through national AI programs and large entertainment projects, and Israel adds technology supply through startups that build voice and video models for global customers.
Market Dynamics
Growth Drivers: Generative AI, Content Demand and Customer Service Automation
Advances in generative AI have made avatars more realistic, expressive and responsive, while costs per minute of video continue to fall. Companies need far more video and personalized content than they can produce with studios, and avatars let them create content in many languages from a script. Growth of remote and hybrid work has also increased use of recorded training and communication content.
Customer service automation is a second driver, since organizations want engaging, always-available agents that can handle routine questions. Funding for leading vendors and platform investment by large technology companies add capacity and attention to the market. Cloud platforms from large technology companies also make avatar tools easier to deploy and scale. Rising spending on artificial intelligence by large companies also supports vendor funding and product development across the sector.
Restraints: Deepfake Risk, Likeness Rights and Compute Cost
Concerns over deepfakes, fraud and misinformation lead to regulation and public mistrust, and companies must manage consent for the use of real people's likenesses. Rules for disclosure and watermarking vary by country, adding compliance cost. Platforms must also invest in detection tools and moderation to limit abuse of their services.
Real-time conversational avatars need substantial computing power, which raises cost at scale. Uneven quality, the uncanny valley effect and user preference for human contact in sensitive cases also limit use in some settings. Some users distrust synthetic presenters, so companies may keep human staff for sensitive messages. Clear policy and standards work is still developing, which creates uncertainty for global rollouts.
Opportunities: Digital Twins, Education and Public Services
Digital twins that can be created from short recordings give executives, teachers and creators a way to scale their presence. Education, language learning and corporate training offer large use cases for patient, multilingual avatar tutors. Subscriptions bundled with learning platforms and creative suites can also reach new groups of buyers.
Governments and public agencies are testing avatars as guides and spokespeople, and healthcare, banking and retail offer further opportunities for compliant, branded agents. Emerging markets with fast mobile growth provide large new audiences. Healthcare, banking and retail brands may adopt compliant avatar agents once standards for safety and disclosure mature. Partnerships with telecom and software firms can speed distribution.
Recent Developments:
- 2026: the UAE Presidential Court's International Affairs Office introduced an AI-generated spokesperson named Zayed. The avatar shares policy priorities and engagements with local and international audiences.
- 2026: Synthesia announced a USD 200.00 million Series E round at a valuation of about USD 4.00 billion. The round was led by Google Ventures.
- 2026: NVIDIA Corporation expanded its NVIDIA ACE digital-human technology with an on-device Game Agent SDK and Unreal Engine 5 plugins for building interactive AI characters and companions.
Digital Avatar Market Key Players
- Synthesia Ltd.
- HeyGen Technology Inc.
- D-ID Creative Reality Ltd.
- NVIDIA Corporation
- Epic Games, Inc.
- Meta Platforms, Inc.
- Microsoft Corporation
- Soul Machines Ltd.
- UneeQ Ltd.
- DeepBrain AI Co., Ltd.
- Hour One AI
- Didimo, Inc.
- Ready Player Me
- ByteDance Ltd.
- Cover Corp.
- Anycolor Inc.
- Huawei Technologies Co., Ltd.
- SenseTime Group Inc.
- Samsung Electronics Co., Ltd.
- Tencent Holdings Ltd.
Digital Avatar Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 7.35 Billion |
| Market Size by 2035 | USD 116.26 Billion |
| CAGR | CAGR of 31.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Interactive Avatars, Non-Interactive Avatars) • By Technology (AI and Machine Learning, 3D Rendering and Animation, Computer Vision, Speech Recognition and Synthesis, Natural Language Processing) • By Application (Virtual Agents and Assistants, Virtual Influencers, Gaming and Virtual Characters, Virtual Companions, Marketing and Advertising, Others) • By End Use (Enterprise, Consumer, Government and Public Sector) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Synthesia Ltd., HeyGen Technology Inc., D-ID Creative Reality Ltd., NVIDIA Corporation, Epic Games, Inc., Meta Platforms, Inc., Microsoft Corporation, Soul Machines Ltd., UneeQ Ltd., DeepBrain AI Co., Ltd., Hour One AI, Didimo, Inc., Ready Player Me, ByteDance Ltd., Cover Corp., Anycolor Inc., Huawei Technologies Co., Ltd., SenseTime Group Inc., Samsung Electronics Co., Ltd., Tencent Holdings Ltd. |

Frequently Asked Questions
Key players include Synthesia Ltd., HeyGen Technology Inc., D-ID Creative Reality Ltd., NVIDIA Corporation, Epic Games, Inc., Meta Platforms, Inc., Microsoft Corporation and Soul Machines Ltd.
Key opportunities include digital twins created from short recordings, avatar tutors in education and training, and public service avatars in government and healthcare.
The major growth factor is generative AI, which makes avatars more realistic and cheaper to produce, together with enterprise demand for scalable video and service automation.
By Type, the Interactive Avatars segment dominated the market in 2025 with an estimated 60.00% share, supported by customer service and training deployments.
North America dominated the market with a share of 39.00% in 2025, driven by platform companies, venture funding and early enterprise adoption.
