
Digital Experience Platform Market Report Scope & Overview:
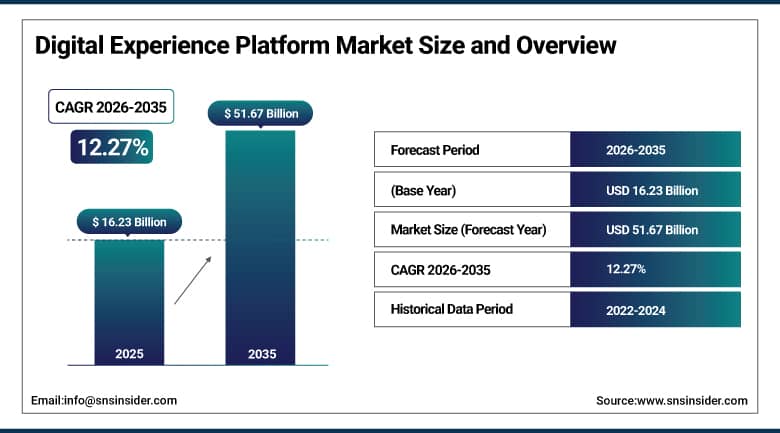
The Digital Experience Platform Market was valued at USD 16.23 Billion in 2025 and is expected to reach USD 51.67 Billion by 2035, growing at a CAGR of 12.27% from 2026-2035.
The Digital Experience Platform market is being driven mainly by businesses becoming more interested in creating smooth and personalized customer experience through growing numbers of digital touchpoints, where companies are moving away from traditional monolithic content management systems towards API-first platforms which can help unify customer data, content, and personalization technologies through web and mobile channels. Growing integration of artificial intelligence and machine learning capabilities, along with increasing AI agency, is allowing for smarter, predictive, and automated customer engagement as vendors are striving to incorporate generative and agentic AI directly into content creation and personalization and channel visibility workflows. Growing investments in digital transformation of enterprises is making the use of DXPs increasingly necessary.
In 2025, Salesforce closed its USD 8 billion acquisition of Informatica, followed by additional acquisitions including Momentum, Qualified, and Cimulate, before agreeing to acquire Berlin-founded headless content platform Contentful on June 1, 2026, extending its Customer 360 and Headless 360 product lines to serve more than 4,800 existing Contentful brand customers. The acquisition spree reflects the broader industry pattern of established CRM and customer experience vendors expanding digital experience platform capability through acquisition, reinforcing the competitive position of well-capitalized platforms pursuing integrated, AI-enabled content, commerce, and customer data strategies.
To Get More Information On Digital Experience Platform Market - Request Free Sample Report
Digital Experience Platform Market Trends
- Rising integration of agentic AI capability into content creation, personalization, and customer engagement workflows.
- Growing vendor investment in AI-driven brand visibility and answer-engine optimization across AI-powered search channels.
- Expanding adoption of composable, headless architecture enabling enterprises to swap platform components independently.
- Increasing consolidation among DXP vendors through acquisitions of specialized content, commerce, and AI visibility platforms.
- Rising enterprise demand for unified customer data platforms integrated directly within core digital experience architecture.
U.S. Digital Experience Platform Market Outlook
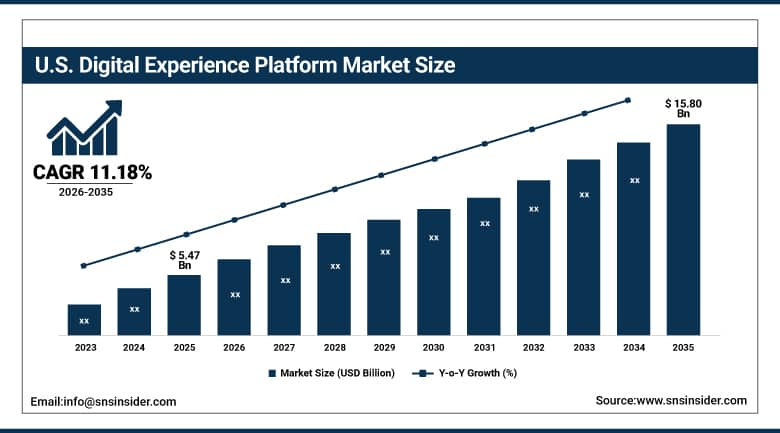
The U.S. Digital Experience Platform Market was valued at USD 5.47 Billion in 2025 and is expected to reach USD 15.80 Billion by 2035, growing at a CAGR of 11.18% from 2026-2035.
The U.S. Digital Experience Platform Market growth continues to be reinforced by the country's concentration of major DXP vendors and early enterprise adoption of AI-driven personalization and omnichannel customer engagement technology. Domestic retailers, banks, and media companies continue to expand DXP deployment to enable omnichannel commerce, instant checkout flows, and AI-powered product and content recommendations across increasingly complex digital customer journeys. The increasing investments by firms towards integrating marketing, analytics, and customer services into an AI-enabled platform will keep contributing to the growth of DXP use, not only for major corporations but also for smaller firms, who are looking for ways of adopting such technologies. Moreover, another contributor to growth will be domestic vendors’ investments in AI-based search optimization.
In February 2025, Klaviyo, a Boston-based marketing technology company, launched Klaviyo B2C CRM, the first customer relationship management platform built specifically for business-to-consumer brands, unifying marketing, analytics, and customer service into a single AI-powered platform to help brands deliver seamless, personalized experiences across the customer journey. The launch illustrates how established U.S. marketing technology vendors continue to expand into comprehensive digital experience platform capability, extending beyond point solutions to compete directly with established enterprise DXP vendors for B2C brand customers.
Digital Experience Platform Market Segment Analysis
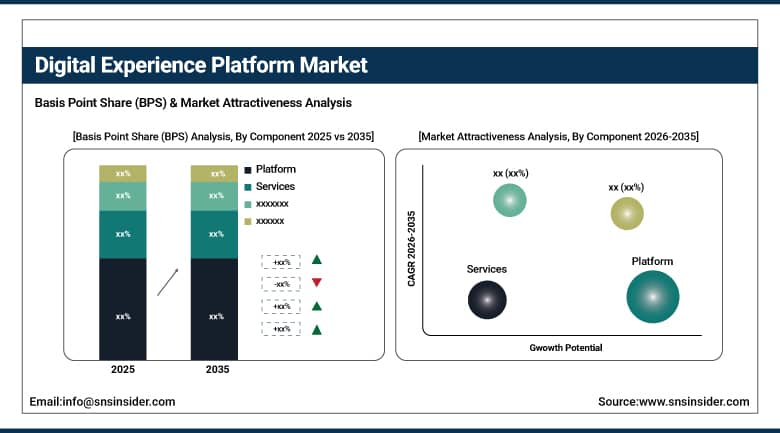
- By Component, the platform segment dominated the digital experience platform market with approximately 68.60% share in 2025, while the services segment is the fastest growing with a CAGR of approximately 13.40%.
- By Deployment Mode, the cloud segment dominated the digital experience platform market with approximately 58.40% share in 2025, and is also the fastest growing with a CAGR of approximately 13.20%.
- By Organization Size, the large enterprises segment dominated the digital experience platform market with approximately 60.60% share in 2025, while the SMEs segment is the fastest growing with a CAGR of approximately 12.80%.
- By Application, the B2C segment dominated the digital experience platform market with approximately 60.20% share in 2025, while the B2B segment is the fastest growing with a CAGR of approximately 13.80%.
- By End-Use Industry, the retail & e-commerce segment dominated the digital experience platform market with approximately 28.60% share in 2025, while the BFSI segment is the fastest growing with a CAGR of approximately 13.10%.
By Component, platform dominates the digital experience platform market and services grows fastest
The platform component dominates in the Digital Experience Platform market since subscriptions to basic software services and licenses constitute the technological investment in managing digital experiences. An integration of features related to content management, customer data, personalization, analytics, automation, and omnichannel delivery plays an increasingly important role in determining enterprise purchases. Enterprise preferences are moving towards platforms which can integrate many digital touchpoints while enhancing consistency and engagement. Repeated subscriptions and increasing AI functionality make the case even stronger for the dominance of the platform category.
Services represent the segment which grows fastest due to the increased need for specialized skills to properly implement, integrate, customize, and optimize the increasingly complex DXP environment. Services such as consulting, implementation, integration, training, and managed services enable businesses to speed up their deployment and link DXP solutions to enterprise-level applications and data infrastructures. The adoption of the composable approach, AI-powered personalization, and omnichannel experiences increases the level of implementation complexity and makes service providers highly valued.
By Deployment Mode, cloud dominates the digital experience platform market and also grows fastest
Cloud-based deployment takes the lead in the DXP market since companies tend to move from their existing on-premises solutions to flexible subscription-based platforms. Cloud-based DXPs minimize the need for managing infrastructures and provide faster updates, integration, and flexibility for distributed teams. The potential of cloud-based platforms to unify content, customer data, analytics, and personalization features makes such a solution the most promising choice for delivering seamless experiences via different digital channels.
The cloud is growing at the fastest pace because more organizations prefer to focus on scalability, cost-effectiveness, agility, and fast deployment of their digital transformation efforts. Cloud DXPs provide enterprises with the ability to scale up their computing capacity based on varying workloads without the need for huge amounts of internal infrastructures. Growth is being fueled by the greater adoption of technologies such as AI-based personalization, automation of content creation, real-time analytics, and intelligent customer engagement functionalities. All of these advanced computing requirements take advantage of cloud-native computing capabilities to process huge amounts of customer data.
By Organization Size, large enterprises dominates the digital experience platform market and SMEs grows fastest
Large enterprises dominate the Digital Experience Platform market because comprehensive DXP implementations require substantial technology budgets, dedicated IT teams, and integration capabilities. These organizations typically manage complex digital ecosystems spanning websites, mobile applications, commerce platforms, customer data, and multiple brands or business units. Their need for centralized content management, personalization, analytics, and customer-data integration encourages investment in sophisticated DXP solutions. Large enterprises are also increasingly adopting AI-driven capabilities to unify customer experiences, automate content workflows, and support personalized engagement across diverse digital touchpoints and markets.
Small and medium enterprises constitute the fastest-growing size category of organizations, because DXPs have been customizing and scaling solutions to suit small enterprises with smaller IT budgets. Subscription-based solutions, solutions that can be deployed easily, and self-service solutions have reduced barriers to entry and enabled SMEs to obtain digital experience functionalities without having to make big investments in IT infrastructure. Availability of AI-driven personalization, automated content generation, analytics, and other tools is also helping adoption efforts. As SMEs are becoming more focused on digital engagement with customers, the adoption of DXP solutions is rapidly growing.
By Application, B2C dominates the digital experience platform market and B2B grows fastest
Business-to-consumer (B2C) applications dominate the Digital Experience Platform market because B2C organizations depend heavily on personalized, seamless, and consistent digital experiences to attract customers and generate direct online revenue. The use of DXP platforms by retailers, banks, travel businesses, media firms, and consumer goods brands for managing content, commerce, customer information, personalization, and engagement on web, mobile, and social media channels is rising. The growing popularity of artificial intelligence (AI)-enabled recommendation engines, real-time personalization, and omnichannel commerce is adding momentum to the trend driven by B2C companies’ competitive need to satisfy customers.
Business-to-business (B2B) applications are the fastest-growing segment as organizations increasingly digitize complex purchasing journeys, account management, lead nurturing, and customer relationship processes. Expectations from B2B customers have changed in recent times, and there is a demand for more convenient and personalized digital interactions, which has encouraged companies to transform traditional sales channels and means of communication. DXPs allow B2B companies to integrate all the elements like content, customer data, analytics, personalization, and marketing automation through various channels. Adoption of AI-powered customer insights and digital commerce functionality has further driven the adoption of B2B DXPs.
By End-Use Industry, retail & e-commerce dominates the digital experience platform market and BFSI grows fastest
Retail and e-commerce have become key sectors where DXP solutions have a major presence due to the importance of digital experience platforms in omnichannel business models, personalized interactions and purchases, and buying experiences. There has been an increasing adoption by retailers of functionalities available via DXPs for coordination of content, recommendations, promotions, consumer data, and transactions in sites and apps and other digital channels. The ongoing growth of e-commerce and increasing expectations on the part of consumers for seamless and personalized experiences continue to drive investment in technology in this industry.
BFSI represents the fastest-growing end-use industry as banks, insurers, and financial service providers accelerate digital transformation across customer onboarding, online banking, insurance portals, and self-service channels. The growing need for more secure, convenient, and customized interaction with financial institutions is prompting these entities to upgrade their disjointed digital landscapes and unite their customer data through several different touchpoints. Financial organizations can provide consistent content, personalization, and automation with the help of DXP solutions. Increasing use of AI-driven personalization and digital customer-service capabilities is further strengthening DXP adoption across banking and insurance operations.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
40.60% |
|
Europe |
Germany |
28.60% |
|
Middle East & Africa |
United Arab Emirates |
25.80% |
|
Latin America |
Brazil |
30.20% |
North America Digital Experience Platform Market Insights
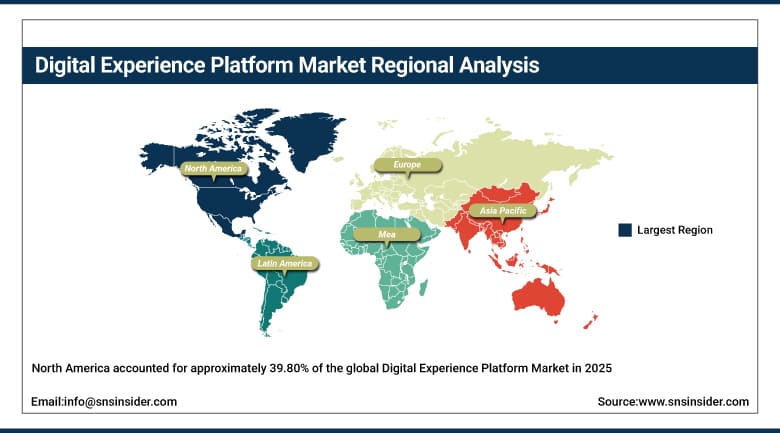
North America accounted for approximately 39.80% of the global Digital Experience Platform Market in 2025, making it the largest regional market, supported by early enterprise adoption of DXP technology and substantial ongoing investment among domestic retailers, banks, and technology companies. The region's concentration of major DXP vendors, combined with strong enterprise digital transformation investment, continues to anchor North America's leading market position.
Canada is helping provide gradual demand in light of growth in investments made by regional companies in the area of digital customer engagement. Business importance is growing more and more in the region as digital transformation is becoming increasingly important for companies in terms of competitiveness, while big companies keep innovating through implementation of platforms that integrate AI.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Digital Experience Platform Market Insights
Asia Pacific is the fastest-growing regional market, expanding at a CAGR of approximately 12.90% from 2026 to 2035, driven by rapidly expanding e-commerce activity, rising enterprise digital transformation investment, and growing adoption of cloud-native DXP platforms across China, India, and Southeast Asian markets. The robust demand for regional DXP solutions is being fueled by the large domestic e-commerce and digital retail ecosystem in China, along with scale contributions from Japan and South Korea through the presence of their well-established technology industry.
There is considerable incremental growth being generated by India due to its rapid digital economy and growing enterprise cloud adoption. Regional cloud infrastructure investment continues to support faster DXP platform deployment across the region, reinforcing Asia Pacific's position as the fastest-growing market through the forecast period.
Europe Digital Experience Platform Market Insights
Europe represents a significant share of the global Digital Experience Platform Market, anchored by Germany's large enterprise technology sector and the region's strong data privacy regulatory framework, which continues to shape how DXP vendors architect customer data handling and personalization capability. European enterprises continue to prioritize DXP platforms capable of delivering compliant, GDPR-aligned personalization across increasingly complex digital customer journeys.
The United Kingdom, France, and Italy are contributing steady demand growth as regional enterprises extend DXP adoption from large multinational corporations into broader mid-market enterprise segments. Regional vendors continue to invest in composable, headless architecture to serve the region's diverse regulatory and localization requirements across multiple European markets.
MEA & Latin America Digital Experience Platform Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing digital transformation investment across the United Arab Emirates and Saudi Arabia sustains demand for modern customer engagement platforms. Regional enterprises, particularly within banking and retail, continue to invest in DXP capability to support national digital economy initiatives.
The Latin American market is dominated by Brazil, where the use of e-commerce and digital banking services keeps increasing and driving DXP adoption. Mexico is helping to fuel the growth as companies in the region continue to invest in digital transformation. In the region, the adoption remains mostly limited to large companies and financial institutions with digital infrastructure.
Market Dynamics
Growth Drivers: Digital Transformation Priority and AI Integration
Organizations increasingly prioritizing seamless customer experiences across digital touchpoints represents the primary driver of Digital Experience Platform Market growth, as businesses undergoing digital transformation continue to treat comprehensive DXP adoption as a competitive necessity rather than an optional technology investment. Rising integration of AI, machine learning, and increasingly agentic capability into DXP solutions is providing more intuitive and interactive experiences for users, reinforcing platform adoption across an expanding range of industries and organization sizes.
The continued shift from monolithic content systems toward modular, API-first stacks represents a second major growth driver, as enterprises seek platform architecture capable of harmonizing customer data, content, and personalization engines across web, mobile, and emerging touchpoints. Growing enterprise recognition that digital experience quality directly influences customer acquisition and revenue generation continues to reinforce DXP investment as a strategic priority across retail, financial services, and other customer-facing industries.
Restraints: Platform Complexity and Integration Costs
The complexity involved in comprehensive DXP platforms, especially those providing a vast feature set that includes content management, commerce, personalization, and customer data unification, is a significant barrier to growth in the market, because such complexity may make the platform difficult to deploy for non-technical users or companies with minimal technical expertise. This barrier is especially true of enterprises looking at DXP platforms with large partner ecosystems.
The substantial implementation and customization costs associated with comprehensive DXP deployments represent a further restraint, as organizations must weigh platform licensing costs against the additional services investment required to achieve full platform value. This cost consideration constrains the pace at which comprehensive DXP capability can extend from well-resourced large enterprises into smaller organizations with more limited technology budgets.
Opportunities: Agentic AI Integration and Composable Architecture Expansion
Continued integration of agentic AI capability into content creation, personalization, and customer engagement workflows represents a substantial opportunity, as vendors that can embed AI-driven brand visibility and answer-engine optimization directly into core platform architecture are positioned to differentiate as digital discovery increasingly shifts toward AI-powered search and conversational channels. Vendors pursuing this capability through both acquisition and in-house development continue to reshape competitive positioning across the DXP vendor landscape.
Another way in which businesses can grow is by continuing to expand their use of composable and headless architecture, as more and more businesses look for ways to replace parts of a technology stack, rather than being stuck with one vendor’s stack alone. Companies that have the ability to offer headless content delivery, as well as wide third-party integrations, are sure to benefit from this trend.
Recent Developments:
- 2026: Sitecore acquired Scrunch, an AI-search visibility platform, in a deal reported at approximately USD 225 million, integrating Scrunch's Agent Experience Platform into SitecoreAI.
- 2025: Sitecore renamed its XM Cloud platform to SitecoreAI, reflecting the company's strategic pivot toward AI-driven content and experience management capability.
- 2026: Adobe renamed Experience Cloud to CX Enterprise, at April 2026 Summit, unveiling a Brand Visibility pillar governed by its Adobe Brand Intelligence system alongside general availability of its Agent Orchestrator, first launched in 2025.
- 2024: H&M Group acquired a minority stake in Voyado, a retail technology platform that enables retailers and brands to establish enduring, personalized connections with their customers.
Digital Experience Platform Market Key Players are:
- Adobe Inc.
- Salesforce.com, Inc.
- Oracle Corporation
- SAP SE
- Microsoft Corporation
- International Business Machines Corporation
- Sitecore
- Optimizely
- Acquia Inc.
- Bloomreach, Inc.
- Contentful GmbH
- Liferay, Inc.
- OutSystems Inc.
- Pegasystems Inc.
- Open Text Corporation
- HCL Technologies Limited
- Infosys Limited
- Magnolia International Ltd.
- Crownpeak Technology, Inc.
- censhare AG
Digital Experience Platform Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 16.23 Billion |
| Market Size by 2035 | USD 51.67 Billion |
| CAGR | CAGR of 12.27% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Platform, Services) • By Deployment Mode (Cloud, On-Premises) • By Organization Size (Large Enterprises, SMEs) • By Application (B2C, B2B) • By End-Use Industry (Retail & E-Commerce, IT & Telecom, BFSI, Healthcare, Manufacturing, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Adobe Inc., Salesforce.com, Inc., Oracle Corporation, SAP SE, Microsoft Corporation, International Business Machines Corporation, Sitecore, Optimizely, Acquia Inc., Bloomreach, Inc., Contentful GmbH, Liferay, Inc., OutSystems Inc., Pegasystems Inc., Open Text Corporation, HCL Technologies Limited, Infosys Limited, Magnolia International Ltd., Crownpeak Technology, Inc., censhare AG |
Frequently Asked Questions
Key players include Adobe Inc., Salesforce.com, Inc., Oracle Corporation, SAP SE, Microsoft Corporation, Sitecore, and Optimizely, among other enterprise software and content management vendors.
Continued integration of agentic AI capability into content and engagement workflows, along with continued expansion of composable, headless architecture, represent the primary opportunities.
Growth is primarily driven by organizations increasingly prioritizing seamless, personalized customer experiences combined with rising integration of AI and agentic capability into digital experience platforms.
By Component, Platform dominated the market with approximately 68.60% share in 2025, reflecting the foundational role of core software licensing and unified customer engagement capability.
North America dominated the market with approximately 39.80% share in 2025, supported by early enterprise adoption and a strong concentration of major DXP vendors.
