
Edge Artificial Intelligence Chips Market Report Scope & Overview:
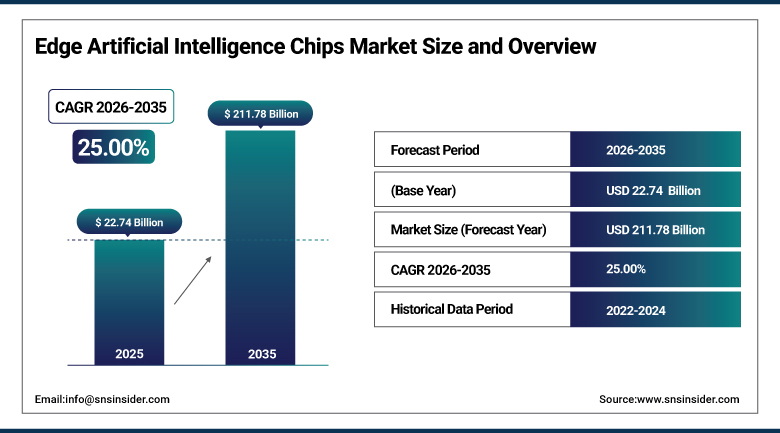
The Edge Artificial Intelligence Chips Market size was valued at USD 22.74 Billion in 2025 and is expected to reach USD 211.78 Billion by 2035, growing at a CAGR of 25.00% from 2026-2035.
The Edge Artificial Intelligence Chips Market is expanding rapidly as manufacturers move machine learning inference from cloud data centers into smartphones, vehicles, cameras, industrial controllers and sensors. Demand is supported by the need for low-latency decisions, privacy-preserving on-device processing, reduced bandwidth costs and the arrival of generative AI features on personal devices. Suppliers compete with application-specific integrated circuits, neural processing units integrated in system-on-chip designs, graphics processors, field-programmable gate arrays and emerging neuromorphic architectures. Published valuations diverge widely because research firms define the product differently, with 2025 estimates ranging from roughly USD 3.7 billion for dedicated edge accelerators to more than USD 27 billion for broader edge AI semiconductors.
⮞On October 14, 2026, Mouser Electronics announced it was shipping the Ara240 discrete neural processing unit from NXP Semiconductors, which delivers up to 40 equivalent tera-operations per second and up to 16 GB of LPDDR4 memory for generative AI, robotics and industrial edge applications. NXP also offers an M.2 accelerator module built on the chip that pairs with its i.MX 95 development boards, showing how microcontroller and applications processor vendors are adding dedicated AI accelerators for edge systems.
To Get more information Edge Artificial Intelligence Chips Market - Request Free Sample Report
Edge Artificial Intelligence Chips Market Trends
-
Generative AI and small language models running on devices
-
NPUs integrated into smartphone, PC and automotive processors
-
Advanced process nodes at 5 nm and below improving performance per watt
-
Discrete accelerators and M.2 modules for industrial and robotics applications
-
TinyML and ultra-low-power inference in battery-powered sensors
-
Neuromorphic and in-memory computing architectures for always-on processing
U.S. Edge Artificial Intelligence Chips Market Size Outlook
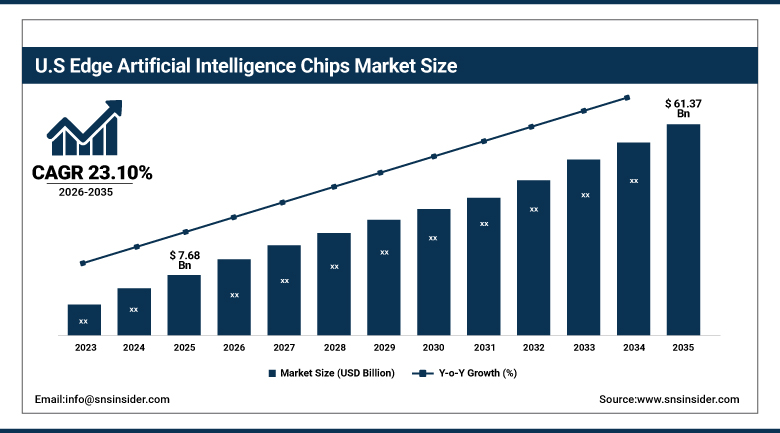
The U.S. Edge Artificial Intelligence Chips Market was valued at USD 7.68 Billion in 2025 and is expected to reach USD 61.37 Billion by 2035, growing at a CAGR of 23.10% from 2026-2035.
The U.S. Edge Artificial Intelligence Chips Market is the largest national market, supported by the headquarters of leading chip designers, extensive venture funding for AI hardware start-ups, strong demand from consumer electronics and automotive makers and federal investment in local semiconductor manufacturing. Companies including NVIDIA, Qualcomm, Intel, AMD, Apple and Google design edge processors and accelerators used in laptops, phones, robots and vehicles. Export controls on advanced AI chips and the CHIPS and Science Act shape supply chains, while defense and industrial customers seek secure on-device intelligence.
⮞In October 2024, AMD launched the Ryzen AI PRO 300 Series processors with neural processing units rated at up to 55 trillion operations per second, aimed at commercial AI PCs. The launch shows how U.S. processor makers are embedding dedicated AI engines in mainstream computing platforms, allowing enterprises to run assistants and analytics locally rather than relying exclusively on cloud services.
Edge Artificial Intelligence Chips Market Segment Analysis
-
By Chipset, the ASICs segment dominated the Edge Artificial Intelligence Chips Market with approximately 35.31% share in 2025, while the Neuromorphic Chips segment is the fastest growing with a CAGR of approximately 48.30%.
-
By Function, the Inference segment dominated the Edge Artificial Intelligence Chips Market with approximately 71.30% share in 2025, while the Training segment is the fastest growing with a CAGR of approximately 33.20%.
-
By Device, the Consumer Devices segment dominated the Edge Artificial Intelligence Chips Market with approximately 47.38% share in 2025, while the Enterprise and Industrial Devices segment is the fastest growing with a CAGR of approximately 24.10%.
-
By Process Node, the 14 nm and Above segment dominated the Edge Artificial Intelligence Chips Market with approximately 39.20% share in 2025, while the 5 nm and Below segment is the fastest growing with a CAGR of approximately 55.40%.
-
By End-Use Industry, the Consumer Electronics segment dominated the Edge Artificial Intelligence Chips Market with approximately 31.76% share in 2025, while the Automotive and Transportation segment is the fastest growing with a CAGR of approximately 26.20%.
By Chipset, ASICs Dominates the Edge Artificial Intelligence Chips Market and Neuromorphic Chips Grows Fastest
Application-specific integrated circuits remain the dominant chipset within the Edge Artificial Intelligence Chips Market, characterized by high performance per watt and a design flexibility that suits mass-produced devices. Smartphone makers, camera suppliers and automotive companies favor custom accelerators because they deliver predictable latency within strict power and thermal limits. This segment benefits from established design ecosystems at firms such as Qualcomm, Hailo and Google, and from software toolchains that translate trained models into efficient hardware, giving ASIC vendors a durable advantage in high-volume products.
Neuromorphic chips are emerging as the fastest-growing chipset, driven by interest in event-driven architectures that consume very little energy when processing sparse sensor data. Companies including BrainChip and Mythic are targeting always-on keyword detection, vision and anomaly detection in battery-powered devices, where conventional accelerators may be too power-hungry. Although revenue is still small and software maturity lags behind established architectures, rapid expansion of industrial sensing and wearables is expected to give this segment very high percentage growth from a modest base.
By Function, Inference Dominates the Edge Artificial Intelligence Chips Market and Training Grows Fastest
Inference accounts for the majority of edge chip demand because devices at the edge typically run models that were trained in the cloud, and the task is to execute them quickly with minimal power. Applications such as face recognition, object detection, speech processing and driver monitoring generate continuous inference workloads that need dedicated acceleration. Vendors optimize chips for quantized models and fixed-function operations, and the growing number of connected cameras, phones and vehicles keeps inference as the highest-volume workload for edge silicon.
Training at the edge is growing fastest as developers explore on-device fine-tuning, federated learning and personalization that keep sensitive data local. Smartphones, industrial gateways and edge servers are being equipped with more memory and compute so that models can adapt to local conditions without transmitting raw data to the cloud. Regulation of privacy and the cost of moving large data sets are encouraging these approaches, and chip designers are adding support for higher precision arithmetic and larger on-chip memory to enable incremental learning.
By Device, Consumer Devices Dominates the Edge Artificial Intelligence Chips Market and Enterprise Devices Grows Fastest
Consumer devices represent the largest device category, reflecting the enormous shipment volumes of smartphones, tablets, personal computers, wearables, smart speakers and home cameras that now include neural processing units. Manufacturers use on-device AI for photography, voice assistants, translation, health sensing and generative features, which differentiates products and justifies higher prices. Companies such as Apple, Qualcomm, MediaTek, Samsung and AMD integrate accelerators into mainstream processors, so every new device generation adds AI capability to the installed base. Premium pricing supports vendor margins.
Enterprise devices are emerging as the fastest-growing segment of the Edge AI chips market, supported by increasing investments in business automation, intelligent infrastructure, and distributed computing. Organizations are deploying AI-enabled industrial gateways, edge servers, medical equipment, retail systems, and enterprise computing devices to process data locally and enable faster decision-making. These applications support predictive maintenance, real-time analytics, automated quality inspection, workplace security, and operational optimization. Furthermore, growing concerns regarding data privacy, network latency, and cloud computing costs are encouraging businesses to adopt edge-based AI processing. Continued digital transformation, expanding Internet of Things deployments, and advancements in energy-efficient AI processors are expected to accelerate enterprise adoption throughout the forecast period.
By Process Node, 14 nm and Above Dominates the Edge Artificial Intelligence Chips Market and 5 nm and Below Grows Fastest
Chips built at 14 nm and above account for the largest share because many edge AI products, including industrial controllers, cameras and microcontroller-based devices, prioritize cost, longevity and supply stability over peak performance. Mature nodes offer lower mask costs, proven yields and abundant foundry capacity, which suits start-ups and specialized suppliers with modest volumes. Automotive and industrial customers also favor mature processes that meet qualification standards, so this tier remains the backbone of volume shipments. Long product lifecycles further support stable demand.
Chips at 5 nm and below are growing fastest, as premium smartphones, AI laptops and advanced driver assistance platforms demand greater computing density and better energy efficiency. Smaller nodes allow more transistors for neural engines within a fixed power budget, enabling larger on-device models and generative AI features. High design and mask costs concentrate this segment among large incumbents, but foundry access to leading-edge capacity and growing average selling prices for flagship products support rapid revenue growth. Premium flagship launches reinforce this momentum.
By End-Use Industry, Consumer Electronics Dominates the Edge Artificial Intelligence Chips Market and Automotive and Transportation Grows Fastest
Consumer electronics lead because smartphones, PCs, televisions, earbuds and smart home products ship in volumes far larger than any other category, and nearly all premium models now advertise on-device AI features. Competition among device makers drives frequent upgrades in neural engine performance, and chip suppliers secure large multi-year design wins. The strong replacement cycle for phones and the arrival of AI-capable personal computers help sustain demand for edge processors in this industry. Retail promotion of AI-enabled devices reinforces consumer awareness.
Automotive and transportation is growing fastest as vehicles adopt advanced driver assistance, in-cabin monitoring, and centralized computing architectures that rely on powerful on-board AI processors. Automakers and suppliers are integrating chips from NVIDIA, Qualcomm, NXP, Renesas and others to run perception and decision models in real time without depending on connectivity. Regulatory attention to safety features and the move toward software-defined vehicles are lengthening design cycles but locking in multi-year volume commitments for qualified suppliers. Over-the-air updates allow vehicles to receive improved AI models after purchase.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
87.46 |
|
Asia Pacific |
China |
41.73 |
|
Europe |
Germany |
32.58 |
|
Middle East & Africa |
Israel |
46.19 |
|
Latin America |
Brazil |
44.82 |
North America Edge Artificial Intelligence Chips Market Insights
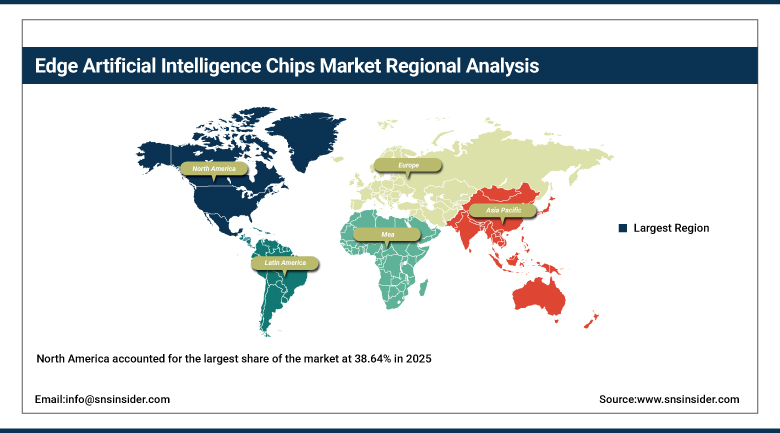
North America accounted for the largest share of the market at 38.64% in 2025, supported by the concentration of leading chip designers, hyperscale cloud companies and device brands that drive early adoption of on-device AI. The United States dominates, with Canada contributing through AI research hubs and automotive suppliers. The region is projected to expand at a CAGR of 23.10% through 2035, reflecting strong demand for AI PCs, vehicle computing platforms and industrial vision systems. Cloud providers also develop their own edge accelerators.
The presence of NVIDIA, Qualcomm, Intel, AMD, Apple and Google, together with start-ups such as SiMa.ai, Mythic and Syntiant, creates a deep innovation ecosystem. Federal incentives for local chip manufacturing aim to strengthen supply security, while export controls on advanced AI chips shape product design and market access. Reliance on foundries in Asia, high development costs and talent shortages are factors that moderate growth and encourage investment in advanced packaging and local capacity. Defense and aerospace programs add demand for secure, ruggedized edge processors.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Edge Artificial Intelligence Chips Market Insights
Asia Pacific held 36.28% of the market in 2025 and is the fastest-growing region, advancing at a CAGR of 27.80% during 2026-2035. China, Taiwan, South Korea and Japan lead through consumer electronics manufacturing, foundry capacity and automotive production. Taiwan's foundry and packaging industry supplies a large share of the world's leading-edge chips, and MediaTek, Samsung, Sony and Renesas are major designers of edge processors. South Korea contributes memory and mobile processor strength through Samsung, and Japan adds automotive and image sensor expertise, while India and Australia expand device adoption.
China is building local edge AI capability through companies such as Huawei and a growing group of smart camera and automotive chip designers, supported by government programs and a vast base of surveillance, smartphone and electric vehicle makers. India is emerging as a design and assembly center, and Southeast Asia benefits from electronics production shifting from China. Export restrictions, geopolitical tension and dependence on leading-edge foundry capacity in a small number of locations are risks, but demand growth remains the highest globally. Local governments are also funding smart city and traffic management projects that deploy AI cameras at large scale.
Europe Edge Artificial Intelligence Chips Market Insights
Europe held 16.45% of the market in 2025 and is projected to grow at a CAGR of 23.90% through 2035. Germany leads through its automotive and industrial automation base, while the Netherlands, France, Italy and the United Kingdom contribute through semiconductor companies such as NXP, STMicroelectronics and Infineon, AI accelerator start-ups such as Axelera AI, and the processor intellectual property of Arm. Sweden and Finland add telecommunications and industrial automation demand through established equipment makers, research clusters and strong software talent.
The European Chips Act and national programs support local manufacturing and design, with a particular emphasis on automotive, industrial and secure embedded applications. Strong regulation on data protection favors on-device processing that keeps personal data local, while the region's leadership in microcontrollers and power electronics positions suppliers to integrate AI engines into existing product lines. Smaller consumer electronics volumes and slower adoption of leading-edge nodes limit the region's overall share relative to Asia and North America. Cooperation among research institutes and carmakers on automated driving also sustains regional design activity.
MEA & Latin America Edge Artificial Intelligence Chips Market Insights
The Middle East and Africa held 4.52% of the market in 2025 and is projected to grow at a CAGR of 25.00%. Israel leads through chip designers such as Hailo and a strong defense and automotive technology sector, while Saudi Arabia and the United Arab Emirates are investing in national AI strategies, smart city projects and advanced manufacturing that increase demand for edge hardware. Regional data centers and telecom operators are also trialing edge deployments at scale for video analytics and network functions.
Latin America held 4.11% of the market in 2025 and is projected to grow at a CAGR of 24.20%. Brazil and Mexico lead through electronics assembly, telecommunications and automotive production, with demand rising for smart cameras, retail analytics and connected vehicles. Limited local semiconductor design capacity and import dependence mean that most chips are sourced from Asia, North America and Europe, so growth depends on device adoption and on multinational manufacturers localizing AI-enabled products. Trade agreements and nearshoring are gradually improving access to components and assembly partners.
Market Dynamics
Growth Drivers: On-Device Generative AI and Demand for Low-Latency, Private Processing
On-device generative AI is a primary driver of demand for edge AI chips. Smartphone, PC and automotive makers are adding assistants, translation, image generation and summarization features that run locally, and these workloads require neural engines with high throughput and large memory bandwidth. Each product generation raises the performance expectations, leading chip suppliers to increase NPU capability and encouraging consumers to upgrade devices to access new AI functions.
Demand for low-latency, private and reliable processing reinforces this trend. Industrial robots, autonomous machines and safety systems cannot depend on network connections, while regulations and customer concerns favor keeping personal and sensitive data on the device. Local inference also reduces cloud costs and bandwidth consumption as the number of sensors and cameras expands, and advances in 5G, advanced process nodes and efficient model compression make powerful AI feasible within tight power budgets.
Restraints: High Design Costs, Fragmented Software and Export Controls
High design and tape-out costs restrain the market, because developing a competitive chip at advanced nodes can cost hundreds of millions of dollars and requires scarce engineering talent. These economics favor large incumbents and make it difficult for start-ups to reach scale, while customers are reluctant to commit to unproven suppliers for long-lived products. Thermal limits in fanless, battery-powered designs also constrain achievable performance and complicate the integration of larger models.
The existence of fragmented software toolchains and export controls presents additional complications. The porting of models using different compilers, runtime environments, and hardware platforms is even harder, contributing to increased development costs and extended deployment times. The restrictions in the exportation of state-of-the-art AI processors and fabrication facilities, together with the geostrategic aspects in relation to the capability of foundries to produce such state-of-the-art products, introduces uncertainties in relation to supply and market access.
Opportunities: Industrial and Automotive AI, Discrete Accelerators and Neuromorphic Computing
Industrial and automotive markets provide major potential as factories, logistics, and automobiles employ vision, prediction maintenance and driver monitoring solutions. Using discrete accelerators, which include M.2 boards, allows for adding AI capabilities to already existing processors without changing the whole system. Suppliers, which deliver high-quality components with proven software stacks, have the opportunity to enter multi-year projects with increased margins compared to consumer products.
Neuromorphic and in-memory computing offer longer-term opportunities for always-on sensing at microwatt power levels, which could open applications in wearables, medical implants and remote sensors. Emerging markets in Southeast Asia, India and the Middle East present further potential as local manufacturers build AI-enabled products. Vendors that combine efficient silicon with developer tools, pretrained models and ecosystem partnerships can accelerate adoption and reduce the barrier for customers new to edge AI.
Recent Developments:
-
2024: SiMa.ai introduced its MLSoC Modalix edge AI product family, rated at up to 200 trillion operations per second. The family is designed to run multimodal and generative AI workloads in embedded systems.
-
2024: Kneron launched the KNEO 330 edge AI server rated at 48 TOPS and the KL830 AI-embedded PC chip. The products extend the company's portfolio into edge servers and AI-enabled personal computers.
-
2024: Hailo unveiled the Hailo-10 generative AI acceleration module for edge devices and announced an additional USD 120 million in funding. The module brings generative AI capability to cameras, PCs and automotive systems.
Edge Artificial Intelligence Chips Companies are:
-
Qualcomm Incorporated
-
Intel Corporation
-
Advanced Micro Devices, Inc.
-
Apple Inc.
-
Alphabet Inc. (Google)
-
Samsung Electronics Co., Ltd.
-
Huawei Technologies Co., Ltd.
-
Arm Holdings plc
-
STMicroelectronics N.V.
-
NXP Semiconductors N.V.
-
Texas Instruments Incorporated
-
Renesas Electronics Corporation
-
Hailo Technologies Ltd.
-
BrainChip Holdings Ltd.
-
SiMa.ai
-
Kneron, Inc.
-
Syntiant Corp.
-
Axelera AI
Edge Artificial Intelligence Chips Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 22.74 Billion |
| Market Size by 2035 | USD 211.78 Billion |
| CAGR | CAGR of 25.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Chipset (ASICs, GPUs, CPUs, FPGAs, NPUs, and Neuromorphic Chips) • By Function (Inference and Training) • By Device (Consumer Devices, Enterprise Devices, and Industrial Devices) • By Process Node (14 nm and Above, 7 nm to 10 nm, and 5 nm and Below) • By End-Use Industry (Consumer Electronics, Automotive and Transportation, Smart Cities and Surveillance, Industrial, Healthcare, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | NVIDIA Corporation, Qualcomm Incorporated, Intel Corporation, Advanced Micro Devices, Inc., Apple Inc., MediaTek Inc., Alphabet Inc. (Google), Samsung Electronics Co., Ltd., Huawei Technologies Co., Ltd., Arm Holdings plc, STMicroelectronics N.V., NXP Semiconductors N.V., Texas Instruments Incorporated, Renesas Electronics Corporation, Hailo Technologies Ltd., BrainChip Holdings Ltd., SiMa.ai, Kneron, Inc., Syntiant Corp., Axelera AI |

Frequently Asked Questions
Key players include NVIDIA, Qualcomm, Intel, AMD, Apple, MediaTek, Google, Samsung, Huawei, Arm, STMicroelectronics, NXP, Hailo, BrainChip, SiMa.ai and Kneron.
Key opportunities include industrial and automotive AI, discrete accelerator modules, on-device generative AI and neuromorphic chips for ultra-low-power sensing.
The major growth factor is the shift of AI inference from the cloud to devices, driven by generative AI features, latency and privacy requirements, and falling cost of efficient neural processors.
By Chipset, the ASICs segment dominated the market with approximately 35.31% share in 2025, owing to high performance per watt and suitability for mass-produced devices.
North America dominated the market with a share of 38.64% in 2025, supported by leading chip designers, device brands and early adoption of on-device AI.
