
Electrolyzers Market Report Scope & Overview
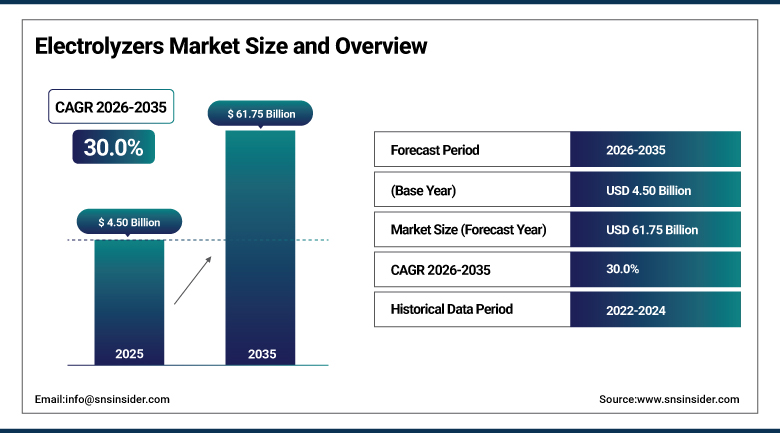
The Electrolyzers Market was valued at USD 4.50 billion in 2025 and is projected to reach USD 61.75 billion by 2035, expanding at a CAGR of 30.0% during the forecast period.
Electrolyzers split water into hydrogen and oxygen using electricity, forming the core production technology behind green hydrogen when powered by renewable electricity rather than grid power derived from fossil fuels. Global decarbonization commitments and investment in clean energy infrastructure continue to accelerate adoption, with alkaline electrolyzer technology retaining the lowest capital cost and longest operational track record of any water electrolysis technology, anchored by decades of chlor-alkali industry manufacturing legacy. Ammonia and fertilizer producers represent one of the largest current demand pools, as the sector seeks to shift away from grey hydrogen derived from natural gas toward renewable-powered electrolysis to meet increasingly binding industrial decarbonization targets.
Gigafactory-scale electrolyzer manufacturing consolidation is accelerating as leading suppliers scale production capacity toward hundreds of megawatts of annual output per facility, aiming to drive down per-unit capital costs through manufacturing learning curves similar to those observed in solar module and lithium-ion battery production. AI-driven predictive maintenance is increasingly integrated into large-scale electrolyzer installations, helping operators of giga-scale green hydrogen and green ammonia projects maximize uptime and stack lifespan across increasingly capital-intensive installations. Suppliers increasingly view total lifecycle cost, including stack replacement intervals and electricity conversion efficiency, as a more meaningful competitive differentiator than upfront capital cost alone, reshaping how large industrial customers evaluate competing technology proposals. This shift toward lifecycle-cost evaluation is also encouraging closer collaboration between electrolyzer suppliers and end customers on maintenance contracts, mirroring long-term service agreement models already established in the wind and solar industries.
In January 2025, the U.S. Treasury finalized the Inflation Reduction Act Section 45V Clean Hydrogen Production Tax Credit rules, locking in incentives of up to USD 3 per kilogram for qualifying projects under 4 kilograms of CO2-equivalent emissions per kilogram of hydrogen produced across a ten-year window, providing long-term policy certainty for U.S. electrolyzer project developers.
To Get more information Electrolyzers Market - Request Free Sample Report
Electrolyzers Market Trends
-
Rising gigafactory-scale manufacturing consolidation aimed at driving down electrolyzer capital costs
-
Growing adoption of PEM electrolyzer technology for its modular design and mobility application suitability
-
Increasing integration of AI-driven predictive maintenance across giga-scale green hydrogen installations
-
Rising deployment of electrolyzers for grid balancing and renewable energy curtailment mitigation
-
Growing interest in solid oxide electrolyzer cells for high-temperature industrial applications with waste heat integration
U.S. Electrolyzers Market Outlook
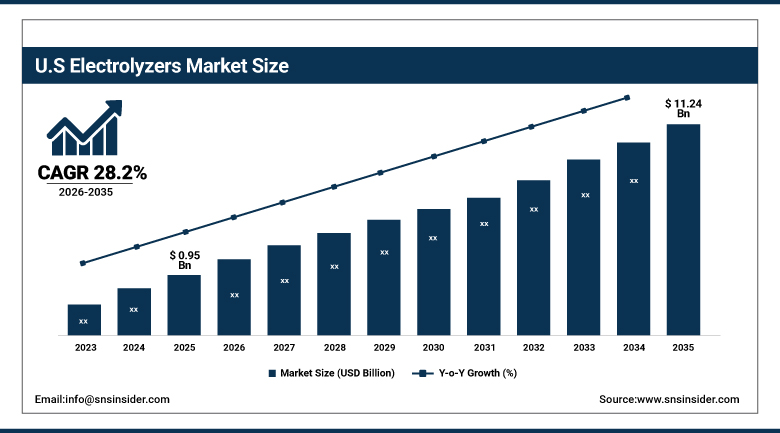
The U.S. electrolyzer market was valued at USD 0.95 billion in 2025 and is projected to reach USD 11.24 billion by 2035, growing at a CAGR of 28.2% during 2026-2035.
The U.S. market benefits from the Section 45V Clean Hydrogen Production Tax Credit and the Department of Energy's approximately USD 7 billion Regional Clean Hydrogen Hubs program, which together provide substantial project financing certainty for electrolyzer developers across ammonia, refining, and industrial decarbonization applications. Gulf Coast refining and chemical hubs represent a particularly strong demand concentration, given the sector's large existing hydrogen consumption base and relatively straightforward pathway to substitute grey hydrogen with electrolytic green hydrogen production.
Electrolyzer manufacturers from the United States are progressively increasing their local manufacturing capacity as a means of earning additional tax credits in domestic content bonus credits under the incentive structure offered by the government. This encourages the integration of manufacture of stacks and balance of plant components locally instead of importing them. Several American electrolyzer manufacturers have been increasing collaborations with American steel and specialty component manufacturers for the development of more robust supply chains for stack components.
Nel Hydrogen US, a subsidiary of Nel ASA, was awarded a purchase order of 2.5 MW containerized PEM electrolyzer unit for the Aberdeen Hydrogen Hub project in March 2025. This shows the increase in the international trade of electrolyzer equipment despite the increase in domestic manufacturing capacity in the United States.
Electrolyzers Market Segment Analysis
-
By Technology, the Alkaline segment dominated the Electrolyzers Market with approximately 52.4% share in 2025, while the Proton Exchange Membrane (PEM) segment is the fastest growing with a CAGR of approximately 38.6%.
-
By Capacity, the Above 2,000 kW segment dominated the Electrolyzers Market with approximately 44.8% share in 2025, while the 500-2,000 kW segment is the fastest growing with a CAGR of approximately 42.3%.
-
By Application, the Ammonia & Fertilizer segment dominated the Electrolyzers Market with approximately 26.9% share in 2025, while the Mobility & Transportation segment is the fastest growing with a CAGR of approximately 41.5%.
By Technology, Alkaline Dominates the Electrolyzers Market While Proton Exchange Membrane (PEM) Registers the Fastest Growth
Alkaline dominated the Electrolyzers Market in 2025 due to the fact that this technology offers the lowest capital cost and longest proven operational track record of any water electrolysis method, anchored by decades of chlor-alkali industry manufacturing experience that continues to support constant optimization for greater efficiency and lower production costs at massive scale.
Proton Exchange Membrane (PEM) is the fastest-growing segment in the Electrolyzers Market due to the fact that its modular design, high efficiency, and superior compatibility with variable renewable electricity input make it increasingly favored for mobility applications, including hydrogen fuel cell vehicle refueling, as well as distributed and grid-balancing installations. Ongoing research and development investment and improved stack durability continue to accelerate PEM manufacturing capacity expansion across Europe, North America, and Asia Pacific.
By Capacity, above 2,000 kW Dominates the Electrolyzers Market While 500-2,000 kW Registers the Fastest Growth
Above 2,000 kW dominated the Electrolyzers Market in 2025 due to the fact that giga-scale green hydrogen, green ammonia, and industrial decarbonization projects increasingly require continuous, high-volume hydrogen supply that only large-capacity electrolyzer installations can economically deliver. Large industrial sectors such as steel, refining, fertilizers, and synthetic fuels favor these installations given their superior cost efficiency at scale relative to multiple smaller distributed systems.
500-2,000 kW is the fastest-growing segment in the Electrolyzers Market due to the fact that this mid-range capacity band offers flexible integration with large renewable energy projects and moderate-volume industrial operations, including commercial hydrogen refueling stations, without the capital intensity and lengthy development timelines associated with giga-scale installations.
By Application, Ammonia & Fertilizer Dominates the Electrolyzers Market While Mobility & Transportation Registers the Fastest Growth
Ammonia & Fertilizer held the largest share of the Electrolyzers Market in 2025 owing to the need for high levels of hydrogen, which is used as the main raw material in the manufacture of ammonia, and conventional manufacturing has relied heavily on grey hydrogen generated using natural gas, thereby leading to high carbon emissions. Fertilizer makers and ammonia manufacturers are increasingly switching to green hydrogen generated through water electrolysis in an effort to reduce their emissions and conform to the decarbonization targets set globally.
The Mobility & Transportation is the fastest growing segment of the Electrolyzers Market since wide adoption of hydrogen fuel cell vehicles and increased investments in hydrogen refueling infrastructure have led to increased demand for electrolyzers installed at the refueling sites.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
77.0% |
|
Europe |
Germany |
31.0% |
|
Asia Pacific |
China |
46.0% |
|
Middle East & Africa |
Saudi Arabia |
36.0% |
|
Latin America |
Chile |
33.0% |
North America Electrolyzers Market Insights
North America's market continues to expand rapidly, anchored by the Section 45V Clean Hydrogen Production Tax Credit and the Department of Energy's Regional Clean Hydrogen Hubs program, which together provide substantial project financing certainty across ammonia, refining, and industrial decarbonization applications.
Canadian electrolyzer project development continues to expand in Quebec and Alberta, supported by low-cost hydroelectric and renewable electricity availability that improves green hydrogen production economics relative to regions reliant on more expensive renewable power.
Mexican industrial customers, particularly in the fertilizer and refining sectors, are beginning to evaluate electrolyzer investment as part of broader North American nearshoring and industrial decarbonization strategies tied to export market requirements.
Europe Electrolyzers Market Insights
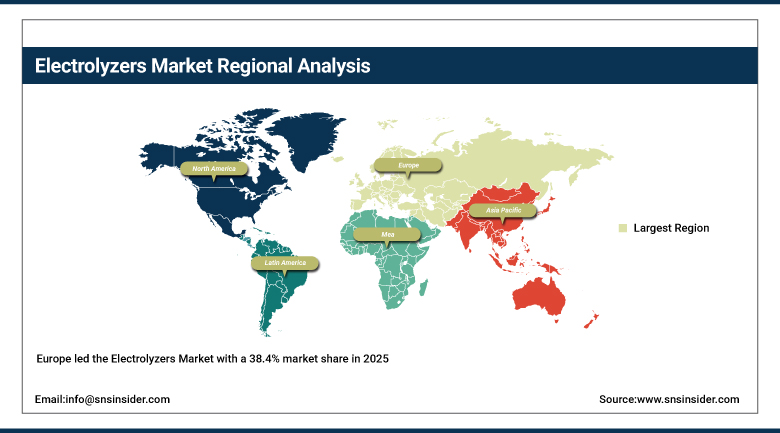
Europe led the Electrolyzers Market with a 38.4% market share in 2025 on account of massive investments made by various European countries to move towards a hydrogen economy within the context of the EU Green Deal and REPowerEU policy frameworks.
German, Netherlands, and Denmark remain the frontrunners in European electrolyzers manufacturing and installations owing to their robust hydrogen policies as well as huge funding from government sources to build gigafactory scale electrolyzers manufacturing in-country.
France and Spain electrolyzers manufacturing investment keeps growing along with Germany on account of their respective national hydrogen policies and EU funding initiatives for building a resilient European electrolyzers manufacturing industry that is less dependent on imports.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Electrolyzers Market Insights
Asia Pacific is the fastest-growing region in the Electrolyzers Market, led by China and India, where large-scale domestic electrolyzer manufacturing capacity expansion and aggressive government green hydrogen targets continue to drive rapid capacity additions ahead of other global regions.
China's electrolyzer manufacturers continue to scale production capacity aggressively, leveraging the country's existing renewable energy equipment manufacturing base to offer increasingly cost-competitive alkaline and PEM systems for both domestic deployment and growing export markets.
Middle East & Africa and Latin America Electrolyzers Market Insights
The Middle East & Africa region is growing steadily thanks to continued development of green hydrogen mega-projects in Gulf states such as Saudi Arabia and Oman, backed up by the outstanding availability of low-cost solar and wind resources in the region. Oman and UAE are moving forward with their green hydrogen/ammonia export projects, making use of the outstanding renewable energy resource availability as well as strategic port infrastructure positioning in order to serve the future hydrogen import demand from Asia and Europe.
Latin America is developing steadily, as Chile continues to move forward with its green hydrogen project developers, which make use of the excellent solar and wind resource availability in the country, in order to deploy electrolyzers that will support not only local decarbonization but also future exports to Asia and Europe. The green hydrogen project developers in Brazil, which are concentrated in wind rich areas of the country, are also advancing electrolyzer deployment in order to serve the same purposes.
Market Dynamics
Growth Drivers: Government tax incentives and industrial decarbonization mandates fueling adoption
Expanding government clean hydrogen production tax credit and subsidy programs, including the U.S. Section 45V credit and the EU's hydrogen bank funding mechanisms, continue to provide the project financing certainty needed to move large-scale electrolyzer installations from planning to final investment decision.
Growing industrial decarbonization mandates across ammonia, steel, and refining sectors are driving structural demand for green hydrogen as a direct substitute for grey hydrogen derived from fossil fuel feedstocks, creating durable, policy-reinforced demand independent of broader energy market cycles.
Continued declines in renewable electricity generation costs are improving green hydrogen production economics, narrowing the cost gap with grey hydrogen and strengthening the business case for electrolyzer investment across an expanding range of industrial applications.
Rising gigafactory-scale manufacturing consolidation among leading electrolyzer suppliers is driving down per-unit capital costs through manufacturing learning curve effects, further improving project economics and accelerating capacity additions across all major technology types.
Growing corporate procurement of green hydrogen through long-term offtake agreements is providing electrolyzer project developers with the revenue certainty needed to secure project financing, particularly among industrial customers with binding corporate decarbonization commitments extending to their process heat and feedstock emissions.
Restraints: High capital costs and renewable electricity availability constraining project economics
Even with cost reduction, electrolyzer capital expenditures and renewable electricity needed to fuel the electrolyzers remain more expensive compared to fossil fuel-based grey hydrogen, thus restricting any economic returns in the short term only to projects that are either subsidized directly or priced as green products.
The lack of adequate and affordable supply of renewable electricity in certain geographic locations poses a limitation to the projects since their economics largely rely on having access to long-term and low-cost renewable power purchase agreements, which are not always available everywhere.
Extended project development and permitting lead times of several years for electrolyzer projects pose financing risks and can deter investment in case of uncertain regulatory or political environments.
Supply chain limitations in the global market for specific electrolyzer parts such as iridium catalysts used for PEM electrolysis pose cost limitations and can limit scaling up of manufacturing despite increasing demand.
Opportunities: Mobility refueling expansion and manufacturing gigafactory scale-up widening addressable demand
Rapid expansion of hydrogen fuel cell vehicle adoption and refueling infrastructure investment presents a substantial growth opportunity for PEM electrolyzer suppliers, given the technology's modular footprint and rapid response capability well-suited to distributed refueling station deployment.
Continued gigafactory-scale manufacturing capacity expansion presents an opportunity for leading suppliers to capture disproportionate market share as manufacturing learning curve cost declines increasingly favor large-scale, vertically integrated producers over smaller manufacturers.
Growing green hydrogen export corridor development between low-cost renewable resource regions, including Chile, Australia, and the Middle East, and hydrogen-importing markets in Europe and Asia presents a significant long-term opportunity for electrolyzer suppliers serving large-scale export-oriented project pipelines.
Growing interest in solid oxide electrolyzer cell technology for high-temperature industrial applications capable of utilizing waste heat presents a significant efficiency opportunity for manufacturers able to commercialize this technology at scale for steel and cement industry decarbonization applications.
Recent Developments
-
In May 2025, ITM Power plc signed an agreement to supply over 300 MW of electrolyzers for a green hydrogen power plant project in the Asia Pacific region.
-
In January 2026, thyssenkrupp nucera partnered with Deutsche Gesellschaft für Internationale Zusammenarbeit to advance green hydrogen and Power-to-X market development in India, supporting electrolyzer deployment across the region.
-
In 2024, Siemens Energy expanded its electrolyzer gigafactory manufacturing capacity in Germany, targeting annual production scale-up to support growing European green hydrogen project demand.
-
In 2024, Accelera by Cummins announced expanded PEM electrolyzer manufacturing capacity in North America, aimed at scaling toward hundreds of megawatts of annual production output.
-
In 2024, Plug Power Inc. expanded its PEM electrolyzer manufacturing capacity in New York, targeting growing North American green hydrogen project demand across ammonia and industrial gas applications.
Electrolyzers Market key players are:
-
thyssenkrupp nucera
-
Siemens Energy AG
-
Nel ASA
-
ITM Power plc
-
Air Liquide S.A.
-
Air Products and Chemicals Inc.
-
Linde plc
-
Cummins Inc. (Accelera)
-
McPhy Energy S.A.
-
Toshiba Corporation
-
Asahi Kasei Corporation
-
LONGi Green Energy
-
Next Hydrogen Solutions
-
Elogen (Gaztransport & Technigaz)
-
Sunfire GmbH
-
Plug Power Inc.
-
Ohmium International
-
John Cockerill
-
HydrogenPro AS
-
Green Hydrogen Systems A/S
Electrolyzers Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.50 Billion |
| Market Size by 2035 | USD 61.75 Billion |
| CAGR | CAGR of 30.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Alkaline, Proton Exchange Membrane (PEM), Solid Oxide, Anion Exchange Membrane (AEM)) • By Capacity (Below 500 kW, 500–2,000 kW, Above 2,000 kW) • By Application (Ammonia & Fertilizer, Power Generation & Grid Balancing, Mobility & Transportation, Refining & Chemicals) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | thyssenkrupp nucera, Siemens Energy AG, Nel ASA, ITM Power plc, Air Liquide S.A., Air Products and Chemicals Inc., Linde plc, Cummins Inc. (Accelera), McPhy Energy S.A., Toshiba Corporation, Asahi Kasei Corporation, LONGi Green Energy, Next Hydrogen Solutions, Elogen (Gaztransport & Technigaz), Sunfire GmbH, Plug Power Inc., Ohmium International, John Cockerill, HydrogenPro AS, Green Hydrogen Systems A/S |

Frequently Asked Questions
Leading companies include thyssenkrupp nucera, Siemens Energy AG, Nel ASA, ITM Power plc, and Air Liquide S.A., among other major industrial gas conglomerates and specialized electrolyzer manufacturers.
Opportunities include rapid expansion of hydrogen fuel cell vehicle refueling infrastructure, continued gigafactory-scale manufacturing capacity expansion, and growing green hydrogen export corridor development between low-cost renewable resource regions and hydrogen-importing markets.
Growth is driven by expanding government clean hydrogen production tax credit programs, growing industrial decarbonization mandates across ammonia, steel, and refining sectors, and continued declines in renewable electricity generation costs.
Alkaline dominates by technology with approximately 52.4% share, Above 2,000 kW dominates by capacity with roughly 44.8% share, and Ammonia & Fertilizer dominates by application with about 26.9% share; PEM, 500-2,000 kW, and Mobility & Transportation are the fastest-growing segments within their respective categories.
Europe is the largest regional market with approximately 38.4% share, led by Germany, while Asia Pacific, led by China, is the fastest-growing region through 2035.
