
Electronic Grade Solvents Market Report Scope & Overview:
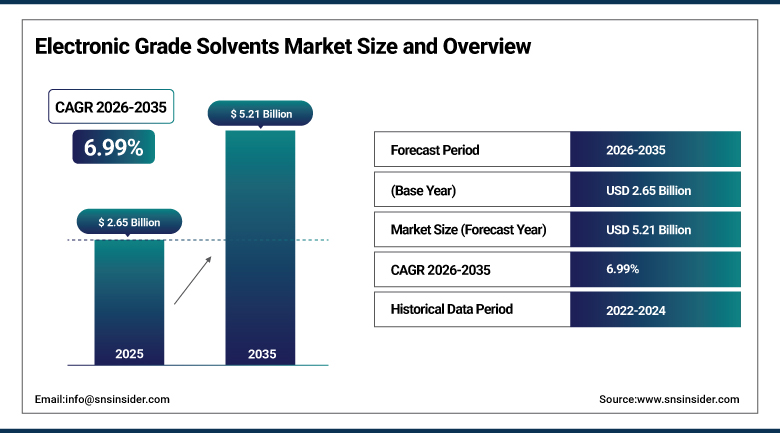
The Electronic Grade Solvents Market size was valued at USD 2.65 Billion in 2025 and is expected to reach USD 5.21 Billion by 2035, growing at a CAGR of 6.99% from 2026-2035.
The Electronic Grade Solvents Market is expanding at a steady pace as semiconductor, display, and solar manufacturers commit record capital to new fabrication capacity and as advancing process nodes demand cleaner, more tightly specified chemistry. Growth is anchored by the rising number of cleaning and lithography steps per wafer, the migration toward parts-per-trillion purity, and government incentive programs that are relocating fabrication capacity into North America, Europe, and India. Isopropyl alcohol leads by volume, while photolithography-grade formulations are gaining momentum with the spread of extreme ultraviolet patterning. Suppliers are investing in regional purification, ultra-clean packaging, and recycling capability to secure long-term contracts with leading chipmakers, and Asia Pacific remains the largest region while North America is the fastest growing region.
⮞Supplier strategy is shifting toward vertical integration, a trend underscored when ExxonMobil announced in April 2026 that it would upgrade its Baton Rouge, Louisiana, plant, described by the company as the world's largest isopropyl alcohol facility, to produce 99.999% ultra-pure isopropyl alcohol for chip manufacturing, with production scheduled to begin in 2027.
To Get more information Electronic Grade Solvents Market - Request Free Sample Report
Electronic Grade Solvents Market Trends
-
Parts-per-trillion purity specifications are spreading from leading-edge logic into memory and advanced packaging lines.
-
Petrochemical majors are entering electronic-grade production to integrate feedstock with ultra-pure purification.
-
Fabrication investment in Arizona, Texas, Japan, and India is driving regional solvent purification and bottling capacity.
-
Photoresist thinners and edge bead removers are gaining volume as extreme ultraviolet and multi-patterning layers increase.
-
Closed-loop solvent recovery and reclaimed electronic-grade products are attracting fabs with sustainability targets.
-
High-efficiency solar cell architectures are moving from technical-grade to electronic-grade cleaning solvents.
U.S. Electronic Grade Solvents Market Outlook
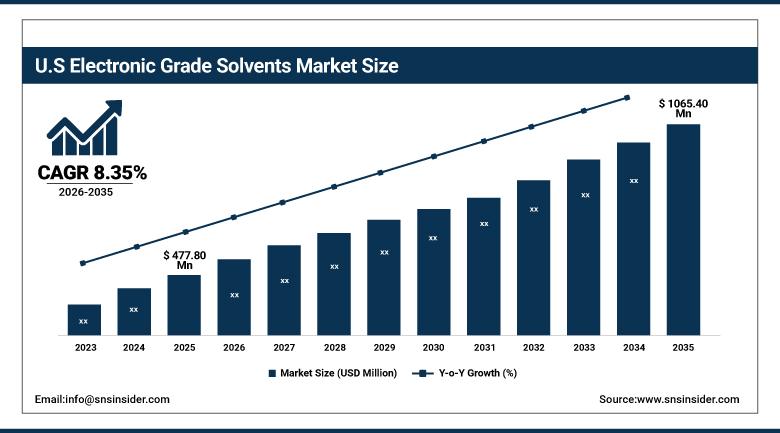
The U.S. Electronic Grade Solvents Market was valued at approximately USD 477.80 Million in 2025 and is expected to reach approximately USD 1065.40 Million by 2035, growing at a CAGR of approximately 8.35%.
The U.S. Electronic Grade Solvents Market growth continues to be reinforced by the largest wave of fabrication investment in the country in decades, with Intel, TSMC, Samsung, Micron, and GlobalFoundries building or expanding facilities in Arizona, Texas, New York, Idaho, and Ohio under federal incentive programs. Each new fab requires a dependable local supply of isopropyl alcohol, acetone, and photolithography solvents, and chipmakers are signing multi-year agreements that include on-site blending, container return, and in-line quality monitoring. Advanced packaging expansion and the build-out of artificial intelligence accelerator production add further demand, while rising interest in reclaimed solvent services reflects waste-reduction goals. Suppliers with regional purification assets are therefore winning preference over imported material. Federal and state workforce programs complement these projects.
⮞Supplier localization is gathering pace, as shown when South Korea's Dongjin Semichem confirmed in February 2025 an investment of more than $110 million at its Killeen, Texas, site to produce ultra-high-purity photoresist thinner for semiconductor photolithography, creating 24 jobs. The project places a leading Asian materials specialist within reach of Texas fabrication customers and signals that qualified suppliers regard North America as a durable long-term market rather than an export destination. Photoresist thinner is consumed in each lithography cell, so proximity to customers reduces lead times and simplifies the lot-by-lot certification that fabs require before releasing material into production.
Electronic Grade Solvents Market Segment Analysis
-
By Type, the Isopropyl Alcohol segment dominated the Electronic Grade Solvents Market with approximately 38.46% share in 2025, while the Propylene Glycol Monomethyl Ether Acetate segment is the fastest growing with a CAGR of approximately 8.72%.
-
By Purity Grade, the Parts-per-Billion Grade segment dominated the Electronic Grade Solvents Market with approximately 61.28% share in 2025, while the Parts-per-Trillion Grade segment is the fastest growing with a CAGR of approximately 9.41%.
-
By Application, the Wafer Cleaning segment dominated the Electronic Grade Solvents Market with approximately 43.17% share in 2025, while the Photolithography segment is the fastest growing with a CAGR of approximately 8.06%.
-
By End Use, the Semiconductors segment dominated the Electronic Grade Solvents Market with approximately 71.54% share in 2025, while the Solar Photovoltaics segment is the fastest growing with a CAGR of approximately 8.19%.
By Type, isopropyl alcohol dominates, propylene glycol monomethyl ether acetate grows fastest
Isopropyl alcohol remains the leading solvent type, characterized by its dual role in wafer rinsing and drying, where low surface tension and rapid evaporation leave minimal residue on patterned silicon. Fabs running advanced logic and memory lines consume it at nearly every cleaning step, from post-etch residue removal to the final Marangoni drying stage, and multi-year qualification cycles with chipmakers create durable supply relationships. Large petrochemical producers with propylene-based integration hold a cost advantage, while dedicated electronic-grade purification lines convert commodity output into material with metal contamination measured in parts per trillion. This breadth of process relevance and entrenched qualification keeps the segment at the center of solvent procurement.
Propylene glycol monomethyl ether acetate is emerging as the fastest growing solvent type, driven by the expansion of photolithography steps in leading-edge manufacturing. Each additional lithography layer in extreme ultraviolet and multi-patterning flows increases consumption of photoresist thinners, edge bead removers, and developer-adjacent solvents built around this chemistry. Memory makers adding high-layer-count three-dimensional NAND and advanced packaging lines are widening demand further. The segment also benefits from tightening metal-ion and moisture specifications, which favor suppliers able to deliver consistent lot-to-lot purity at scale. Regional producers in Japan, South Korea, and Taiwan are adding dedicated distillation capacity, positioning this chemistry as the principal growth vector within the broader solvent portfolio.
By Purity Grade, parts-per-billion grade dominates, parts-per-trillion grade grows fastest
Parts-per-billion grade material dominates the purity landscape, characterized by its suitability for the large installed base of mature and mid-range fabrication lines that still account for most wafer starts worldwide. Automotive, industrial, power, and analog devices manufactured on 28 nanometer and larger nodes tolerate impurity thresholds that this grade satisfies, which keeps procurement economics attractive for fabs operating under tight cost discipline. Established distillation and sub-micron filtration infrastructure allows suppliers to serve a wide customer base. Demand from display panel and photovoltaic cell manufacturers, which also rely on this grade for cleaning and stripping, adds further volume and reinforces its position as the commercial workhorse of the purity hierarchy.
Parts-per-trillion grade is the fastest growing purity tier, reflecting the migration of chip production to sub-5 nanometer geometries where a single metallic or particulate contaminant can destroy a die. Leading foundries and memory manufacturers are qualifying tighter specifications with each node transition, and suppliers are responding with advanced purification, ultra-clean packaging, and in-line metrology that verifies contamination at the point of delivery. Investment in new fabrication capacity across Taiwan, South Korea, Arizona, and Japan is directing premium solvent volumes toward this tier. Pricing power is stronger than in lower grades, rewarding producers that have committed capital to cleanroom bottling, specialized container programs, and batch traceability for the most demanding customers.
By Application, wafer cleaning dominates, photolithography grows fastest
Wafer cleaning leads the application landscape, supported by the repeated cleaning cycles that a modern chip undergoes between deposition, etching, and planarization steps. A single advanced wafer can pass through dozens of rinse and dry operations, and each one consumes high-purity solvent in volumes that scale directly with fab throughput. Single-wafer spin processors, batch immersion tools, and post-chemical-mechanical-planarization cleaners all depend on consistent solvent quality to protect yield. Rising layer counts and the introduction of new materials such as cobalt, ruthenium, and high-k dielectrics complicate residue profiles, which increases both the frequency and the technical sophistication of cleaning sequences and sustains steady, recurring consumption across the fab base.
Photolithography is the fastest growing application, propelled by the increasing number of patterning layers required in advanced logic, high-bandwidth memory, and chiplet architectures. Extreme ultraviolet exposure and multi-patterning schemes rely on formulated thinners, rinses, and edge bead removers that must meet strict contamination limits to avoid defects in resist films only a few tens of nanometers thick. Fab expansions in East Asia and North America are adding lithography cells at pace, and photoresist suppliers continue to launch new formulations that require matched solvent systems. As patterning complexity rises faster than wafer volume, solvent consumption per wafer in this application climbs, lifting its growth profile above the broader average.
By End Use, semiconductors dominate, solar photovoltaics grows fastest
Semiconductor manufacturing dominates the end use landscape, anchored by the purity requirements of wafer fabrication and the sheer scale of global capital investment in new foundry and memory capacity. Government incentive programs in the United States, Europe, Japan, South Korea, and India are accelerating fab construction, and every new facility carries a long-term solvent supply requirement that is contracted years in advance. Artificial intelligence accelerators, high-bandwidth memory, and advanced packaging add process steps that multiply solvent use per finished device. Suppliers with local purification and distribution infrastructure near major fab clusters therefore command an advantage, and the segment continues to account for the overwhelming majority of premium solvent consumption.
Solar photovoltaics is the fastest growing end use, supported by capacity additions in high-efficiency cell architectures such as tunnel oxide passivated contact and heterojunction technology. These designs require cleaner surfaces than earlier passivated emitter cells, and manufacturers are consequently moving from technical-grade to electronic-grade solvents for texturing rinses, wafer cleaning, and paste removal steps. Cell producers in China, India, Southeast Asia, and increasingly the United States are building gigawatt-scale lines under domestic manufacturing incentives. Although per-unit solvent intensity is lower than in semiconductors, the volume of wafers processed is very large, which gives the end use a faster expansion rate and widens the electronic-grade customer base.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
79.43% |
|
Europe |
Germany |
31.58% |
|
Asia Pacific |
China |
34.72% |
|
Latin America |
Brazil |
46.12% |
|
Middle East & Africa |
Israel |
38.26% |
North America Electronic Grade Solvents Market Insights
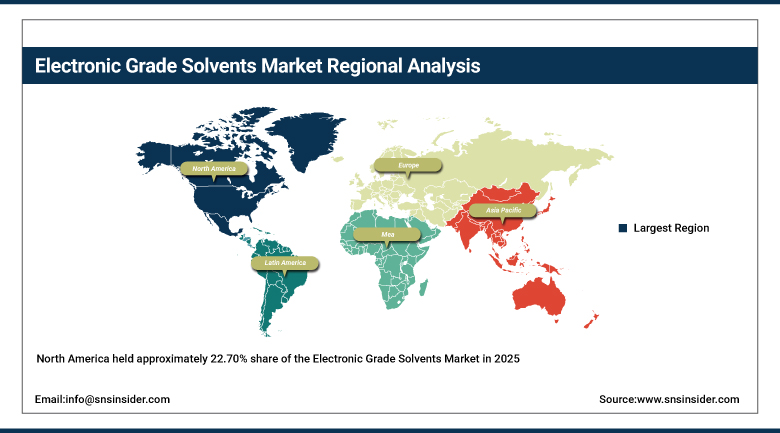
North America held approximately 22.70% share of the Electronic Grade Solvents Market in 2025 and is the fastest growing region, expanding at a CAGR of 8.35% during 2026-2035. The expansion follows large-scale fab commitments in Arizona, Texas, New York, and Ohio by Intel, TSMC, Samsung, Micron, and GlobalFoundries, all of which require locally available high-purity chemistry to reduce logistics risk and contamination exposure. Supplier responses have been immediate: ExxonMobil is upgrading Baton Rouge for ultra-pure isopropyl alcohol, Dongjin Semichem is building in Killeen, and Entegris has enlarged purification capacity in Colorado and California. Federal incentives under the CHIPS and Science Act continue to anchor the investment pipeline.
The United States accounts for the substantial majority of regional demand, while Canada and Mexico contribute through specialty chemical distribution, packaging operations, and emerging backend assembly activity. Arizona has become the focal point for electronic chemical logistics, with dedicated storage, bulk delivery, and recycling infrastructure developing around the Phoenix fab corridor. Chipmakers increasingly prefer supply agreements that include on-site blending, container return programs, and in-line quality monitoring, which favors suppliers willing to commit capital near customer sites. Workforce availability and permitting timelines remain variables, yet the long-term trajectory is upward as the United States seeks a more balanced share of global semiconductor output and a shorter materials supply chain.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Electronic Grade Solvents Market Insights
Europe represents a mature but strategically important market, supported by established semiconductor clusters in Germany, France, the Netherlands, Italy, and Ireland, and by the European Chips Act objective of expanding regional manufacturing capacity. Infineon, STMicroelectronics, NXP Semiconductors, and GlobalFoundries operate substantial fabrication lines focused on power electronics, automotive, and industrial devices, which rely heavily on parts-per-billion grade solvents. Intel's planned Magdeburg investment and the Dresden cluster, including the European Semiconductor Manufacturing Company joint venture, point toward additional demand. Regional suppliers including Merck, BASF, and Solvay maintain deep technical relationships with these customers and invest steadily in purification capability and environmental compliance programs.
Germany leads regional consumption through the Dresden and Saxony ecosystem, often described as Silicon Saxony, while France and Italy contribute through power semiconductor and sensor production. The Netherlands benefits from the presence of ASML and its extensive lithography supply chain, which sustains demand for photolithography solvents. Environmental regulation, including the REACH framework and solvent emission controls, raises compliance costs and encourages investment in recycling and closed-loop recovery systems. These requirements also create opportunities for suppliers offering reclaimed electronic-grade solvents, a segment gaining relevance as fabs seek to reduce waste volumes and carbon footprints while preserving the stringent purity levels needed for production.
Asia Pacific Electronic Grade Solvents Market Insights
Asia Pacific dominated the Electronic Grade Solvents Market in 2025 with approximately 54.20% share, reflecting the concentration of the world's wafer fabrication, display manufacturing, and photovoltaic cell production in Taiwan, South Korea, China, and Japan. Taiwan Semiconductor Manufacturing Company, Samsung Electronics, SK hynix, and a deep network of outsourced foundries generate continuous demand for ultra-clean solvents, and local suppliers such as Tokuyama, Kanto Chemical, and Soulbrain have built purification plants adjacent to major fab clusters. Regional growth is expected at a CAGR of 6.84% during 2026-2035, as new fabs, packaging lines, and domestic substitution programs add volume steadily over the decade.
Within the region, Taiwan and South Korea anchor premium-grade consumption, supported by leading-edge logic and memory production that demands parts-per-trillion material, while Japan contributes advanced photoresist and solvent formulation expertise that supplies fabs worldwide. China is pursuing localization of electronic chemicals under national self-sufficiency policy, and domestic purifiers are qualifying products with SMIC, YMTC, and CXMT, gradually raising the share of regionally produced material. India has begun to emerge as a future demand center, with approved fabrication and assembly projects in Gujarat and Assam expected to create new procurement channels. The depth of integrated supply chains makes the region both the largest consumer and the principal production base.
MEA & Latin America Electronic Grade Solvents Market Insights
The Middle East and Africa remain a small but developing market, with demand concentrated in Israel, where Intel, Tower Semiconductor, and a vibrant design and fabrication ecosystem consume high-purity chemicals, and in Gulf economies exploring semiconductor and solar manufacturing as part of industrial diversification. Saudi Arabia and the United Arab Emirates have announced programs to build advanced electronics and renewable energy supply chains, which could create future procurement for electronic-grade materials. Petrochemical producers in the region hold feedstock advantages in isopropanol and acetone, creating a plausible path toward local purification and export once downstream customers establish a presence. Solar module assembly in the Gulf also offers an early entry point.
Latin America is a nascent market led by Brazil and Mexico, where electronics assembly, display module production, and early-stage semiconductor packaging generate modest but growing solvent requirements. Brazil's incentive framework for semiconductor and display production has attracted new assembly and test investments, while Mexico benefits from nearshoring trends that bring electronics manufacturing closer to North American customers. Most electronic-grade solvents are imported through distributors, which exposes buyers to longer lead times and price volatility. Local blending and repackaging operations are therefore a gradual opportunity, and regional demand is expected to follow the pace of backend semiconductor and photovoltaic module investment across the decade ahead.
Market Dynamics
Growth Drivers: Fabrication capacity expansion and rising process complexity
Capital investment in semiconductor fabrication is the dominant driver of solvent demand, with foundries and memory manufacturers committing hundreds of billions of dollars to new capacity across Asia, North America, and Europe. Each new fabrication facility carries a multi-decade consumption profile for cleaning, rinsing, and lithography solvents, and purchasing teams increasingly sign long-term supply agreements to secure material ahead of ramp. Government incentive packages in the United States, Japan, South Korea, India, and the European Union further improve project economics and accelerate construction schedules. As these facilities reach volume production, procurement shifts from qualification samples to continuous bulk delivery, creating a stable revenue base for qualified solvent producers.
Technology transitions inside existing fabs also lift consumption, as extreme ultraviolet lithography, gate-all-around transistors, three-dimensional memory stacking, and advanced packaging add process steps and tighten contamination limits. Artificial intelligence workloads are stimulating demand for large accelerator dies and high-bandwidth memory, both of which require complex multi-layer fabrication. Greater process complexity translates into higher solvent volume per wafer and a migration toward higher-purity grades with superior pricing. Suppliers that invest in metrology, ultra-clean packaging, and rapid technical support gain a durable advantage, as customers value reliability and traceability far more than marginal price differences when yield and uptime are at stake.
In 2026, Soulbrain announced an investment of more than $120 million in Taylor, Texas, for a high-purity phosphoric acid plant with annual capacity of 28,800 metric tons, which will also serve as its U.S. headquarters. The project positions a leading Korean materials supplier close to Texas fabrication clusters.
Restraints: Feedstock volatility and stringent regulation
Feedstock price volatility represents a significant restraint, since electronic-grade solvents are derived from propylene, methanol, and other petrochemical intermediates whose costs fluctuate with energy markets and refinery operating rates. Purification adds further cost through energy-intensive multi-stage distillation, specialized filtration, and ultra-clean packaging, which compress margins when upstream prices rise. Smaller producers lack the integration to absorb these swings and often depend on contract pass-through mechanisms that lag actual cost changes. Supply interruptions at a single large producer can also tighten regional availability, as demonstrated during previous logistics disruptions, which encourages chipmakers to demand safety stock and dual sourcing that raise working capital requirements across the supply chain.
Stringent regulation and long qualification cycles add to the restraints. Handling flammable solvents requires specialized storage, transport, and emission controls, and environmental rules governing volatile organic compounds and certain solvents such as N-methyl-2-pyrrolidone continue to tighten in Europe and North America. New entrants face lengthy qualification, frequently extending twelve to twenty-four months with major fabs, before commercial volumes begin. This protects incumbents but slows capacity responsiveness when demand rises quickly. In addition, the capital intensity of building ultra-high-purity plants and the shortage of skilled process engineers can delay projects and limit how rapidly supply expands to match fab construction schedules.
Opportunities: Supply chain regionalization and solvent recycling
There is a huge potential in regionalizing semiconductor supply chains, as the need for locally sourced chemicals arises from chip manufacturers to minimize logistics and geopolitics. The upcoming fabs in Arizona, Texas, Ohio, Japan, India, and Germany will need the capability of purification, bottling, and distributing in the region, creating an opportunity for companies willing to invest in or purchase assets in the region. The news from ExxonMobil, Dongjin Semichem, Tokuyama, and Soulbrain indicate the strategic planning by producers before the demand arises. Through joint ventures with local players, qualification can be sped up as well as market penetration, while offtake agreements with fab foundries will de-risk investment and fund ultra-high-purity production lines of isopropyl alcohol and photoresist thinners.
Recycling and reclamation represent a second opportunity, particularly as fabs set ambitious sustainability targets and face rising disposal costs. Recovery of used isopropyl alcohol, acetone, and other solvents through advanced distillation and purification can return material to electronic-grade specification at lower carbon intensity than virgin production. Suppliers offering closed-loop services, on-site recovery systems, and certified reclaimed products can differentiate themselves while helping customers meet environmental commitments. Emerging applications in advanced packaging, silicon carbide and gallium nitride power devices, and perovskite solar cells also broaden the addressable market, creating additional pathways for premium formulations beyond the established wafer fabrication base. Pilot programs with leading foundries are already under way.
Recent Developments:
-
2026: Tokuyama Corporation approved construction of a second high-purity isopropyl alcohol plant at the Kaohsiung site of its Formosa Tokuyama Advanced Chemicals joint venture in Taiwan, with a capacity of 30,000 metric tons per year and commercial operations scheduled for September 2028. The addition strengthens regional supply for Taiwanese foundries running leading-edge production.
-
2025: Solvay opened an expansion of its Zhenjiang, China, facility that doubles annual output of electronic-grade hydrogen peroxide marketed under the INTEROX Pico range for wafer cleaning and etching. Although a wet chemical rather than a solvent, the product is sold to the same fab purchasing teams and reflects rising purification investment in China.
-
2025: BASF disclosed an investment in the high double-digit million-euro range to expand ultra-pure, semiconductor-grade sulfuric acid production at its Ludwigshafen site in Germany, with operations expected to start by 2027. The move supports European chip manufacturing ambitions under regional supply chain policy.
-
2023: Entegris announced a $50 million capacity expansion for its high-purity electronic chemicals business, covering purification of acids, bases, and solvents at facilities in Pueblo, Colorado, and Hollister, California. The investment was designed to serve anticipated growth in North American fabrication.
-
2022: Kanto Group, together with Chemtrade Logistics, announced KPCT Advanced Chemicals, a joint venture planning a $200 million electronic-grade sulfuric acid plant of 100,000 metric tons per year in Casa Grande, Arizona. The facility brings Japanese and Taiwanese purification expertise into the Arizona fab corridor.
Electronic Grade Solvents Companies are:
-
BASF SE
-
Merck KGaA
-
Honeywell International Inc.
-
Mitsubishi Chemical Group Corporation
-
FUJIFILM Wako Pure Chemical Corporation
-
Kanto Chemical Co., Inc.
-
Entegris, Inc.
-
Dow Inc.
-
Eastman Chemical Company
-
ExxonMobil Corporation
-
Chang Chun Group
-
Soulbrain Co., Ltd.
-
Dongjin Semichem Co., Ltd.
-
Technic Inc.
-
Stella Chemifa Corporation
-
Sumitomo Chemical Co., Ltd.
-
Solvay SA
-
LCY Chemical Corp.
Electronic Grade Solvents Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.65 Billion |
| Market Size by 2035 | USD 5.21 Billion |
| CAGR | CAGR of 6.99% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Isopropyl Alcohol, Acetone, Propylene Glycol Monomethyl Ether Acetate, N-Methyl-2-Pyrrolidone, Others) • By Purity Grade (Parts-per-Billion Grade, Parts-per-Trillion Grade) • By Application (Wafer Cleaning, Photolithography, Etching and Stripping, Others) • By End Use (Semiconductors, Displays, Solar Photovoltaics, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Avantor, Inc., BASF SE, Merck KGaA, Honeywell International Inc., Mitsubishi Chemical Group Corporation, FUJIFILM Wako Pure Chemical Corporation, Kanto Chemical Co., Inc., Tokuyama Corporation, Entegris, Inc., Dow Inc., Eastman Chemical Company, ExxonMobil Corporation, Chang Chun Group, Soulbrain Co., Ltd., Dongjin Semichem Co., Ltd., Technic Inc., Stella Chemifa Corporation, Sumitomo Chemical Co., Ltd., Solvay SA, LCY Chemical Corp. |

Frequently Asked Questions
Key players in the Electronic Grade Solvents Market include Avantor, Inc., BASF SE, Merck KGaA, Honeywell International Inc., Mitsubishi Chemical Group Corporation, Tokuyama Corporation, Entegris, Inc., and ExxonMobil Corporation, among others.
Key opportunities include regionalization of semiconductor supply chains, which requires new local purification and bottling capacity, along with solvent recycling services, advanced packaging chemistry, and expanding demand from high-efficiency solar cell manufacturing.
The market is driven by record investment in semiconductor fabrication capacity and by rising process complexity, which increases both the number of cleaning and lithography steps per wafer and the purity grade of solvents required.
The Isopropyl Alcohol segment dominated the Electronic Grade Solvents Market in 2025 with approximately 38.46% share, supported by its use in wafer rinsing and drying across logic, memory, and display fabrication.
Asia Pacific dominated the Electronic Grade Solvents Market in 2025 with approximately 54.20% share, supported by the concentration of wafer, display, and photovoltaic production in Taiwan, South Korea, China, and Japan.
