
Semiconductor Chemicals Market Report Scope & Overview:
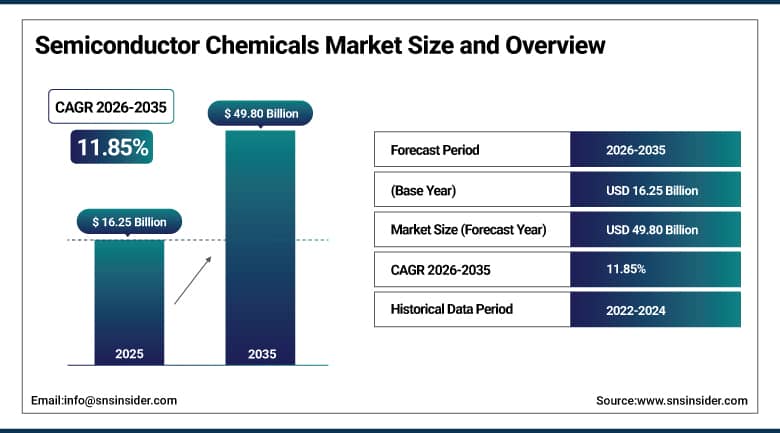
The Semiconductor Chemicals Market was valued at USD 16.25 Billion in 2025 and is expected to reach USD 49.80 Billion by 2035, growing at a CAGR of 11.85% from 2026-2035.
The Semiconductor Chemicals Market is expected to grow due to rising demand for advanced semiconductors used in artificial intelligence (AI), high-performance computing, 5G networks, electric vehicles, and Internet of Things (IoT) devices. Continuous semiconductor miniaturization and advanced manufacturing processes are increasing the need for ultra-high-purity chemicals used in wafer cleaning, photolithography, etching, deposition, and chemical mechanical planarization. Additionally, expanding semiconductor fabrication facilities, government initiatives supporting domestic chip production, and growing investments in advanced packaging are boosting chemical consumption. Increasing requirements for improved chip performance, manufacturing precision, and production yields will further support market expansion throughout the forecast period.
⮞In February 2026, SEMI reported that global silicon wafer shipments reached 12,973 million square inches during 2025. Each wafer passes through repeated cleaning, patterning and etching steps, so rising wafer area translates directly into higher process chemical volumes.
To Get More Information On Semiconductor Chemicals Market - Request Free Sample Report
Semiconductor Chemicals Market Trends
-
Chemical intensity per wafer is rising as advanced nodes, 3D architectures and advanced packaging add process steps.
-
Suppliers are localizing production near fabs in the U.S., South Korea, Taiwan and Japan to shorten qualification and delivery cycles.
-
Green chemistry is gaining ground through PFAS substitution, biodegradable photoresists and water-based processes.
-
EUV and metal oxide resists are driving new photoresist inputs and photoacid generator capacity.
-
Industrial gas suppliers are building on-site ultra-pure gas plants tied to AI memory and foundry fabs.
U.S. Semiconductor Chemicals Market Outlook
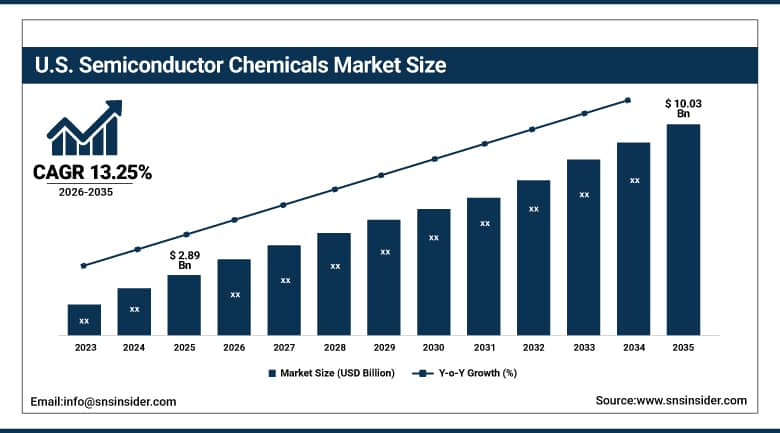
The U.S. Semiconductor Chemicals Market was valued at USD 2.89 Billion in 2025 and is expected to reach USD 10.03 Billion by 2035, growing at a CAGR of 13.25% from 2026-2035.
The U.S. Semiconductor Chemicals Market is shifting from reliance on overseas supply toward local production. New leading edge fabs in Arizona, Texas and other states need ultra pure acids, solvents and gases delivered under strict impurity limits. Chemical makers are therefore building plants beside these sites. The market is estimated at USD 3.27 Billion in 2026 and is on course for USD 10.03 Billion by 2035. Federal chip incentives support fab construction and the supplier base around it. Customers favor vendors that qualify quickly and hold stock close to the line. Advanced packaging growth adds further demand for cleans, plating and etch chemistries.
⮞In August 2025, Entegris announced USD 700.00 Million in research and development spending in the United States, centered on a technology center in Aurora, Illinois. The program spans deposition materials, slurries, cleans and CMP pads, which deepens the local innovation base for process chemicals.
Semiconductor Chemicals Market Segment Analysis
-
By Type, the Acid and Base Chemicals segment dominated the Semiconductor Chemicals Market with approximately 39.38% share in 2025, while the High-Performance Polymers segment is the fastest growing with a CAGR of approximately 13.06%.
-
By End Use, the Integrated Circuits segment dominated the Semiconductor Chemicals Market with approximately 67.08% share in 2025, while the Optoelectronics segment is the fastest growing with a CAGR of approximately 12.65%.
-
By Application, the Cleaning segment dominated the Semiconductor Chemicals Market with approximately 28.73% share in 2025, while the Photolithography segment is the fastest growing with a CAGR of approximately 13.15%.
-
By Purity Grade, the 5N segment dominated the Semiconductor Chemicals Market with approximately 46.84% share in 2025, while the 6N and Above segment is the fastest growing with a CAGR of approximately 13.35%.
By Type, Acid and Base Chemicals Dominates the Semiconductor Chemicals Market and High-Performance Polymers Grows Fastest
Acid and Base Chemicals dominated the Semiconductor Chemicals Market in 2025, supported by their extensive use in wafer cleaning, etching, and surface preparation. Chemicals such as sulfuric acid, hydrofluoric acid, and ammonium hydroxide help remove contaminants and prepare wafers for subsequent fabrication stages. Increasing semiconductor production and stringent cleanliness requirements sustain demand. Their essential role across multiple manufacturing processes reinforces their importance in maintaining device quality, process consistency, and production yields.
High-Performance Polymers are projected to record the fastest growth, driven by rising demand for advanced semiconductor packaging and specialized electronic materials. These polymers provide thermal stability, mechanical strength, and chemical resistance under demanding manufacturing conditions. Increasing chip complexity, miniaturization, and the adoption of advanced packaging technologies are expanding their applications. Continued innovation in semiconductor fabrication and packaging is expected to encourage demand for polymer materials that support component reliability, precision, and performance.
⮞Soulbrain RASA TX said in June 2026 that its Taylor, Texas plant will carry an annual production capacity of 28,800 metric tons of high-purity phosphoric acid. The capacity places a large block of wet chemical supply inside the United States and shows how acid producers are following fab investment.
By End Use, Integrated Circuits Dominates the Semiconductor Chemicals Market and Optoelectronics Grows Fastest
Integrated Circuits dominated the Semiconductor Chemicals Market in 2025 because their manufacturing requires chemicals throughout wafer cleaning, photolithography, etching, deposition, and polishing. Rising demand for processors, memory chips, automotive electronics, and data-center semiconductors supports production activity. Increasing circuit complexity and tighter manufacturing tolerances further intensify requirements for high-purity process chemicals. The extensive use of these materials across fabrication stages reinforces integrated circuits as a major source of semiconductor chemical consumption.
Optoelectronics is projected to record the fastest growth, supported by increasing adoption of optical communication components, photonic devices, LEDs, and advanced sensors. Manufacturing these devices requires specialized chemicals for substrate preparation, cleaning, etching, and material deposition. Expanding data-center connectivity, high-speed optical networks, and demand for efficient sensing technologies are encouraging production. Advances in photonic integration and precision manufacturing are expected to increase the need for specialized semiconductor chemicals that support device quality and performance.
⮞In October 2025, Qnity Electronics signed a memorandum of understanding with a leading memory chipmaker for a long term supply agreement covering CMP polishing pads. Planarization consumables of this kind are central to integrated circuit manufacturing, and the agreement shows how memory demand locks in multi-year supply.
By Application, Cleaning Dominates the Semiconductor Chemicals Market and Photolithography Grows Fastest
Cleaning dominated the Semiconductor Chemicals Market in 2025 because removing particles, organic residues, and metallic contaminants is essential throughout semiconductor fabrication. Even minute impurities can impair device performance and reduce manufacturing yields. Multiple cleaning stages are required during wafer preparation, etching, deposition, and polishing. As chip geometries shrink and fabrication processes become more complex, manufacturers increasingly depend on high-purity cleaning chemicals to maintain surface quality, minimize defects, and ensure consistent production performance.
Photolithography is projected to register the fastest growth, driven by demand for increasingly precise patterning in advanced semiconductor devices. The process uses photoresists, developers, solvents, and related chemicals to transfer circuit designs onto wafers. Shrinking feature sizes, advanced process nodes, and investment in leading-edge fabrication facilities are increasing demand for specialized formulations. Developments in advanced lithography techniques are expected to support chemical consumption by enabling accurate pattern formation, tighter process control, and consistent manufacturing yields.
⮞For instance, in February 2025, Dongjin Semichem announced a project of more than USD 110.00 Million in Killeen, Texas to make ultra-high-purity photoresist thinner. Thinner is used in every coating step of the lithography process, so a local plant strengthens the supply chain for patterning chemicals in the United States.
By Purity Grade, 5N Dominates the Semiconductor Chemicals Market and 6N and Above Grows Fastest
The 5N segment dominated the Semiconductor Chemicals Market in 2025, supported by demand for chemicals with 99.999% purity across semiconductor manufacturing processes. These materials help control contamination during wafer cleaning, etching, and other fabrication stages. Their established commercial availability and balance between purity requirements and cost support widespread use. Semiconductor production volumes and rigorous quality-control practices continue to sustain demand for 5N-grade chemicals across manufacturing facilities producing a broad range of electronic devices.
The 6N and Above segment is projected to record the fastest growth as advanced semiconductor manufacturing requires increasingly stringent contamination control. Chemicals with purity levels of 99.9999% or higher help minimize trace impurities that may affect device reliability and manufacturing yields. Advanced process nodes, high-performance computing chips, and sophisticated memory devices are strengthening demand for ultra-high-purity materials. Expanding investment in leading-edge fabrication capacity is expected to support adoption, although requirements vary according to specific manufacturing processes and cost considerations.
⮞Solvay reported in September 2025 that its Zhenjiang, China site doubled production capacity for electronic grade hydrogen peroxide with impurities held in single-digit parts per trillion. That specification level is typical of the ultra-high purity tier and shows suppliers building plants for the most demanding grades.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
29.70 |
|
North America |
United States |
94.00 |
|
Europe |
Germany |
34.00 |
|
Latin America |
Mexico |
41.00 |
|
MEA |
Israel |
32.00 |
Asia Pacific Semiconductor Chemicals Market Insights
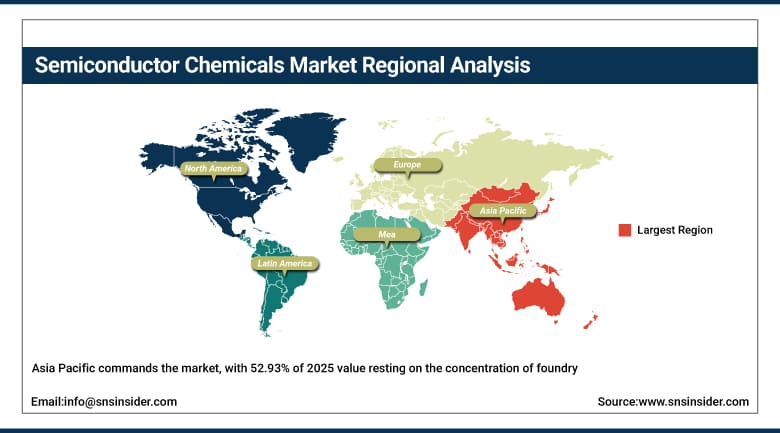
Asia Pacific commands the market, with 52.93% of 2025 value resting on the concentration of foundry, memory and packaging capacity in Taiwan, South Korea, China and Japan. Chemical buyers in these countries run some of the world's largest fabs, and they demand a steady stream of cleaning acids, developers, slurries and gases. Japanese suppliers retain depth in photoresists and high purity wet chemicals, while South Korean producers expand quickly alongside memory growth. Proximity to customers makes local qualification faster and favors suppliers with plants inside the region.
China is the largest national market in the region and is pushing hard for self-sufficiency in electronic chemicals as new fabs come online. Taiwan and South Korea rank among the leaders in consumption, supported by leading edge logic and memory lines. India is at an earlier stage, yet new fab and assembly projects are building a base for future chemical demand. Local capacity additions by global and regional producers are reducing lead times and are pulling advanced grades closer to the point of use.
⮞Merck KGaA inaugurated its Kaohsiung semiconductor materials megasite in December 2025 on a campus of 150,000 square meters. The company describes the site as the largest semiconductor materials campus worldwide, which confirms Taiwan as a core node for thin films, formulation materials and specialty gases.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Semiconductor Chemicals Market Insights
North America is projected to post the quickest regional expansion, advancing at a CAGR of 13.54% between 2026 and 2035. That pace reflects a fab construction wave in Arizona, Texas and neighboring states, backed by public incentives and large commitments from foundries and memory makers. As each site nears production, nearby chemical, gas and slurry plants must be ready with qualified supply. The region starts from a smaller base than Asia Pacific, which magnifies the growth rate of every new plant.
The United States accounts for nearly all regional demand, and its buyers lean on suppliers that can deliver ultra pure grades in bulk with strong safety and traceability records. Industrial gas majors are building on-site facilities within fab complexes, while specialty chemical firms break ground on purification and blending plants. Canada adds a smaller base of demand from photonics and specialty device producers. Advanced packaging projects add further requirements for plating, etch and polymer chemistries in the region. Safe handling and delivery rules also favor nearby sourcing.
⮞In July 2026, Linde announced that it will invest USD 1.00 Billion to expand its existing on-site industrial gases complex in Phoenix, Arizona. The project adds two new air separation units and shows how gas supply for leading edge fabs is being built at scale in North America.
Europe Semiconductor Chemicals Market Insights
Europe builds its position on strengths in automotive, industrial and power semiconductors and on a deep chemical industry. Germany is the largest national market, hosting both device fabs and the chemical clusters that supply high purity acids, bases and solvents. Specialty fabs for power, analog and sensor chips run mature nodes and buy large volumes of wet process chemistry. Regional policy aims to raise the continent's share of global chip output, which would lift chemical consumption in step. Buyers value dependable regional sourcing.
Regulation shapes supplier strategy more in Europe than elsewhere. Proposed limits on PFAS push producers to reformulate etchants, surfactants and resist components, and sustainability targets influence solvent recovery and water use. The United Kingdom is expected to be the fastest growing national market, supported by compound semiconductor and design activity. Suppliers that offer low PFAS products and recycling services stand to gain preference from European fabs. Water use and energy cost add to the equation, and vendors that publish credible environmental data gain trust with buyers.
⮞In June 2026, the European Commission adopted a proposal for the Chips Act 2.0. The proposal carries the regional chip strategy into a second phase, and any resulting fab expansion would raise demand for high purity process chemicals across Europe.
Latin America and MEA Semiconductor Chemicals Market Insights
Latin America holds a small share of the market because wafer fabrication in the region is still at a very early stage. Mexico anchors regional demand through electronics assembly and test activity, and national industrial plans promote semiconductor design and future production. Chemical consumption today centers on cleaning and packaging related materials, and most advanced grades arrive through imports. Progress on a first local fab would create the first meaningful need for locally supplied process chemicals. Policy support remains the main swing factor.
The Middle East and Africa region remains the smallest market, with Israel as the main center of demand thanks to its established fabs and chip design industry. Elsewhere in the region the absence of local wafer fabs limits chemical consumption to small volumes tied to assembly and research. Interest in semiconductor ventures across the Gulf may create future opportunities for gas and chemical suppliers. Near term growth will rely on imports of qualified electronic grade materials from Asia and Europe.
Market Dynamics
Growth Drivers: Record chip demand and a global fab build-out are raising chemical consumption per wafer.
Demand for semiconductors from AI servers, data centers, vehicles and consumer devices is lifting wafer starts and the number of process steps per chip. Each added layer in logic and 3D NAND brings extra cleaning, etching and deposition cycles that consume acids, bases, solvents and gases. Memory makers keep raising stack heights while logic makers move to gate all around transistors. Both trends lengthen process flows. Chemical consumption therefore grows faster than wafer area, and suppliers with qualified high purity products capture that multiplier directly.
New fab construction compounds the effect. Many 300 mm fabs and lines are being planned across the United States, Asia and Europe, and each needs a stable local chemical supply before it can ramp. Equipment installation precedes chemical qualification, so supplier engagement begins early. Chemical makers sign multi-year agreements and often co-locate purification units, which locks in volume well ahead of production. Governments back the build-out with incentives for fabs and materials suppliers. Packaging expansion adds a second wave of demand for plating, etch and polymer chemistries.
⮞The Semiconductor Industry Association reported in February 2026 that global semiconductor sales reached USD 791.70 Billion in 2025. Higher chip output at that scale feeds directly into wafer starts and sustains the need for cleaning, etching and patterning chemicals.
Restraints: Tightening PFAS and chemical waste regulation is raising compliance costs and reformulation burdens for suppliers.
Many fluorinated compounds appear in etchants, surfactants and photoresist components because they deliver stability under aggressive process conditions. Proposed restrictions on PFAS in Europe and similar scrutiny elsewhere force producers to search for substitutes. Each replacement chemistry must pass fab qualification, which can take years and cost heavily. Until alternatives match performance, suppliers face uncertainty over product lines, legal exposure and investment timing. Photoresist developers and surfactant-rich cleans are among the products most exposed. Customers also ask for full disclosure of ingredients and alternatives.
Environmental rules on chemical waste, wastewater and air emissions add to operating costs, particularly for acids and solvents that need treatment or recovery after use. Transport of hazardous liquids across borders is regulated tightly and exposes supply chains to disruption. Holding impurity levels consistent at parts per trillion needs costly analytics and clean packaging, which raises the entry barrier for smaller producers. These pressures slow capacity additions and squeeze margins on mature products. Compliance spending falls hardest on mid-sized producers with limited capital and may push them to exit marginal lines.
⮞In December 2025, the Committee for Socio-economic Analysis of the European Chemicals Agency finalized its conclusions for the electronics and semiconductor sector within the EU PFAS restriction process. The finding moves the restriction closer to implementation and keeps reformulation pressure on fluorinated process chemicals.
Opportunities: National chip programs and onshore fab construction are opening new demand for locally produced high-purity chemicals.
Governments in the United States, Europe, India and East Asia are funding fabs and the supplier ecosystems around them. New sites create the chance to win long term supply positions before incumbent relationships form. Chemical producers that build purification and blending capacity near these clusters can shorten qualification and cut logistics risk. Reshoring programs therefore reward suppliers that commit capital early and hold the right purity credentials. Early entrants often secure anchor customer contracts that last across multiple fab phases. Public grants can offset part of the cost of building new plants.
Technology shifts open further doors. Low PFAS and sustainable chemistries are emerging as a premium segment, while advanced packaging, gallium nitride and silicon carbide devices need new etchants, cleans and polymers. AI-driven demand for logic and memory sustains growth in the highest purity grades. Suppliers that pair new formulations with recycling services, on-site delivery and digital quality tracking can differentiate and build lasting accounts. Regional demand centers such as India are drawing first-time investment, and local chemical production there could grow alongside fab projects.
⮞In July 2026, India's Cabinet approved the India Semiconductor Mission 2.0 with an outlay of USD 13.25 Billion. The program includes support for semiconductor equipment and materials, which creates a new sourcing base for process chemicals in South Asia.
Recent Developments:
-
In February 2025, FUJIFILM Electronic Materials announced an investment to add CMP slurry and photoresist developer production lines at its Zwijndrecht site in Belgium, with operation planned from the spring of 2026. The expansion brings advanced slurry and developer supply closer to European fabs and shortens delivery chains.
-
July 2026, Air Liquide announced an investment of more than USD 150.00 Million in a new Idaho facility that will supply ultra-pure nitrogen, oxygen and argon to a leading memory chip manufacturer, with operations scheduled for 2028. The project secures long term gas supply for a major memory site and extends the on-site model.
-
August 2025, Tokyo Ohka Kogyo announced the first phase of a high-purity chemical building at Pyeongtaek in South Korea, covering about 6,300 square meters with a start planned for the second half of 2027. The plant places photoresist-related chemistry beside a major memory and foundry cluster.
-
December 2025, Kanto Chemical, through its KPPC Advanced Chemicals unit, broke ground on a USD 120.00 Million first phase of an ultrapure chemical campus in Casa Grande, Arizona, with production planned for late 2027. The campus adds local ultrapure supply for Arizona fabs.
Semiconductor Chemicals Market Key Players
-
Entegris
-
Merck KGaA (EMD Electronics)
-
BASF
-
FUJIFILM Electronic Materials
-
JSR
-
Tokyo Ohka Kogyo
-
Qnity Electronics
-
Linde
-
Air Liquide
-
Air Products
-
Solvay
-
Resonac
-
Soulbrain
-
Dongjin Semichem
-
Moses Lake Industries
-
Kanto Chemical
-
Technic Inc
-
Daikin
-
Hansol Chemical
-
Tokuyama
Semiconductor Chemicals Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 16.25 Billion |
| Market Size by 2035 | USD 49.80 Billion |
| CAGR | CAGR of 11.85% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Acid and Base Chemicals, High-Performance Polymers, Adhesives, Solvents, and Others) • By End Use (Integrated Circuits, Discrete Semiconductors, Optoelectronics, Sensors, and Others) • By Application (Cleaning, Photolithography, Etching, Deposition, Doping, and Others) • By Purity Grade (4N, 5N, and 6N and Above) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Entegris, Merck KGaA (EMD Electronics), BASF, FUJIFILM Electronic Materials, JSR, Tokyo Ohka Kogyo, Qnity Electronics, Linde, Air Liquide, Air Products, Solvay, Resonac, Soulbrain, Dongjin Semichem, Moses Lake Industries, Kanto Chemical, Technic Inc, Daikin, Hansol Chemical, Tokuyama |
Frequently Asked Questions
The key players include Entegris, Merck KGaA (EMD Electronics), BASF, FUJIFILM Electronic Materials and JSR, among others.
Key opportunities arise from national chip programs and new fab construction that reward suppliers able to deliver ultra-high-purity chemicals close to the point of use.
The major growth factor is the rising chemical consumption per wafer, which results from advanced nodes, EUV lithography, 3D memory stacking and advanced packaging, combined with record chip demand from AI and data center applications.
The Acid and Base Chemicals segment dominated the market with approximately 39.38% share in 2025.
Asia Pacific dominated the market with approximately 52.93% share in 2025, owing to the concentration of foundry, memory and packaging capacity in Taiwan, South Korea, China and Japan.
