
Gas Turbine Services Market Report Scope & Overview:
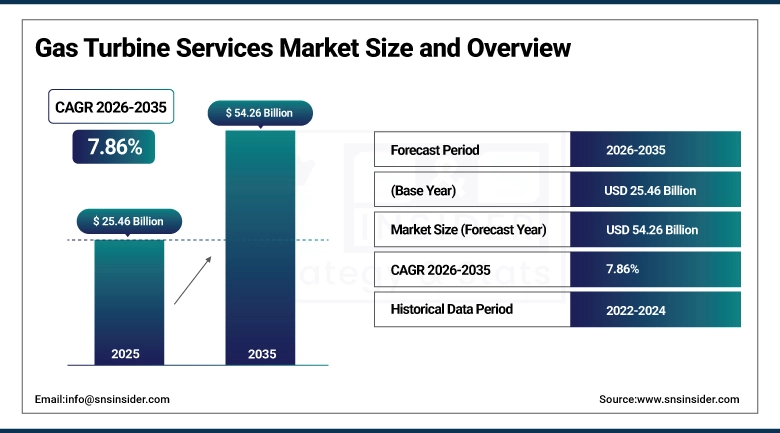
The Gas Turbine Services Market was valued at USD 25.46 Billion in 2025 and is expected to reach USD 54.26 Billion by 2035, growing at a CAGR of 7.86% from 2026-2035.
The Gas Turbine Services Market is expanding steadily as operators work to keep an aging, heavily utilized global fleet reliable while new-unit delivery slots stretch toward the end of the decade. Utilities, independent power producers, and oil and gas operators are extending outage intervals, upgrading hot-gas-path components, and signing multi-year agreements that bundle parts, repairs, and performance guarantees. Rising electricity demand from data centers, coal retirements, and the need for dispatchable power alongside renewables are increasing running hours and shortening inspection cycles. Remote diagnostics and condition-based maintenance are reducing unplanned downtime, while independent repair specialists are widening competition against original equipment manufacturers across every major turbine frame. Hydrogen-ready combustor upgrades are adding a longer-term layer of service scope to fleets.
⮞In May 2026, long-term fleet support came into focus when GE Vernova reported that its HA gas turbine fleet had passed 4 million commercial operating hours across 128 units in 21 countries, adding that each new HA unit typically ships with a long-term maintenance and performance contract that feeds its multi-decade services backlog.
To Get more information On Gas Turbine Services Market - Request Free Sample Report
Gas Turbine Services Market Trends
-
Rising shift from calendar-based overhauls to condition-based maintenance programs.
-
Growing demand for aeroderivative engine exchanges and lease-pool support.
-
Expanding use of AI-enabled remote diagnostics on connected turbine fleets.
-
Increasing adoption of hot-gas-path upgrades for output and efficiency gains.
-
Rising share of independent providers servicing mature OEM turbine frames.
-
Growing preparation of existing fleets for hydrogen blending and carbon capture.
U.S. Gas Turbine Services Market Outlook
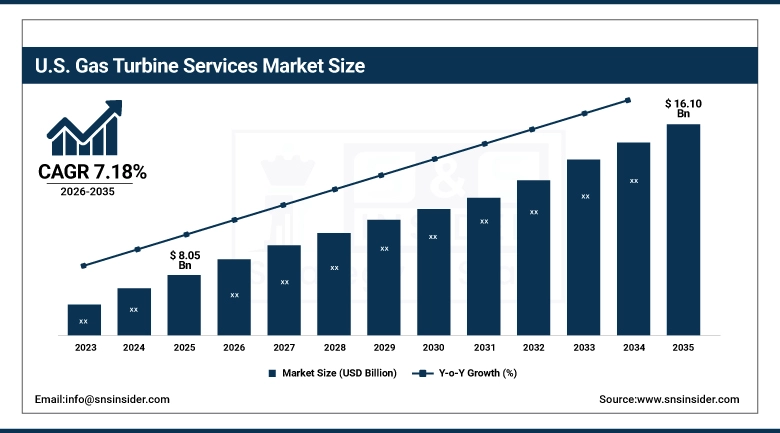
The U.S. Gas Turbine Services Market was valued at USD 8.05 Billion in 2025 and is expected to reach USD 16.10 Billion by 2035, growing at a CAGR of 7.18% from 2026-2035.
The U.S. Gas Turbine Services Market continues to grow as the country operates the largest installed base of large-frame and aeroderivative units, many of which are two decades old and running at higher capacity factors than originally planned. Coal-to-gas switching, data center load growth, and reliability concerns in several grid regions are encouraging owners to defer retirements and invest in inspections, rotor exchanges, and performance upgrades. Texas, the Southeast, Pennsylvania, and the Mid-Atlantic hold dense clusters of combined cycle plants served by OEM field teams and independent repair shops near Houston, Greenville, and Orlando. Long delivery times for new turbines further extend the working life of existing units. Gulf Coast LNG exporters add steady, recurring demand for mechanical-drive turbine support.
⮞In August 2026, Houston's repair capacity expanded when Allied Power Group acquired TRS Services, LLC, a turbine repair firm founded in 1998. TRS is building a new 50,000-square-foot repair center, which adds component repair capacity for Siemens and Alstom units to Allied Power Group's existing work on GE Frame 5, 6, 7E/F, and 9 turbines.
Gas Turbine Services Market Segment Analysis
-
By Service Type, the Maintenance and Repair segment dominated the Gas Turbine Services Market with approximately 35.46% share in 2025, while the Remote Monitoring and Diagnostics segment is the fastest growing with a CAGR of approximately 9.34%.
-
By Turbine Type, the Heavy Duty segment dominated the Gas Turbine Services Market with approximately 72.18% share in 2025, while the Aeroderivative segment is the fastest growing with a CAGR of approximately 8.93%.
-
By Service Provider, the OEM segment dominated the Gas Turbine Services Market with approximately 61.87% share in 2025, while the Non-OEM segment is the fastest growing with a CAGR of approximately 9.18%.
-
By Contract Type, the Long-Term Service Agreements segment dominated the Gas Turbine Services Market with approximately 48.32% share in 2025, while the Performance-Based Contracts segment is the fastest growing with a CAGR of approximately 10.26%.
-
By End User, the Power Generation segment dominated the Gas Turbine Services Market with approximately 66.45% share in 2025, while the Oil and Gas segment is the fastest growing with a CAGR of approximately 8.52%.
By Service Type, Maintenance and Repair Dominates the Gas Turbine Services Market and Remote Monitoring and Diagnostics Grows Fastest
Maintenance and repair remains the backbone of the market because every operating turbine needs scheduled combustion, hot-gas-path, and major inspections, along with unplanned repairs to blades, vanes, combustor liners, and rotors. Owners running units in peaking and cycling duty rack up starts and equivalent operating hours faster than planned, which pulls inspection dates forward. The installed base of Frame 6B, 7E, 7F, and 9E machines, many beyond twenty years of age, relies on repeated repair of coated and cooled hot parts rather than full replacement. Plant owners also prefer outage work by field teams that restore performance quickly, since lost generation during a long outage costs more than the repair. Predictive scheduling further trims outage duration.
Remote monitoring and diagnostics is advancing fastest as operators move away from fixed-interval overhauls toward condition-based maintenance. Sensors on compressors, combustors, and bearings stream data to OEM and independent operations centers, where analytics flag combustion dynamics, vibration drift, and efficiency loss well before a trip. Baker Hughes' iCenter, Siemens Energy's Omnivise platform, and GE Vernova's Controls Lifecare Services show how vendors now package digital surveillance with long-term contracts. Falling sensor costs, secure connectivity at unmanned sites, and lean operating teams are speeding adoption, and monitoring agreements increasingly act as the entry point for parts and outage business. Providers that bundle these analytics with guaranteed response times report stronger renewal rates among independent power producers.
⮞In June 2026, Baker Hughes extended its long-term service agreement with Nigeria LNG to a 13-year scope for Train 7 on Bonny Island, covering four heavy-duty gas turbines with centrifugal compressors and two power-generation gas turbines. The package is delivered from the Port Harcourt service center and includes iCenter digital services, powered by Cordant, for remote monitoring and diagnostics.
By Turbine Type, Heavy Duty Dominates the Gas Turbine Services Market and Aeroderivative Grows Fastest
Heavy duty turbines anchor the market because utilities and independent power producers depend on E-class, F-class, and H-class frames for baseload and mid-merit generation, and these machines carry the largest parts values and the longest outage scopes. Their hot-gas-path components follow predictable replacement cycles, so spending is recurring and easy to forecast. Coal retirements and a steady pipeline of combined cycle additions keep large frames under heavy dispatch, while upgrade programs that raise output, improve efficiency, and extend inspection intervals draw retrofit spending. OEMs bundle these upgrades into multi-decade agreements, which concentrates revenue from the installed fleet in this category. Spare parts pooling and rotor exchange programs help owners shorten outages on these large machines.
Aeroderivative units are growing faster on the strength of fast-start peaking, offshore platforms, LNG compression, and behind-the-meter power for data centers. Their modular design allows complete engine exchanges, so an operator can install a replacement and send the removed engine to a shop, which supports lease-pool and exchange programs. Utilities adding firm capacity to balance solar and wind, and industrial sites that need on-site generation while grid interconnections remain slow, are enlarging the base of LM2500 and LM6000 engines. Frequent starts and stops accelerate wear, which raises the number of shop visits, borescope inspections, and hot section repairs for these engines. Industrial users such as refiners and chemical sites add further demand for compact, quick-start power equipment.
⮞In April 2026, PROENERGY announced it would deliver 13 PE6000 aeroderivative gas turbine generator sets, each rated at 50 MW, for a combined 650 MW to AI infrastructure provider Crusoe. The units will be test-fitted and quality-checked at the company's Sedalia, Missouri, facility before shipment, ahead of installation at upcoming hyperscale data center projects.
By Service Provider, OEM Dominates the Gas Turbine Services Market and Non-OEM Grows Fastest
OEM providers lead because they control the engineering data, proprietary combustion and coating technologies, and warranty terms for their turbines, and they tie service offerings to the original equipment contract. Buyers of advanced-class units usually sign OEM long-term agreements at the time of order, locking in parts, inspections, and performance guarantees for decades. OEMs also invest heavily in repair centers, digital platforms, and remanufacturing facilities that smaller companies find hard to match. Because H-class and HL-class machines remain under proprietary design control, the OEM channel is expected to keep the larger share of revenue even as independents gain ground on older frames. Lenders and insurers also tend to favor OEM-backed work on critical assets.
Non-OEM providers are gaining share as owners of mature fleets look for lower-cost parts, repairs, and flexible scheduling. Independent specialists increasingly hold engineering licenses, reverse-engineered designs, and repair processes for GE, Siemens, Alstom, and Mitsubishi frames, which lets them compete directly on hot-gas-path components, rotor services, and field outages. Tight OEM shop capacity and long lead times for new parts are pushing owners toward multi-vendor strategies, and private equity funding is financing acquisitions that broaden independent footprints. Operators of aging combined cycle plants in North America, the Middle East, and Southeast Asia are among the most active adopters of this model. Warranty-compatible repair standards are helping them win business from cautious utilities and lenders.
⮞In February 2026, EthosEnergy acquired the intellectual property needed to service Frame 9FA.03 gas turbines, giving the non-OEM provider a technical basis to repair and supply hot-gas-path and combustion parts for the unit's key sections worldwide. The move followed its 2025 purchase of Turbine Services Limited, a New York aftermarket parts manufacturer.
By Contract Type, Long-Term Service Agreements Dominate the Gas Turbine Services Market and Performance-Based Contracts Grow Fastest
Long-term service agreements lead because they give owners cost certainty and risk transfer over inspection cycles that can span a decade or longer. Lenders financing combined cycle projects frequently require them, since they secure planned maintenance, guaranteed parts availability, and defined outage durations. For OEMs, these contracts turn a one-time turbine sale into multi-decade revenue and provide early visibility into outage scheduling and parts demand. Agreements increasingly include upgrade options, remote monitoring, and fleet-level performance reporting, which strengthens renewal rates. As new gas turbine orders rise, the number of agreements signed alongside equipment purchases keeps growing. Renewal terms are frequently negotiated years ahead of major outages, which keeps customers with the same vendor for several cycles.
Performance-based contracts are the fastest-growing structure as owners prefer to pay for outcomes such as availability, heat rate, or output rather than for individual repairs or operating hours. These agreements tie vendor compensation to measured plant results and often pair digital analytics with guaranteed degradation limits. Merchant generators and data center developers that sell firm capacity under strict reliability commitments are especially receptive, because penalties for unavailability can be steep. Vendors gain stronger customer alignment and can fund upgrades that lift output, since the resulting gains are shared. Wider availability of plant data from connected turbines makes these terms easier to define and verify. Shared savings arrangements also tend to strengthen long-term relationships with customers.
⮞In May 2026, Doosan Enerbility signed gas turbine service contracts valued at about KRW 480 billion with Korea Southern Power for the Goyang Changneung combined heat and power plant and the Hadong combined cycle plant, both targeting commercial operation in December 2029. The scope covers hot parts supply, reconditioning, consumables, and technical support.
By End User, Power Generation Dominates the Gas Turbine Services Market and Oil and Gas Grows Fastest
Power generation accounts for the largest portion of service demand because gas-fired plants supply a growing share of dispatchable electricity worldwide and run at high capacity factors. Utilities and independent power producers operate thousands of heavy duty and aeroderivative units that face scheduled outages under reliability requirements. Coal-to-gas switching, capacity additions to support electrification, and the use of gas turbines to balance variable renewables are all increasing running hours and start counts. Rising electricity demand from data centers has also encouraged owners to delay retirements and fund life extension programs for older units, sustaining a steady flow of inspection, repair, and upgrade work. Outage calendars set far in advance give vendors clear visibility into labor and parts needs.
Oil and gas operators are growing fastest as upstream platforms, FPSOs, gas processing plants, and LNG terminals depend on gas turbines for mechanical drive and on-site power, and their production schedules leave little room for downtime. Expanding liquefaction capacity in the United States, Qatar, and Nigeria, together with deepwater development off Brazil and Guyana, is enlarging the number of compressor and generator drives that need lifecycle support. Many of these sites are remote, which favors nearby service centers, digital monitoring, and exchange engines. Operators are also outsourcing maintenance to OEMs and specialist providers so that internal teams can concentrate on core production. Compressor-drive turbines on gas pipelines add further demand as transmission operators expand throughput.
⮞In June 2026, Chevron's Energy Forge One LLC signed a 20-year power purchase agreement with Microsoft for Project Kilby, a phased 2.67 GW gas power hub in West Texas to be built around large GE Vernova turbines and Solar Turbines equipment. Chevron is developing the site with Engine No. 1 as a collaborator, creating a long-run lifecycle service requirement for the fleet.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
86.41% |
|
Asia Pacific |
China |
31.64% |
|
Europe |
Germany |
22.58% |
|
Latin America |
Brazil |
38.72% |
|
Middle East & Africa |
Saudi Arabia |
34.96% |
North America Gas Turbine Services Market Insights
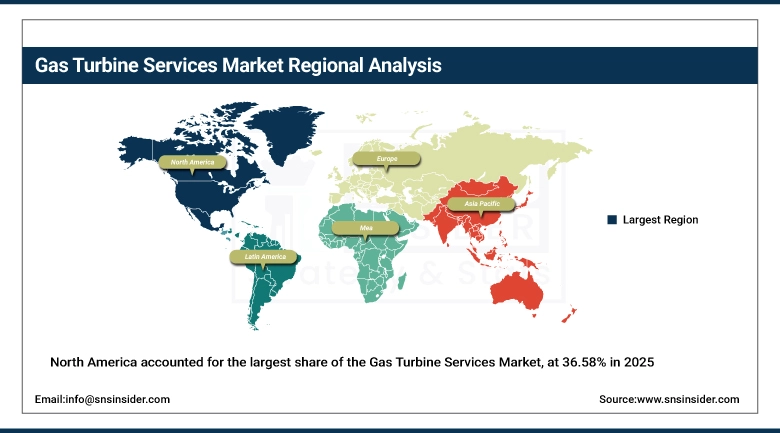
North America accounted for the largest share of the Gas Turbine Services Market, at 36.58% in 2025, supported by one of the world's biggest gas turbine fleets, high capacity utilization, and a mature aftermarket ecosystem. Inexpensive shale gas, large-scale coal-to-gas conversions, and rapid growth in data center electricity demand are keeping older units online. OEM service centers operate alongside independent repair shops that compete on turnaround time and cost. Utilities and independent power producers are adopting long-term agreements and condition-based maintenance to protect availability, and many are upgrading E-class and F-class units to raise output and efficiency while new capacity remains scarce. Aftermarket competition has also pushed OEMs to offer shorter lead times and bundled outage scopes.
In the United States, merchant generators in Texas, PJM, and the Southeast are funding hot-gas-path upgrades and rotor exchanges, and pipeline operators and LNG exporters on the Gulf Coast need compressor-drive support. Canada contributes through Alberta's cogeneration and oil sands facilities, where aeroderivative and industrial turbines require regular overhauls and emissions-related retrofits. Mexico's Comisión Federal de Electricidad and private generators are adding gas-fired capacity and service contracts as industrial demand expands along the border. Continued fleet aging and rising power demand are expected to keep North America the leading regional market through the forecast period. Aeroderivative fleets supporting wellhead gas compression in the Permian Basin and Marcellus add regular engine exchanges and repair work.
⮞In September 2026, Liburdi Turbine Services and Hughes Technical Services, an AP4 company, announced a partnership at Mooresville, North Carolina, to support owners of Alstom gas turbines. It combines Liburdi's proprietary LPM hot gas path repair process with new and refurbished parts supply, added shop capacity, and a dedicated engineering support team.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Gas Turbine Services Market Insights
Asia Pacific is the fastest-growing regional market, projected to expand at a CAGR of 9.12% from 2026 to 2035, as rapid electrification, industrial expansion, and the shift from coal to natural gas add new combined cycle capacity that will soon require service. China is building a local service base around Shanghai Electric, Harbin Electric, and joint ventures with foreign OEMs, while demand for LNG-to-power projects is rising in Southeast Asia. Governments in the region are also extending the life of existing plants to protect supply security, which increases overhaul and upgrade activity across older frames and sustains demand for independent repair shops. Regional service hubs in Singapore and Malaysia are expanding to shorten engine turnaround.
India is a key growth engine, with state utilities and private operators maintaining a large fleet of GE-designed Frame 9E and 6B units through BHEL-GE service ventures and independent shops. Japan and South Korea contribute through advanced-class combined cycle fleets, hydrogen co-firing trials, and long-term parts agreements with local manufacturers. Australia supports aeroderivative and industrial turbines used in LNG, mining, and peaking applications, while Indonesia, Vietnam, Thailand, and the Philippines are signing parts and service agreements for plants commissioned over the past two decades. Local repair centers are being opened to shorten turnaround times and reduce import costs for hot-section parts. Hot-section repair capacity in Asia is expected to remain tight through the decade.
⮞In March 2026, Kawasaki Heavy Industries and Kobe Steel began supplying hydrogen fuel to a gas turbine generator at the Kobe Hydrogen Energy Center in Japan using an intermediate fluid vaporizer and a liquefied hydrogen pump, a combination described as the first of its kind. A wet-type combustion gas turbine received hydrogen fuel in January 2026, with a dry-type unit to follow.
Europe Gas Turbine Services Market Insights
Europe is a sizeable regional market in which gas turbines act as flexible backup for wind and solar output, and as a replacement for retiring coal and nuclear capacity. Germany leads the region, with large combined cycle fleets operated by utilities such as RWE, EnBW, and Uniper, and a strong base of OEM and independent service centers. Capacity mechanisms and security-of-supply programs in Germany, the United Kingdom, Italy, and Poland are making plant owners keep older units available, which sustains outage and upgrade spending. Regional manufacturers including Siemens Energy and Ansaldo Energia hold a strong position in long-term agreements for their installed units. Gas-fired units are also being kept ready for winter peaks and low-wind periods.
The United Kingdom's gas fleet is receiving efficiency upgrades and hydrogen-readiness studies, and the Netherlands and Italy are modernizing combined cycle plants to meet tighter emissions limits. Spain, France, and Poland add demand through peaking capacity and cogeneration units that serve industrial sites. Offshore oil and gas platforms in the North Sea also depend on aeroderivative and industrial turbines for power and compression, creating a steady need for exchange engines and overhauls. Preparation of existing fleets for hydrogen blending and carbon capture is shaping new service offerings, and decommissioning of older plants keeps the market balanced rather than expanding quickly. Hydrogen-capable combustors will influence repair scopes for newer units in the coming decade.
⮞In July 2026, Tauron selected Ansaldo Energia to supply a turbine island with two AE94.3 gas turbines, each rated at 314.6 MW, for a 600 MWe peaking gas unit at Jaworzno in Poland. The award includes an additional service contract valued at EUR 100 million net, tying the plant to Ansaldo Energia's aftermarket support.
MEA & Latin America Gas Turbine Services Market Insights
The Middle East & Africa is a fast-emerging market led by Saudi Arabia, the UAE, Qatar, Oman, and Kuwait, where gas-fired plants supply most electricity and national utilities and independent producers sign multi-decade service agreements. Saudi Arabia is replacing liquid-fired generation with gas and has been localizing outage capability, while Abu Dhabi and Oman are adding large combined cycle blocks. Oil and gas operators including Saudi Aramco, ADNOC, and QatarEnergy depend on turbines for compression and power. In Africa, Nigeria's LNG and gas processing expansions and South Africa's peaking plants are widening the base for lifecycle support. Localization targets are pushing OEMs to build service centers, train regional engineers, and shift some repair work closer to customers.
⮞In July 2026, Siemens Energy secured contracts for six SGT5-4000F gas turbines and six SGen5-2000P generators for the Misfah and Duqm combined cycle plants in Oman, which will add 2.6 GW to the national grid. The agreements are accompanied by 20-year long-term service agreements covering the turbines.
Latin America is developing steadily, supported by Brazil, Mexico, Argentina, and Colombia. Brazil's gas-to-power plants, pre-salt FPSOs, and refineries rely on large aeroderivative fleets, and Petrobras alone runs roughly 40 LM6000 and 150 LM2500 units that require continuous shop support. Mexico's industrial corridor and the Comisión Federal de Electricidad's combined cycle plants generate recurring overhaul work, while Argentina's Vaca Muerta shale expansion needs compression and power generation for gas treatment. Colombia relies on gas-fired units as backup for hydropower in dry years, keeping a modest but regular flow of inspections and repairs. Local service centers in Brazil and Mexico are expanding to reduce transit time for engines moving to shops abroad, while currency swings affect parts pricing.
⮞In July 2026, MTU Maintenance signed an exclusive five-year contract with Petrobras covering ten LM6000TM industrial gas turbines and three hot sections. Overhaul work will take place at MTU Maintenance Berlin-Brandenburg, with field services delivered by MTU Maintenance do Brasil at four sites across Rio de Janeiro and Minas Gerais.
Market Dynamics
Growth Drivers: Aging Gas Turbine Fleets and Rising Data Center Power Demand
Much of the installed gas turbine base was commissioned between 2000 and 2010 during the first wave of combined cycle construction, and these units are now reaching their second and third major inspection cycles. Owners face scheduled hot-gas-path replacements, rotor life assessments, and control system obsolescence that cannot be postponed without reliability risk. Units that were designed for baseload now run through frequent starts and stops, which consumes component life faster than original maintenance plans assumed. Extension of operating life through upgrades is generally cheaper than building new capacity, so the aging fleet itself produces a long and predictable stream of service demand. These programs are usually contracted years ahead and repeat on defined intervals.
Electricity demand from data centers and AI computing is raising utilization of existing gas plants and encouraging the construction of new on-site generation, both of which expand the service base. Operators of data center campuses want high availability, so they sign performance guarantees and remote monitoring rather than relying on informal maintenance. Delivery slots for new large-frame turbines now reach toward 2030, which makes keeping current units healthy and upgrading them for extra output a rational alternative. Utilities in regions with tight reserve margins are delaying retirements, creating further inspection, repair, and uprate work. Hyperscale operators also value fast response, which supports local parts inventories and on-call field engineers near their campuses.
⮞In June 2026, Hallador Energy agreed to buy about 460 MW of unfired Siemens gas turbines and generators for USD 350 million to build its Merom simple-cycle project in Indiana. The units will be refurbished at Siemens USA before shipment, a route chosen because new-unit availability from original manufacturers is reported at late 2028 at the earliest.
Restraints: Supply Chain and Skilled Labor Constraints and Competition from Renewables and Storage
Service providers face long lead times for castings, forgings, and coated hot-section parts, since the same foundries and coating shops supply new-unit production and repair work. Competition for shop capacity can extend outage windows and push owners to buy refurbished or reverse-engineered components. A shortage of trained field engineers, welders, and controls specialists limits how many outages a provider can run in the same season, especially during spring and autumn shoulder periods when many plants schedule work together. Rising wages, travel costs, and tariffs on imported alloys are also raising service prices, which can prompt customers to defer discretionary upgrades. Providers that hold regional parts inventories and trained crews gain an advantage when capacity is tight.
Expanding solar, wind, and battery storage capacity reduces the running hours of some gas turbines, particularly in markets where renewables are subsidized or where storage can capture evening peaks. Lower operating hours extend inspection intervals and cut parts consumption, which slows service revenue for peaking and mid-merit units. Policy goals for decarbonization also create uncertainty about the long-term life of gas assets, making some owners reluctant to commit to multi-decade agreements or large upgrades. Service vendors must therefore balance growth in high-utilization markets with weaker demand in regions that are phasing out fossil generation. Customers consequently negotiate shorter contract terms and demand exit clauses in some markets, which weakens revenue visibility for vendors.
Opportunities: Hydrogen and Carbon Capture Retrofits and Digital Performance Services
Gas turbine owners are preparing existing units for hydrogen blending and for integration with carbon capture, which opens a new class of retrofit and service work. Combustor upgrades, fuel system modifications, materials reviews, and revised control logic are needed to burn hydrogen blends safely, and each program carries multi-year engineering and testing scopes. Carbon capture projects require changes to exhaust conditions, heat recovery equipment, and plant controls that OEMs and independent specialists can package into service contracts. Policy incentives for low-carbon power in the United States, Europe, and Japan are encouraging owners to commit to these conversions rather than retire assets. Early projects will also create reference designs that make later conversions faster and less costly.
Digital performance services offer a second opportunity as providers use AI models, digital twins, and fleet-wide data to predict failures, optimize combustion tuning, and plan outages. These tools can reduce unplanned downtime and improve heat rate, giving vendors a basis to sell performance-based contracts and subscription analytics. Independent providers can also use open data platforms to serve mixed-OEM portfolios that large owners operate. As sensor coverage and connectivity improve, the volume of operating data available for service decisions will increase, supporting higher-margin advisory and optimization offerings. Subscription pricing for these services produces recurring revenue that is less tied to outage calendars. Smaller operators, which lack in-house data science teams, are likely to outsource analytics to vendors with large fleet datasets.
⮞In July 2026, Entergy and MHI Group agreed to a collaboration that pairs M501JAC gas turbine combined cycle plants with carbon capture, aiming to cut carbon capture costs by half for projects in Louisiana. The work places a carbon-capture-ready gas turbine package at the center of future retrofit and long-term service scopes.
Recent Developments:
-
July 2026: Ansaldo Energia reported that its GT36 fleet had passed 80,000 equivalent operating hours and that the fleet leader at Edison's Marghera Levante combined cycle plant in Italy had completed the first B1 inspection. The 780 MW plant pairs a 515 MW GT36 with a 265 MW steam turbine, and the inspection tests the maintenance assumptions the platform was designed around.
-
July 2026: EthosEnergy sold its operations and maintenance business, which served more than 200 facilities, to Brown & Root Industrial Services, keeping its aftermarket repair and overhaul of industrial gas turbines and rotating equipment. The company retains access to Brown & Root's remote monitoring and plant health diagnostics through a continuing commercial partnership.
-
August 2026: Mitsubishi Heavy Industries said its backlog of large-frame gas turbines had reached 35 GW, up from 23 GW a year earlier, while it continues plans to double production capacity compared with 2024. The company reported 10 large-frame orders in the first quarter, four for the United States and six for Japan, lengthening the pipeline of units that will need lifecycle service.
-
October 2026: Siemens Energy announced it will supply 119 SGT-400 gas turbine cores, about 15 MW each and roughly 1.7 GW in total, for Dynamis Power Solutions' DT18 hypermobile power packages aimed at U.S. data centers and oil and gas sites. The cores will be built at the Lincoln, United Kingdom, facility, with deliveries starting in 2027.
Revised Gas Turbine Services Market Key Players
-
GE Vernova Inc.
-
Siemens Energy AG
-
Mitsubishi Heavy Industries, Ltd. (Mitsubishi Power)
-
Baker Hughes Company
-
Solar Turbines Incorporated (Caterpillar Inc.)
-
Ansaldo Energia S.p.A.
-
Everllence (formerly MAN Energy Solutions)
-
Kawasaki Heavy Industries, Ltd.
-
EthosEnergy Group
-
Sulzer Ltd.
-
MTU Aero Engines AG
-
Centrax Limited
-
PROENERGY Services, LLC
-
Bharat Heavy Electricals Limited (BHEL)
-
Rolls-Royce Holdings plc
-
MJB International
-
Pratt & Whitney
-
Wood Group (Wood)
-
Chromalloy
Gas Turbine Services Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 25.46 Billion |
| Market Size by 2035 | USD 54.26 Billion |
| CAGR | 7.86% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Service Type: Dominant – Maintenance and Repair (35.46% share in 2025); Fastest-Growing – Remote Monitoring and Diagnostics (CAGR 9.34%) • By Turbine Type: Dominant – Heavy Duty (72.18% share in 2025); Fastest-Growing – Aeroderivative (CAGR 8.93%) • By Service Provider: Dominant – OEM (61.87% share in 2025); Fastest-Growing – Non-OEM (CAGR 9.18%) • By Contract Type: Dominant – Long-Term Service Agreements (48.32% share in 2025); Fastest-Growing – Performance-Based Contracts (CAGR 10.26%) • By End User: Dominant – Power Generation (66.45% share in 2025); Fastest-Growing – Oil and Gas (CAGR 8.52%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | GE Vernova Inc., Siemens Energy AG, Mitsubishi Heavy Industries, Ltd. (Mitsubishi Power), Baker Hughes Company, Solar Turbines Incorporated (Caterpillar Inc.), Ansaldo Energia S.p.A., Everllence (formerly MAN Energy Solutions), Kawasaki Heavy Industries, Ltd., EthosEnergy Group, Sulzer Ltd., MTU Aero Engines AG, Centrax Limited, PROENERGY Services, LLC, Bharat Heavy Electricals Limited (BHEL), Rolls-Royce Holdings plc, MJB International, Pratt & Whitney, Wood Group (Wood), Chromalloy |

Frequently Asked Questions
Key players include GE Vernova Inc., Siemens Energy AG, Mitsubishi Heavy Industries, Ltd. (Mitsubishi Power), Baker Hughes Company, Solar Turbines Incorporated, Ansaldo Energia S.p.A., and Everllence, among other OEMs and independent service providers.
Hydrogen and carbon capture retrofits for existing turbines, along with digital performance services such as AI-based diagnostics and performance-based contracts, represent the primary opportunities.
Growth is primarily driven by aging gas turbine fleets that require scheduled inspections and upgrades, combined with rising data center power demand that is increasing turbine utilization.
By Service Type, Maintenance and Repair dominated the market with approximately 35.46% share in 2025, reflecting recurring inspection cycles and the repair of coated hot-gas-path components.
North America dominated the market with approximately 36.58% share in 2025, driven by a large installed turbine fleet, high capacity utilization, and a mature aftermarket ecosystem.
