
Geocomposites Market Report Scope & Overview:
The Geocomposites Market was valued at USD 568.35 Million in 2025 and is anticipated to climb to USD 611.26 Million in 2026 and USD 1176.85 Million by 2035, registering a CAGR of 7.55% over 2026–2035. Geocomposites are engineered products that bond two or more geosynthetic materials, such as geotextiles, geonets, geomembranes and geogrids, into a single layer that performs several jobs at once. They drain water, separate soil layers, filter fines, reinforce ground and contain liquids, and they replace thick layers of gravel and sand in roads, railways, landfills and water projects.
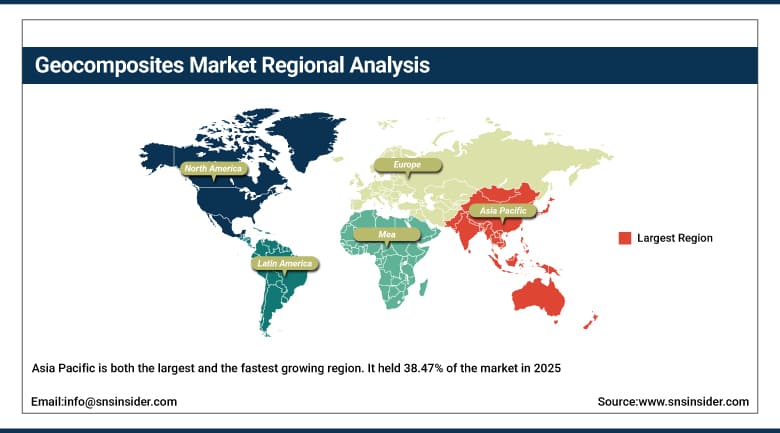
Asia Pacific accounted for the largest share of the market, at 38.47% in 2025, as China, India and Southeast Asia build roads, railways, dams and urban drainage at large scale. Europe is the second largest region, followed by North America, Latin America and Middle East and Africa. Asia Pacific is also the fastest growing region, supported by infrastructure budgets and stricter rules on landfill and mining containment. Producers sell through engineering firms, distributors and direct project supply, and design support from the manufacturer often decides which product is chosen.
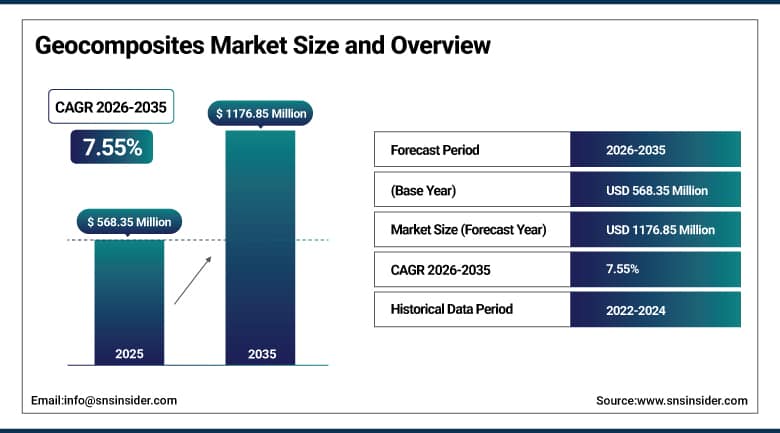
To Get More Information On Geocomposites Market - Request Free Sample Report
Key Report Takeaways
-
By type, geotextile-geonet composites held a 31.75% share in 2025, while geotextile-geocore composites are the fastest growing.
-
By function, drainage held a 45.00% share in 2025, while separation is the fastest growing.
-
By application, road and highway held a 40.38% share in 2025, while water and wastewater management is the fastest growing.
-
By region, Asia Pacific held a 38.47% share in 2025 and is also the fastest growing.
Market Trends and Insights
Engineers are replacing granular layers with thin synthetic drainage systems. A composite sheet can carry water flow equal to a thick bed of gravel, weighs little and arrives in rolls, which cuts trucking, excavation and installation time. Contractors on tight schedules and in locations where aggregate is scarce or expensive increasingly specify these products in retaining walls, tunnels, green roofs and sports fields.
Climate adaptation is opening new uses. Heavier rainfall, flooding and coastal erosion are driving investment in stormwater channels, bank protection, culverts and flood control embankments, and designers use composites for drainage, filtration and slope stabilization. Public agencies are also asking for materials with lower embodied carbon, which favors lightweight products and recycled polymers.
Product design is becoming more specialized. Manufacturers are adding high-strength geogrid layers to drainage composites, developing foam and cuspated cores for compression resistance, and offering prefabricated vertical drains and bentonite-enhanced liners. Digital installation tools, such as sensors that detect leaks under liners and drones that check quality, help owners confirm performance after construction.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Infrastructure spending on roads, railways and water projects |
+3.18% |
Asia Pacific, North America and Europe |
Long term (4 years or more) |
|
Stricter landfill, mining and environmental containment rules |
+2.34% |
Europe, North America and Asia Pacific |
Medium term (2 to 4 years) |
|
Flood, stormwater and climate resilience projects |
+1.46% |
Asia Pacific, Europe and North America |
Medium term (2 to 4 years) |
|
Cost and time savings versus aggregate-based systems |
+0.88% |
Global |
Short term (2 years or less) |
|
Growth in mining, renewable energy and industrial sites |
+0.66% |
Latin America, Middle East and Africa and Asia Pacific |
Long term (4 years or more) |
Infrastructure Spending on Roads, Railways and Water Projects
Governments are investing in highways, rail corridors, airports, ports, canals and dams to support economic growth and replace aging assets. Geocomposites are used beneath pavements to drain water from the base, between layers to prevent mixing of soils, and along tracks to stabilize ballast. Large public programs in India, China, the United States and Europe provide steady project pipelines, and design standards increasingly recognize geosynthetics as a standard part of road and rail construction. Funding pipelines extend several years ahead, which supports order visibility.
Stricter Landfill, Mining and Environmental Containment Rules
Rules on waste disposal and mine tailings require liners, leachate collection and protective layers that prevent contamination of soil and groundwater. Geocomposites combine drainage cores with geotextiles or geomembranes to collect leachate and protect liners from puncture. As more countries close open dumps and build engineered landfills, and as mining companies upgrade heap leach pads and tailings storage, demand for these systems rises. Regulators also require long-term monitoring, which favors high-quality products. Third-party inspections add further demand for certified materials.
Flood, Stormwater and Climate Resilience Projects
Extreme rainfall, urban flooding and rising sea levels are pushing cities and agencies to build drainage channels, retention basins, bioswales and coastal defenses. Geocomposites provide quick drainage in retaining walls, tunnel linings, bridge abutments and green roofs, and they stabilize slopes that are vulnerable to saturation. Funding for resilience programs, including international development finance, supports adoption in flood-prone regions. Municipal agencies also add composite drains to bridge approaches and culverts during repair work, and insurers favor resilient design that reduces recurring flood damage.
Cost and Time Savings versus Aggregate-Based Systems
A single roll of composite can replace a thick layer of sand or gravel, which reduces material hauling, excavation depth and compaction effort. Lighter loads on soft ground also allow thinner structures, and faster installation shortens closure of roads and rail lines. Where quality aggregate is far from the site or its price has risen, designers favor composites, and life-cycle comparisons often show lower total cost and emissions. Reduced truck traffic also lowers road wear and emissions near busy construction sites.
Growth in Mining, Renewable Energy and Industrial Sites
Mines need large lined ponds, heap leach pads and tailings facilities, and wind and solar plants require access roads and drainage on challenging terrain. Industrial parks, logistics hubs and data centers also need controlled stormwater systems. These projects are often in remote places, where light, easily shipped composite products reduce transport cost and speed construction. Operators also value that composites arrive on site in compact rolls, which suits difficult terrain and tight construction windows, and mining companies request long design lives for liners and drains.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Volatile polymer and resin prices |
-0.42% |
Global |
Short term (2 years or less) |
|
Limited awareness, standards and skilled installation |
-0.28% |
Asia Pacific, Middle East and Africa and Latin America |
Medium term (2 to 4 years) |
|
Competition from traditional aggregate and single-layer geosynthetics |
-0.17% |
Global |
Long term (4 years or more) |
|
Project delays and public budget constraints |
-0.10% |
Global |
Medium term (2 to 4 years) |
Volatile Polymer and Resin Prices
Geocomposites are made mainly from polypropylene, polyester and polyethylene, so their cost follows the prices of petrochemical resins, which move with oil, gas and supply disruptions. Producers often sell on long project bids and cannot adjust prices quickly when resin costs rise. Shipping rates also affect delivered prices, and small contractors may delay purchases when quotes change, which creates uneven demand across quarters. Some buyers sign fixed-price contracts, and producers then absorb the extra input cost until new quotes are accepted.
Limited Awareness, Standards and Skilled Installation
In many developing markets designers still default to gravel and sand, and local codes do not yet cover composite drainage or reinforcement. Installers need training on seams, overlaps, anchoring and protection from damage, and poor workmanship can lead to leaks or clogging. A few failures can make owners cautious, so manufacturers spend heavily on education, testing and technical support. Universities and industry associations are publishing guidelines, yet adoption of those guidelines by public agencies is slow and uneven across regions.
Competition from Traditional Aggregate and Single-Layer Geosynthetics
Conventional gravel drains are well understood and cheap where aggregate is plentiful, and simple geotextiles or geonets can meet the needs of less demanding sites. Contractors who already own equipment for placing stone may prefer it, and low-bid public tenders often reward the cheapest option rather than the best lifetime performance. This limits penetration in price-sensitive projects. Value engineering during construction can also replace specified composites with cheaper alternatives, especially when owners lack in-house technical staff to review proposals carefully.
Project Delays and Public Budget Constraints
Demand depends on the timing of construction, which can slip because of permitting, land acquisition, weather and financing. Public budgets may be reduced when governments face fiscal pressure, and large projects can be cancelled or postponed. Manufacturers with fixed production capacity feel the effect on utilization and margins, and wide gaps between order and delivery dates complicate planning. Elections and changes in government priorities can also reorder spending, so manufacturers keep large inventories and extend credit to contractors to secure orders.
Geocomposites Segment Analysis
By Type, Geotextile-Geonet Composites Dominate Geocomposites Market; Geotextile-Geocore Composites to Register Fastest Growth.
Geotextile-geonet composites lead the type axis, holding a 31.75% share in 2025. A plastic net core, which carries water in its open channels, is bonded to one or two layers of nonwoven geotextile that filter soil particles. The product offers high flow capacity at a low weight and reasonable price, so it is the usual choice for road bases, retaining walls, landfill leachate systems and sports fields. Wide availability from many suppliers keeps lead times short for contractors.
Geotextile-geocore composites are expected to register the fastest growth, at a CAGR of 8.64% during 2026–2035. These sheets use a three-dimensional core of polymer filaments, cuspated shapes or foam between geotextile faces, giving strong compression resistance and high flow under load. They suit deep fills, tunnels, green roofs and heavily loaded transport structures. Engineers choose them where loads are high, and specifiers value that the core keeps its flow capacity under pressure over many decades of service life.
By Function, Drainage Dominates Geocomposites Market; Separation to Register Fastest Growth.
Drainage leads the function axis, holding a 45.00% share in 2025. Geocomposites collect and carry away water from behind walls, beneath pavements, under embankments and around structures, which prevents pressure build-up and keeps soils stable. Because water is the main cause of damage to civil works, drainage is the function specified most often, and it is required in nearly every application. Highway agencies, rail operators and developers include drains in standard details, which makes the function a fixture of design.
Separation is projected to register the fastest growth, at a CAGR of 7.76% over 2026–2035. Composite layers keep soft subgrade from mixing with granular base, which preserves strength and extends pavement and rail life. Growing construction on weak soils, along with the need to cut aggregate use, increases adoption. Rail operators also use separation layers to keep ballast clean and extend maintenance intervals, and builders of logistics yards and parking areas use them to avoid rutting under heavy traffic.
By Application, Road and Highway Dominates Geocomposites Market; Water and Wastewater Management to Register Fastest Growth.
Road and highway construction leads the application axis, holding a 40.38% share in 2025. Geocomposites are placed under pavements, in shoulders and in embankment walls to drain water, separate layers and reduce freeze damage. Large road programs in Asia, North America and Europe, along with maintenance of aging networks, create steady volumes, and highway agencies increasingly include composite drainage in standard specifications. Maintenance of older networks adds repair projects that need quick installation with minimal traffic closures and little disruption.
Water and wastewater management is expected to register the fastest growth, at a CAGR of 8.16% during 2026–2035. Canals, reservoirs, treatment plants, stormwater basins and flood protection works use composites for lining protection, drainage and filtration. Investments in water security and urban drainage, together with development funding in emerging markets, support rapid expansion. Many utilities and municipalities are renewing pipes, pump stations and treatment works, and composites protect liners and drain surrounding soils in these works over many decades.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
42.80% |
|
Europe |
Germany |
19.60% |
|
North America |
United States |
84.30% |
|
Middle East and Africa |
Saudi Arabia |
28.40% |
|
Latin America |
Brazil |
47.20% |
Asia Pacific Geocomposites Market
Asia Pacific is both the largest and the fastest growing region. It held 38.47% of the market in 2025 and is expected to register a CAGR of 8.74% during 2026–2035. China leads with large road, rail, hydropower and urban drainage programs, while India is expanding highways, metro systems, dams and landfills under national infrastructure plans. Flood control, railway expansion and port development in Vietnam, Indonesia and Thailand add demand, and large government programs provide funding for long project pipelines across the region.
Japan and South Korea use composites in slope protection, tunnels and disaster resilience works, and Southeast Asian countries are building roads, ports and flood defenses. Australia adds demand from mining and rail projects. Local manufacturers are growing quickly, and international producers are opening regional plants to serve the market. Chinese suppliers offer competitive pricing and are expanding export sales, while Japanese and Korean firms focus on high-specification products. Quality standards are rising, and public agencies in India and China now require certified test data for drainage materials.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Geocomposites Market
Europe accounted for 26.91% of the market in 2025. Germany, France, the United Kingdom, Italy and the Nordic countries have well-developed standards for geosynthetics and a strong tradition of engineered landfills, railways and flood defenses. Renovation of aging road and rail networks provides steady demand, and several leading manufacturers are based in the region. The United Kingdom and Ireland use composites in flood alleviation schemes, rail embankments and motorways, and Nordic countries rely on them for freeze protection in roads and airfields.
Environmental rules on landfill, mining waste and construction materials favor engineered solutions, and sustainability targets encourage lower-carbon products. Eastern European countries are upgrading transport corridors with European funds, which creates additional demand for drainage and separation layers. Landfill capacity is shrinking as recycling targets rise, yet remaining sites and closure works require high-specification drainage and protection layers. Mining and energy projects in Scandinavia, Spain and Poland contribute further volume, and regional manufacturers export to the Middle East and North Africa from plants in Germany, Italy and Greece.
North America Geocomposites Market
North America held 21.08% of the market in 2025. The United States market was valued at USD 101.00 Million in 2025 and is projected to register a CAGR of 7.22% during 2026–2035. Federal infrastructure funding for roads, bridges, water systems and rail, together with strict landfill and coal ash rules, supports use of composites. Highway departments in cold states specify drainage layers to limit ground heave, and utilities rely on composites at coal ash impoundments and lined storage basins to meet federal rules.
Canada contributes through mining, oil sands, transport and hydropower projects, often in cold regions where freeze protection and drainage are critical. Mature design standards and a skilled installer base help adoption. Tariffs and trade policy on polymer products affect supply chains, and producers are adding local capacity to serve customers. Mining in Nevada, Arizona and Ontario uses heap leach and tailings systems that include drainage composites, while solar farms and data center campuses add drainage needs on large sites. Supplier networks are mature.
Middle East and Africa Geocomposites Market
Middle East and Africa accounted for 6.74% of the market in 2025. Gulf countries use composites in highways, airports, stadiums, water storage and landscaped developments, and Saudi Arabia leads the region through giga projects and large road and rail programs. Desert conditions also create demand for lining and protection in water conveyance and evaporation control. Water conveyance, desalination plant sites and storage reservoirs also need protective drainage layers, and developers of residential towers in the Gulf specify composites for basements and podiums.
In Africa, South Africa, Egypt and Morocco have established mining and infrastructure sectors, while East and West African countries are building roads and urban drainage with development financing. Limited local manufacturing and installer skills are challenges, but projects financed by international lenders increasingly specify modern geosynthetics. Rail and port projects in Kenya, Tanzania and Ethiopia are financed by international lenders that require modern drainage practice, and North African countries use composites for highway and irrigation works. Supply is mostly imported, which raises cost.
Latin America Geocomposites Market
Latin America held 6.80% of the market in 2025. Brazil leads the region, with roads, railways, hydropower, mining and landfill projects that use drainage and separation layers. Chile and Peru add demand from copper mining, where heap leach pads and tailings dams require protective composite systems. Landfill modernization in São Paulo, Rio de Janeiro and Minas Gerais requires leachate collection systems, and Brazilian rail and port concessions add drainage and separation needs along new corridors. Hydropower and sugar mills also use lined channels and drained structures.
Colombia and Argentina are expanding transport networks, and Mexico and Central America build highways, industrial parks and flood protection. Currency swings and project delays affect volumes, yet mining investment and growing urban populations support steady long-term growth. Argentina uses composites in oil and gas pads and road works in the Vaca Muerta region, while Colombia and Ecuador invest in mountain roads where drainage is critical for slope stability. Local distributors import most products, so currency swings and customs delays affect pricing.
Competitive Landscape
The Geocomposites Market is fragmented, with a few global geosynthetics groups that offer broad product lines and many regional manufacturers that compete on price in local projects. Large firms combine geotextiles, geogrids, geomembranes and composites with engineering support, while smaller producers focus on standard drainage products for nearby customers.
Competition depends on product performance, technical design support, price, distribution and project references. Companies are acquiring regional players, expanding plants close to demand and developing lower-carbon and recycled-content products. Over the forecast period, scale, engineering service and certified quality are expected to separate leading suppliers from the rest.
Geocomposites Industry Leaders
1. Solmax
2. Officine Maccaferri
3. HUESKER
4. NAUE
5. Thrace Group
Companies Covered in this Report
-
ABG
-
Climax Synthetics
-
GSE Environmental
-
HUESKER
-
NAUE
-
Officine Maccaferri
-
Solmax
-
Strata Geosystems
-
Terram
-
Thrace Group
Recent Industry Developments
-
February 2025: Officine Maccaferri announced the acquisition of Synteen Technical Fabrics, a US maker of high-strength polyester geogrids and fabrics, to expand in North America.
-
June 2025: Solmax began building a flagship manufacturing and innovation center in Les Mureaux, France, to boost regional production and logistics.
-
February 2026: Strata Geosystems acquired Venus Interlinings to expand its technical textiles and engineered materials portfolio.
-
March 2026: NAUE launched Secutex Green, a biodegradable nonwoven geotextile for temporary filtration and separation.
Scope and Research Methodology
This study sizes the Geocomposites Market for 2025 and forecasts it to 2035. The scope covers factory-made products that bond two or more geosynthetic components, including geotextile-geonet, geotextile-geocore, geomembrane-geotextile and geogrid-geotextile composites, measured as manufacturer sales value in USD Million. Standalone geotextiles, geogrids, geomembranes, geosynthetic clay liners, and erosion control products are excluded. Values are reported on a calendar year basis, and trade is allocated to the country of production. The historical period covers 2021 to 2024 and the forecast period covers 2026 to 2035. Sales are counted at the point of first sale by the manufacturer.
Research began with a review of infrastructure spending statistics, construction and mining project pipelines, polymer price data, trade records, company filings and technical standards. Demand was built from the bottom up using project area, specification rates and price per square meter by function and application, and it was cross-checked from the top down using the sales of leading geosynthetics producers. Segment and regional shares were set from construction mix, regulation and trade flows in each geography. Product prices were reviewed by type and construction to convert area into revenue, and constant exchange rates were used to remove currency effects from the series. Assumptions were documented for each major country. Project and distributor sales channels were both considered.
Findings were validated through discussions with manufacturers, distributors, design engineers and contractors, and the forecast was tested under scenarios for infrastructure funding, resin prices, regulation and project timing. Growth rates reflect expected specification growth and capacity additions. Values are expressed in USD, rounded to two decimals, and the analysis is refreshed when major market or policy changes occur. Estimates for each region were checked against national construction and trade statistics where available, and adjustments were made for imported and exported rolls. Results are reviewed periodically. Assumptions are documented for each major country.
Geocomposites Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 568.35 Million |
| Market Size by 2035 | USD 1176.85 Million |
| CAGR | CAGR of 7.55% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Geotextile-Geonet, Geotextile-Geocore, Geomembrane-Geotextile, Geogrid-Geotextile, and Others) • By Function (Drainage, Separation, Filtration, Reinforcement, and Others) • By Application (Road and Highway, Railways, Landfills and Waste Management, Water and Wastewater Management, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | ABG, Climax Synthetics, GSE Environmental, HUESKER, NAUE, Officine Maccaferri, Solmax, Strata Geosystems, Terram, Thrace Group |

Frequently Asked Questions
The market was valued at USD 568.35 Million in 2025 and is expected to reach USD 611.26 Million in 2026 and USD 1176.85 Million by 2035.
The market is projected to grow at a CAGR of 7.55% during 2026–2035.
Asia Pacific holds the largest share, at 38.47% in 2025, led by China.
Geotextile-geonet composites, drainage and road and highway lead, while geotextile-geocore composites, separation and water and wastewater management grow fastest.
Infrastructure spending, stricter containment rules, flood and climate resilience projects, savings versus aggregate and growth in mining and energy sites.
