
Hernia Mesh Devices Market Report Scope & Overview:
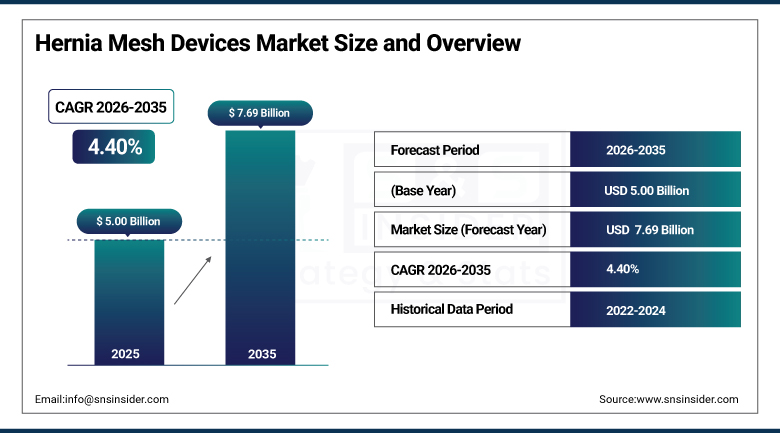
The Hernia Mesh Devices Market was valued at USD 5.00 Billion in 2025 and is expected to reach USD 7.69 Billion by 2035, growing at a CAGR of 4.40% from 2026-2035.
Hernia mesh devices are surgical implants placed across a weakened abdominal or groin wall to reinforce tissue and lower the risk of recurrence after repair. Tension-free mesh repair has become the accepted standard of care for inguinal hernias, and its use is now routine across ventral, incisional, and umbilical procedures as well. Growth is supported by a rising prevalence of hernias linked to ageing and obesity, wider use of minimally invasive and robotic surgery, and steady improvement in mesh materials. Manufacturers continue to invest in lightweight, pre-cut, and resorbable designs that reduce chronic pain and foreign-body response. Product liability litigation remains a defining feature of the industry, encouraging surgeons to favour newer, better-documented mesh options and steering suppliers toward stronger clinical evidence.
In December 2024, TELA Bio received clearance of a Special 510(k) from the U.S. Food and Drug Administration for two additional large-size offerings in its OviTex PRS portfolio. The clearance widened the range of defect sizes that the company's reinforced tissue matrix products can address in complex abdominal wall reconstruction.
To Get more information On Hernia Mesh Devices Market - Request Free Sample Report
Hernia Mesh Devices Market Trends
-
Rising preference for lightweight, macroporous meshes that reduce chronic postoperative pain.
-
Growing adoption of fully absorbable and hybrid meshes as alternatives to permanent synthetic implants.
-
Expanding use of robotic platforms for inguinal and ventral hernia repair.
-
Increasing demand for biologic and reinforced tissue matrices in contaminated surgical fields.
-
Rising migration of hernia procedures toward ambulatory surgical centers.
-
Growing scrutiny of permanent synthetic mesh following large-scale product liability settlements.
U.S. Hernia Mesh Devices Market Overview
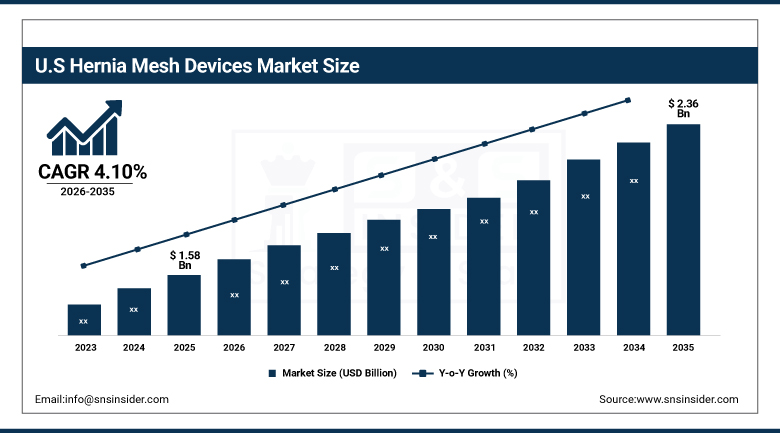
The U.S. Hernia Mesh Devices Market was valued at USD 1.58 Billion in 2025 and is expected to reach USD 2.36 Billion by 2035, growing at a CAGR of 4.10% from 2026-2035.
The domestic market constitutes the largest national market for hernia meshes based on the high level of elective abdominal wall surgery performed, extensive insurance coverage, and use of laparoscopic and robotic surgery methods. Obesity and increased laparotomy procedures lead to the rise of the patient population for whom ventral and incisional repairs are required, and the use of large and complicated meshes is inevitable. Despite the fact that the majority of procedures take place in hospitals, Medicare coverage growth is constantly transferring appropriate candidates into ASCs (ambulatory surgical centers). Lawsuits against permanent synthetic meshes had an impact on buying behavior of surgeons and value analysis panels who started to pay more attention to clinical studies, materials used, and outcomes.
In October 2024, Becton Dickinson agreed to settle approximately 38,000 hernia mesh lawsuits in the United States. The settlement resolved a large share of the outstanding product liability claims tied to permanent synthetic mesh and removed a major overhang for one of the domestic market's largest suppliers.
Hernia Mesh Devices Market Segment Analysis
-
By Mesh Type, the Synthetic segment dominated the market with a 83.70% share in 2025, while the Biologic segment is the fastest growing with a CAGR of 6.42% during 2026-2035.
-
By Mesh Material, the Non-Absorbable segment dominated the market with a 77.60% share in 2025, while the Fully Absorbable segment is the fastest growing with a CAGR of 7.12% during 2026-2035.
-
By Hernia Type, the Inguinal segment dominated the market with a 52.40% share in 2025, while the Ventral segment is the fastest growing with a CAGR of 6.54% during 2026-2035.
-
By Surgical Technique, the Open segment dominated the market with a 55.30% share in 2025, while the Robotic segment is the fastest growing with a CAGR of 6.98% during 2026-2035.
-
By End-User, the Hospitals segment dominated the market with a 47.90% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of 7.53% during 2026-2035.
By Mesh Type, Synthetic Dominates the Market and Biologic Grows Fastest
Synthetic mesh dominated the market in 2025. Polypropylene and other engineered polymers offer high tensile strength, predictable handling, and low cost per unit, which explains their use in the great majority of routine inguinal and ventral repairs. Surgeons value the long track record behind these products and the wide range of sizes, pore structures, and weights available, from ultralight meshes for groin repair to heavier constructs for large abdominal wall defects. Reimbursement structures also favour synthetic products, since hospitals can standardise on a small number of proven items and negotiate volume pricing with suppliers.
Biologic mesh is expected to be the fastest-growing type over the forecast period. Derived from decellularised human or animal tissue, these products encourage native tissue regeneration and are preferred in contaminated or infected surgical fields where permanent synthetic material carries a higher risk of complications. Interest has also grown among patients and surgeons wary of long-term foreign-body reactions to permanent implants. Reinforced biologic matrices, which combine a tissue scaffold with a limited amount of resorbable polymer, are extending the reach of this category into complex ventral and incisional repair.
By Mesh Material, Non-Absorbable Dominates the Market and Fully Absorbable Grows Fastest
Non-absorbable materials dominated the market in 2025. Permanent polymers such as polypropylene and polyester provide durable, lasting reinforcement of the abdominal wall, which is why they remain the default option for the bulk of elective hernia repairs. Their mechanical performance is well understood, manufacturing is mature and inexpensive, and they are supported by decades of clinical experience across every major surgical approach. This depth of evidence, together with wide availability and competitive pricing, keeps permanent materials at the centre of standard surgical practice.
Fully absorbable materials are projected to grow fastest over the forecast period. Platforms based on poly-4-hydroxybutyrate and similar resorbable polymers provide temporary support while the body builds its own repair tissue, leaving no permanent foreign material behind. That property is attractive in younger patients, in contaminated cases, and in a legal environment where long-term complications of permanent mesh have drawn attention. As clinical data on durability of the repair continue to accumulate, resorbable options are gaining a firmer place in surgeon preference lists.
By Hernia Type, Inguinal Dominates the Market and Ventral Grows Fastest
Inguinal hernia repair dominated the market in 2025. Groin hernias are the most common type worldwide and occur far more frequently in men, and mesh-based tension-free repair is used in nearly all such procedures in many health systems. The sheer procedure volume, combined with short surgical times and a well-established evidence base, keeps inguinal repair at the top of the market. Robotic and laparoscopic approaches are increasingly used for groin repair, further supporting demand for lightweight, pre-shaped meshes designed for minimally invasive delivery.
Ventral hernias are expected to grow fastest over the forecast period. Rising obesity, repeat abdominal surgery, and an ageing population are enlarging the group of patients with midline defects, many of which are wide and require component separation with large composite meshes. These cases generate substantially higher revenue per procedure than routine groin repair and are where biologic scaffolds, reinforced matrices, and resorbable constructs are most actively used. Growth in this category is therefore both volume-driven and value-driven.
By Surgical Technique, Open Dominates the Market and Robotic Grows Fastest
Open repair dominated the market in 2025. It remains the standard route for large, complex, or recurrent defects, for patients unsuitable for prolonged general anaesthesia, and in settings where laparoscopic infrastructure and training are limited. Open surgery is also the technique most often paired with component separation and biologic or large composite meshes, so it consumes a disproportionate share of higher-value implants. Its lower equipment requirements keep it dominant across emerging markets and smaller hospitals.
Robotic repair is projected to be the fastest-growing technique over the forecast period. Robotic platforms give surgeons better visualisation, wristed instruments, and improved ergonomics, which is particularly helpful for intraperitoneal placement, suturing of fascial defects, and complex ventral reconstruction. Robotic use is already substantial in groin repair in the United States, and hospitals are extending it to larger abdominal wall cases. Mesh makers are launching robot-compatible sizes and shapes to support this shift.
By End-User, Hospitals Dominates the Market and Ambulatory Surgical Centers Grows Fastest
Hospitals dominated the market in 2025. They handle the full spectrum of hernia surgery, including emergency, complex, and recurrent cases that require inpatient support, and they account for the majority of large ventral reconstructions. Purchasing is centralised through group contracts and value analysis committees, which favours established suppliers with broad portfolios. Access to advanced imaging, robotic systems, and multidisciplinary teams keeps hospitals at the centre of the market.
Ambulatory surgical centers are expected to be the fastest-growing end-user category over the forecast period. Uncomplicated inguinal and umbilical repairs are well suited to outpatient delivery, and payers increasingly favour the lower cost base of these facilities. Expanded coverage for hernia procedures in the ambulatory setting is accelerating the shift, and centers are adding laparoscopic and robotic capability to broaden the cases they can accept. Suppliers are adapting with compact product kits and simplified fixation systems.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
87.30% |
|
Europe |
Germany |
26.70% |
|
Asia Pacific |
China |
34.80% |
|
Latin America |
Brazil |
46.30% |
|
Middle East & Africa |
United Arab Emirates |
23.80% |
North America Hernia Mesh Devices Market Insights
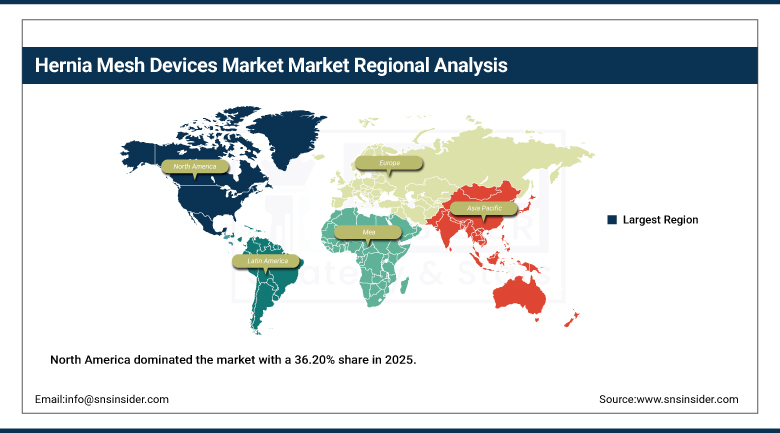
North America dominated the market with a 36.20% share in 2025. High surgical volumes, widespread private and public insurance coverage, and quick uptake of minimally invasive and robotic techniques underpin this leading position. The region is also home to several of the largest mesh manufacturers and to a well-organised network of hospitals and ambulatory centers that purchase through consolidated contracts, giving established suppliers a stable base of recurring demand and rapid access to clinical feedback.
Canada adds steady demand through its publicly funded system, where standardised tendering favours proven, cost-effective products. Continued interest in resorbable and reinforced biologic meshes, together with the migration of routine cases into outpatient settings, is expected to keep North America in front through the forecast period, although its growth rate will trail faster-developing regions where access to elective surgery is still expanding.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Hernia Mesh Devices Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 6.05% during 2026-2035. Large and ageing populations, improving hospital infrastructure, rising health spending, and growing awareness of mesh-based repair are widening access to elective hernia surgery. Governments across the region are investing in surgical capacity and in insurance schemes that cover common procedures, which is drawing more patients into treatment who would previously have gone without repair.
China anchors regional demand through its very large hospital network and expanding domestic device industry. India contributes rapid volume growth as private hospital chains add surgical capacity. Japan and South Korea add mature, technology-oriented demand, including growing use of laparoscopic and robotic approaches. Local manufacturers are also entering the market with lower-priced synthetic meshes, which is broadening adoption in price-sensitive settings.
Europe Hernia Mesh Devices Market Insights
Europe holds a substantial share of the global market, supported by well-developed public health systems, high procedure volumes, and a strong tradition of hernia surgery research. National societies publish detailed guidelines that endorse mesh repair, and registry data across several countries give surgeons unusually clear evidence on outcomes. Germany anchors regional demand with its large hospital sector and a domestic base of medical textile and device manufacturers.
The United Kingdom, France, and Italy add consistent demand, with the National Health Service using mesh in the great majority of inguinal repairs. Regulatory tightening under the European Medical Device Regulation has raised the evidentiary bar for new products, which slows launches but favours suppliers with strong clinical data. Interest in lightweight and resorbable designs is growing steadily across the region.
MEA & Latin America Hernia Mesh Devices Market Insights
The Middle East & Africa region is supported by expanding hospital construction and rising surgical capacity in the United Arab Emirates and Saudi Arabia, where government-backed healthcare programs are widening access to elective procedures. Medical tourism into Gulf hubs also adds volume for private hospitals that perform hernia repair with imported branded meshes.
Latin America is anchored by Brazil, where a large public system and a sizeable private sector sustain steady demand. Mexico adds further growth through private hospitals serving domestic and cross-border patients. Currency volatility and budget limits in public procurement encourage use of lower-cost synthetic meshes, though premium options are gaining ground in leading urban centers.
Market Dynamics
Growth Drivers: Rising Hernia Prevalence and Minimally Invasive Adoption
The rising prevalence of hernias is the primary growth driver. Global incidence runs into the tens of millions of cases, and ageing, obesity, chronic cough, and repeated abdominal surgery all raise the likelihood of developing a defect. Because mesh repair is the accepted standard of care for most hernias, growth in disease burden translates directly into demand for implants across both developed and emerging health systems.
Adoption of minimally invasive and robotic surgery is a second major driver. Shorter hospital stays, faster recovery, and lower wound complication rates make laparoscopic and robotic repair attractive to patients and payers, and they increase demand for pre-shaped, lightweight, and robot-compatible meshes. Continued advances in mesh materials and fixation devices strengthen this effect by improving outcomes and expanding the range of cases that can be treated through small incisions.
Restraints: Product Liability Litigation and Regulatory Scrutiny
Product liability litigation is a significant restraint. Thousands of lawsuits have been filed over complications attributed to certain permanent synthetic meshes, and large settlements have weighed on the financial results of several suppliers. The legal environment makes some surgeons and hospitals more cautious about specific products, encourages them to seek alternative materials, and raises the cost of insurance and compliance for manufacturers.
Regulatory scrutiny adds a further constraint. Authorities in the United States and Europe have tightened requirements for clinical evidence, post-market surveillance, and labelling of surgical mesh. These rules improve patient safety, yet they lengthen approval timelines and add cost, which can slow the launch of new products and disadvantage smaller companies with limited clinical resources.
Opportunities: Resorbable Materials and Ambulatory Care Expansion
Resorbable and hybrid mesh technology is a substantial opportunity. Companies that can show durable repair without permanent foreign material stand to gain share from surgeons and patients concerned about long-term complications. Reinforced biologic matrices and fully absorbable polymers open access to complex and contaminated cases that were historically difficult to treat with synthetic products.
The shift of hernia surgery into ambulatory surgical centers offers a further avenue for growth. As payers extend coverage for outpatient procedures, suppliers that provide compact, cost-effective product packages and simplified fixation systems can win contracts with a fast-growing customer group. Expansion into emerging markets, where elective surgery capacity is still being built, gives additional headroom for both premium and value-tier products.
Recent Developments:
-
2024: TELA Bio announced the full commercial launch in the United States of the LIQUIFIX hernia mesh fixation devices, distributed under an agreement with Advanced Medical Solutions.
-
2024: TELA Bio sold its distribution rights for the NIVIS fibrillar collagen pack to MiMedx Group in exchange for an initial payment of USD 5.0 million.
Hernia Mesh Devices Market Key Players
-
Ethicon, Inc. (Johnson & Johnson)
-
W. L. Gore & Associates, Inc.
-
Becton, Dickinson and Company (C. R. Bard)
-
B. Braun Melsungen AG
-
Integra LifeSciences Holdings Corporation
-
TELA Bio, Inc.
-
LifeCell Corporation (AbbVie)
-
Herniamesh S.r.l.
-
Aspide Medical
-
Dipro Medical Devices S.R.L.
-
FEG Textiltechnik mbH
-
Cousin Biotech
-
Betatech Medical
-
Deep Blue Medical Advances, Inc.
-
Advanced Medical Solutions Group plc
-
Meril Life Sciences Pvt. Ltd.
-
Lotus Surgicals Pvt. Ltd.
-
Textile Hi-Tec
Hernia Mesh Devices Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.00 Billion |
| Market Size by 2035 | USD 7.69 Billion |
| CAGR | CAGR of 4.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Mesh Type (Synthetic, Biologic, Composite) • By Mesh Material (Non-Absorbable, Partially Absorbable, Fully Absorbable) • By Hernia Type (Inguinal, Ventral, Incisional, Femoral, Umbilical, Others) • By Surgical Technique (Open, Laparoscopic, Robotic) • By End-User (Hospitals, Ambulatory Surgical Centers, Specialty Clinics) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Medtronic plc, Ethicon, Inc. (Johnson & Johnson), W. L. Gore & Associates, Inc., Becton, Dickinson and Company (C. R. Bard), B. Braun Melsungen AG, Cook Medical LLC, Integra LifeSciences Holdings Corporation, TELA Bio, Inc., LifeCell Corporation (AbbVie), Herniamesh S.r.l., Aspide Medical, Dipro Medical Devices S.R.L., FEG Textiltechnik mbH, Cousin Biotech, Betatech Medical, Deep Blue Medical Advances, Inc., Advanced Medical Solutions Group plc, Meril Life Sciences Pvt. Ltd., Lotus Surgicals Pvt. Ltd., Textile Hi-Tec |

Frequently Asked Questions
Key players include Medtronic plc, Ethicon, Inc., W. L. Gore & Associates, Inc., Becton, Dickinson and Company, B. Braun Melsungen AG, and Cook Medical LLC, among other medical device manufacturers.
Development of resorbable and reinforced biologic meshes and the shift of hernia surgery into ambulatory surgical centers represent the primary opportunities.
Growth is primarily driven by rising hernia prevalence linked to ageing and obesity, together with wider adoption of minimally invasive and robotic surgery.
By Mesh Type, Synthetic mesh dominated the market with an 83.70% share in 2025, reflecting its strength, low cost, and long clinical track record.
North America dominated the market with a 36.20% share in 2025, supported by high surgical volumes and broad insurance coverage.
