
Home Audio Equipment Market Report Scope & Overview:
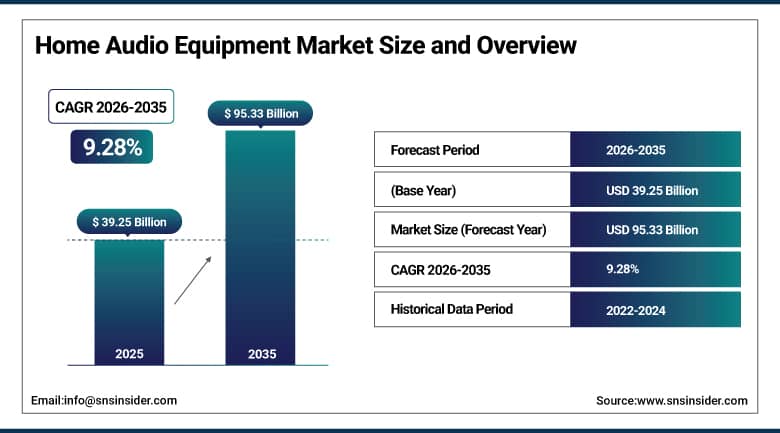
The Home Audio Equipment Market was valued at USD 39.25 Billion in 2025 and is expected to reach USD 95.33 Billion by 2035, growing at a CAGR of 9.28% from 2026-2035.
The Home Audio Equipment Market covers speakers, soundbars, home theater systems, audio-video receivers, amplifiers, multi-room systems, turntables and related products used to play music, film and television sound inside the home. Demand is shaped by the shift to wireless and voice-enabled speakers, the popularity of streaming music and video, the spread of large flat-panel televisions that need better sound than their built-in speakers can provide, and growing interest in immersive formats such as Dolby Atmos. Premiumization, smart home integration and a revival of vinyl listening support steady growth through 2035. Suppliers range from global electronics groups to specialist hi-fi houses.
⮞The International Federation of the Phonographic Industry reported on 18 March 2026 that global recorded music revenue rose 6.4% in 2025, with streaming revenue up 7.7%.
To Get More Information On Home Audio Equipment Market - Request Free Sample Report
Home Audio Equipment Market Trends
-
Soundbars and modular speaker systems supporting Dolby Atmos and wireless rear and subwoofer links are replacing traditional wired surround setups.
-
Voice assistants powered by generative artificial intelligence are being built into smart speakers, soundbars and multi-room systems.
-
Portable speakers with batteries, water resistance and Wi-Fi are blurring the boundary between indoor and outdoor listening.
-
Room calibration, spatial audio processing and ultra-wideband tracking are being used to tailor sound to the space and the listener.
-
Vinyl, turntables and premium hi-fi are gaining new buyers, supported by growth in physical music formats.
U.S. Home Audio Equipment Market Outlook
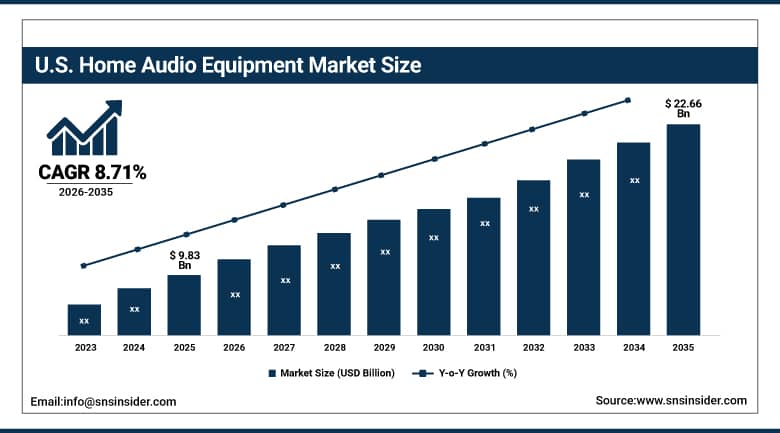
The U.S. Home Audio Equipment Market was valued at USD 9.83 Billion in 2025 and is expected to reach USD 22.66 Billion by 2035, growing at a CAGR of 8.71% from 2026-2035.
The U.S. Home Audio Equipment Market is the largest national market in North America, supported by large homes, high ownership of big-screen televisions, widespread streaming subscriptions and a strong culture of home entertainment. Consumers buy soundbars and wireless speakers in volume, while custom installation and premium hi-fi remain important in affluent households. Technology platform owners compete with audio specialists in smart speakers, and retailers run frequent promotions around holidays and major sporting events. Vinyl and turntable interest adds a growing enthusiast base. Strong holiday sales and sports viewing seasons create predictable peaks for soundbars and speakers. Suppliers also benefit from well-developed distribution networks. Gift-giving holidays remain the single biggest annual selling window.
⮞The Recording Industry Association of America reported in September 2026 that U.S. recorded music revenue rose 6.9% in the first half of 2026, with vinyl up 17.7%.
Home Audio Equipment Market Segment Analysis
-
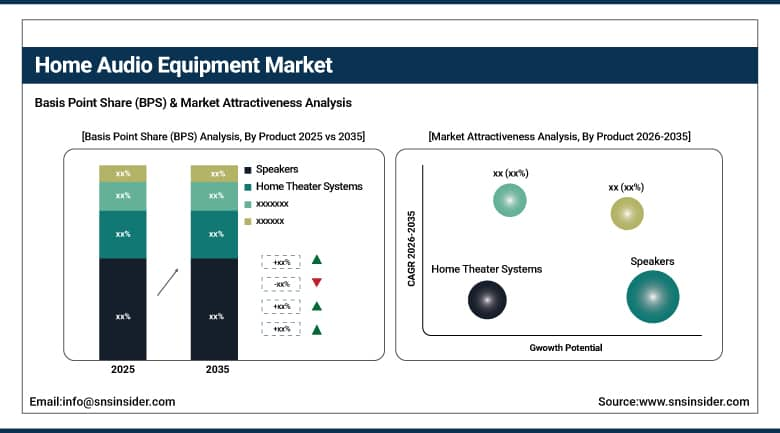
By Product, the Speakers segment dominated the Home Audio Equipment Market with approximately 37.64% share in 2025, while the Home Theater Systems segment is the fastest growing with a CAGR of approximately 10.86%.
-
By Technology, the Wireless segment dominated the Home Audio Equipment Market with approximately 63.28% share in 2025, and it is also the fastest growing with a CAGR of approximately 9.74%.
-
By Installation, the Fixed segment dominated the Home Audio Equipment Market with approximately 57.46% share in 2025, while the Portable segment is the fastest growing with a CAGR of approximately 9.38%.
-
By Distribution Channel, the Offline segment dominated the Home Audio Equipment Market with approximately 53.47% share in 2025, while the Online segment is the fastest growing with a CAGR of approximately 10.64%.
By Product, Speakers Dominate the Home Audio Equipment Market and Home Theater Systems Grow Fastest
Speakers hold approximately 37.64% of the Home Audio Equipment Market in 2025. The category spans bookshelf and floor-standing models, smart speakers, wireless multi-room units and compact Bluetooth designs, and it benefits from a wide price range that reaches students and audiophiles alike. Consumers upgrade speakers to improve music playback, to add voice assistants and to match new televisions, while a steady flow of new models keeps shelves fresh and encourages replacement. Strong brand heritage in this category also helps premium makers hold margins. Compact bookshelf models also appeal to apartment dwellers with limited space.
Home theaters are the fastest growing products with a CAGR of around 10.86% between 2026 and 2035. The full kit that is a combination of soundbar, subwoofer, and rear speakers provides an immersive experience along with easy installation and can be sold along with large TVs. Availability of Dolby Atmos, DTS:X, and wireless rear speakers eliminates the need for cables. The availability of streaming services that provide cinematic sound motivates households to purchase a room that offers a cinematic experience. They are bundled with large TVs during sales periods and increase the rate of attachment and purchase. Rear speakers offered separately enable the consumers to scale over time and make purchases in portions.
⮞The Japan Electronics and Information Technology Industries Association reported that shipments of audio amplifiers within Japan rose about 10.4% year on year in September 2026, while speaker systems fell about 13.3%.
By Technology, Wireless Dominates the Home Audio Equipment Market and Also Grows Fastest
Wireless products account for approximately 63.28% of the market in 2025. Wi-Fi and Bluetooth speakers, soundbars with wireless subwoofers and multi-room systems are easy to place, need no speaker cable and connect directly to streaming services and voice assistants. Consumers value the clean look and flexible layout, and manufacturers favor wireless designs because they can be updated through software and tied to an ecosystem of apps and accessories. Wireless also makes it simple for households to move speakers when they rearrange rooms. Software-defined features such as voice control and equalizer presets add recurring value. Firmware updates also let brands add features and fix issues without service visits.
The same technology is also the fastest growing, at a CAGR of approximately 9.74% during 2026-2035. Better wireless protocols with lossless and low-latency transmission have closed the quality gap with wired systems, and ultra-wideband links allow rear speakers to follow the listener. Wired products remain relevant to enthusiasts and custom installers who prize reliability, but incremental growth is concentrated in wireless formats. Chipsets supporting multi-device and multi-room playback have become cheaper, which brings wireless features into mid-priced products. Interoperability with major streaming and smart home standards also helps adoption.
⮞The Consumer Technology Association reported on 5 January 2026 that U.S. consumer technology unit shipments were forecast to grow 0.7% in 2026.
By Installation, Fixed Dominates the Home Audio Equipment Market and Portable Grows Fastest
Fixed products account for approximately 57.46% of the market in 2025. Soundbars mounted beneath televisions, in-wall and ceiling speakers, floor-standing towers, receivers and amplifiers are bought for permanent living rooms, dedicated theaters and open-plan homes. Installation brings higher spending per household, and professionals often design and calibrate the system. Housing activity and renovation projects influence the pace of these purchases. Dedicated theater rooms and in-wall installations are especially common in newly built homes. Owners often keep these systems for a decade or more. Home renovation spending supports demand.
Portable products are the fastest growing installation type, at a CAGR of approximately 9.38% through 2035. Battery-powered speakers with water resistance, wireless charging bases and power bank functions move easily between rooms, gardens and trips. Households use them as secondary speakers while retaining a main system, and the lower price points attract younger buyers. Longer battery life and multi-room linking raise their appeal. Rechargeable designs also reduce the need for power outlets near seating areas and patios. Compact designs now deliver respectable bass without a dedicated subwoofer. Outdoor entertaining and travel trends reinforce this demand.
⮞The National Association of Realtors reported on 13 October 2026 that existing-home sales in September 2026 were down 2.2% from a year earlier.
By Distribution Channel, Offline Dominates the Home Audio Equipment Market and Online Grows Fastest
Offline channels account for approximately 53.47% of the market in 2025. Electronics chains, specialty hi-fi shops, department stores and home improvement retailers let customers hear products before they buy, which matters for speakers and soundbars where sound quality is subjective. Staff can advise on room size, television pairing and installation, and retailers often showcase premium and flagship models in demonstration rooms. Premium hi-fi buyers in particular still visit listening rooms before committing to larger purchases. Warranty and after-sales service are also easier to arrange through physical stores.
Online is the fastest growing channel, with a CAGR of approximately 10.64% during 2026-2035. E-commerce platforms and brand websites offer detailed comparisons, bundles, financing and fast delivery, and return policies reduce the risk of buying unseen. Brands use direct online sales to build customer relationships and launch limited editions. Younger consumers in particular research and purchase audio gear almost entirely through digital channels. Marketplace sales events create strong peaks, and subscription-style financing reduces the barrier for high-priced items. Many online buyers shortlist products using professional reviews and video demonstrations. Fast delivery and easy returns raise conversion.
⮞The U.S. Census Bureau reported on 15 October 2026 that advance retail and food services sales rose 0.8% from August to September 2026.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
37.46% |
|
North America |
United States |
83.69% |
|
Europe |
Germany |
24.12% |
|
Latin America |
Brazil |
46.58% |
|
Middle East & Africa |
United Arab Emirates |
27.93% |
Asia Pacific Home Audio Equipment Market Insights
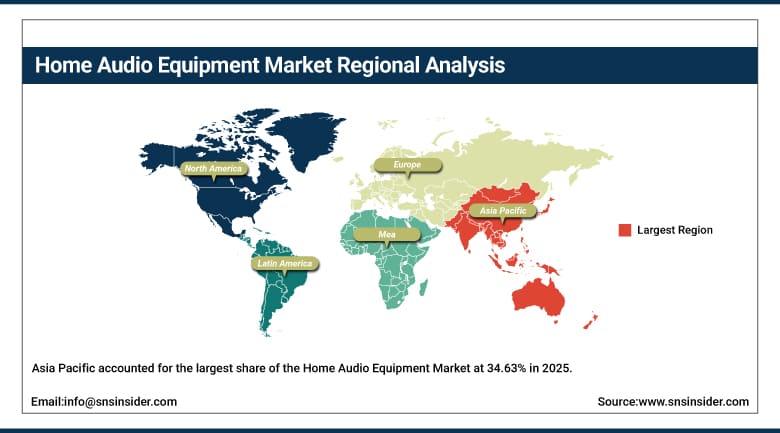
Asia Pacific accounted for the largest share of the Home Audio Equipment Market at 34.63% in 2025 and is also the fastest growing region, with a CAGR of 10.17% during 2026-2035. The region combines large populations, rising household incomes, rapid adoption of streaming services and a strong base of audio and electronics manufacturers. China, Japan, South Korea, India and Australia all contribute, with demand for soundbars and smart speakers growing as housing quality improves. Government support for household consumption and local brands adds momentum in several countries. Improving internet infrastructure supports streaming growth. Growing urbanization raises ownership.
China is the largest country market, with 37.46% of regional demand, supported by a big television base, a strong local brand scene and active online retail. Japan is a mature market with a loyal hi-fi audience, and South Korea is a technology-forward market with major audio brands. India is expanding fast as middle-class households buy larger televisions and pair them with soundbars. Live-streaming commerce is a major sales route, and festivals such as Singles Day create annual peaks. Local brands in China and India compete strongly on price, while Japanese and Korean firms emphasize quality.
⮞The National Bureau of Statistics of China reported on 20 October 2026 that retail sales of home appliances and audio-video equipment rose 1.9% year on year in September 2026 but were down 4.9% for January to September.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Home Audio Equipment Market Insights
North America accounted for approximately 30.41% of the Home Audio Equipment Market in 2025, with the United States contributing about 83.69% of regional demand and Canada the balance. Consumers favor soundbars, smart speakers and premium wireless systems, and the region is the home of several leading audio and platform brands. High streaming use and large televisions boost demand for immersive sound. Large retail chains and online marketplaces together reach almost every household. Seasonal events such as holiday sales and major sports finals produce reliable peaks.
Canada is regarded as the fastest growing country in the region, supported by steady household formation and strong online retail. Mexico, which belongs to Latin America, is an expanding market with a growing middle class. Buyers in the region respond to holiday promotions and to new product launches from established brands, and custom installers serve higher-income households. Specialty hi-fi retailers and custom installers still serve a loyal premium audience. Housing turnover also triggers upgrade spending. Business events and sports bars add commercial demand. Rising spending on outdoor entertaining adds demand for weather-resistant models.
⮞Statistics Canada reported on 23 October 2026 that retail sales rose 1.2% from July to August 2026.
Europe Home Audio Equipment Market Insights
Europe held approximately 25.84% of the Home Audio Equipment Market in 2025, with Germany, the United Kingdom, France, Italy and the Nordic countries leading demand. The region has a heritage of high-end hi-fi, with many respected speaker and amplifier makers, and consumers are willing to pay for design and sound quality. Soundbars and multi-room systems sell widely, and vinyl listening is enjoying a revival. Public service broadcasters and streaming platforms are expanding immersive audio content, which feeds demand. Strong consumer protection rules and clear labeling support trust in branded products. Established distribution through specialist shops sustains premium brands.
Germany is the largest market, with about 24.12% of regional demand, followed by the United Kingdom and France. Retailers range from large electronics chains to specialist shops, and online platforms are expanding. Energy efficiency rules and sustainability expectations influence product design, and manufacturers emphasize repairability, recyclable materials and standby power savings. Premium British, Danish and French brands remain strong exporters, and Nordic households adopt wireless systems early. Small-room living in cities encourages compact wireless solutions. Sustainability labels shape purchasing.
⮞The Office for National Statistics of the United Kingdom reported on 23 October 2026 that retail sales volumes fell 0.4% in September 2026 but were up 0.8% year on year.
MEA & Latin America Home Audio Equipment Market Insights
The Middle East and Africa and Latin America together account for approximately 9.12% of the Home Audio Equipment Market in 2025, with Latin America at 5.72% and the Middle East and Africa at 3.40%. In the Gulf, the United Arab Emirates and Saudi Arabia show demand for premium home theaters and smart home integration in new villas and apartments. South Africa, Egypt and Nigeria are growing markets for affordable speakers and soundbars. Retail expansion by international electronics chains is widening access. Hospitality projects add commercial sales.
Latin America is led by Brazil and Mexico, where large television bases, football viewing and music streaming support steady demand for soundbars and portable speakers. Argentina, Colombia and Chile add smaller volumes. Imports dominate supply, so exchange rates and duties influence shelf prices, and installment payment plans are important in making higher-priced products accessible to consumers. Football tournaments often trigger television and soundbar bundles. Local distributors and installment financing remain essential. Growing online marketplaces are widening the choice available to shoppers in smaller cities.
⮞The Brazilian Institute of Geography and Statistics reported on 15 October 2026 that retail sales of office, informatics and communication equipment rose 6.3% in August 2026, while furniture and appliances fell 4.2%.
Market Dynamics
Growth Drivers: Streaming Adoption and Wireless Smart Speakers Drive Growth in the Home Audio Equipment Market
The popularity of streaming music and video is the strongest force behind the Home Audio Equipment Market. Subscribers listen to more music and watch more films at home, and many feel that built-in television speakers do not do justice to the content. Soundbars, speakers and home theater systems are the simplest way to improve this experience, and platforms increasingly offer high-quality audio formats that need capable equipment. Growth in smart televisions that stream directly also raises awareness of audio quality. Platform exclusives on immersive audio titles give viewers extra reasons to upgrade. The result is a larger installed base of capable speakers.
Wireless connectivity and smart features form the second driver. Voice assistants, multi-room control and simple app setup make speakers more useful and encourage owners to add units across the home. Software updates keep older products relevant, which supports brand loyalty, while new models introduce room calibration and spatial audio. Sound quality that adapts to the room is a persuasive upgrade argument. Competition among platform owners to power the home keeps product development moving quickly. Cross-selling with televisions and phones expands reach.
⮞Eurostat reported on 15 October 2026 that retail trade volume in the European Union rose 4.3% year on year in August 2026.
Restraints: Inflation and Mature Replacement Cycles Restrain Growth in the Home Audio Equipment Market
Inflation and cautious household budgets restrain the Home Audio Equipment Market. Audio equipment is a discretionary purchase, and consumers tend to delay upgrades when prices for food, housing and energy rise. Higher component and logistics costs also squeeze margins, forcing brands to raise prices or reduce features. Promotions are common, which can erode premium positioning. Currency swings further complicate pricing for global brands. Retailers report cautious spending on big-ticket items. Competition from phone-based listening limits spend.
Mature replacement cycles add further pressure. Many households already own a soundbar or smart speaker, and these products last for years, so growth depends on persuading owners to upgrade. Smartphone and headphone listening compete for attention, and television makers keep improving built-in audio. Counterfeit and low-cost products from marketplaces also dilute the market in some regions. Shorter attention spans and a plentiful second-hand market also reduce new unit sales. Product reviews that praise built-in television audio also hold back some buyers. These dynamics encourage brands to emphasize value and durability.
⮞The U.S. Bureau of Labor Statistics reported on 14 October 2026 that consumer prices rose 3.7% over the 12 months to September 2026.
Opportunities: Emerging Market Households and Smart Home Integration Create Opportunities in the Home Audio Equipment Market
Rising household incomes in emerging markets create a large opportunity. Families in India, Southeast Asia, Africa and Latin America are buying larger televisions and want better sound to accompany them. Affordable soundbars, portable speakers and entry-level home theater kits suit these buyers, and local assembly and financing options can widen access further. Governments in several countries are also supporting digital television switchovers that stimulate purchases. Retail expansion into smaller cities supports this trend. Voice assistants are further opening new doors.
Smart home integration is a second opening. Speakers that act as hubs for lighting, security, climate and media control give audio brands a role in broader household ecosystems. Partnerships with platform owners, builders and utilities can place speakers in new homes from the start. Premium customers also value seamless multi-room control and discreet, in-wall designs. Builders and property developers increasingly specify audio as part of smart apartments. Utility and telecom bundles are another channel. Developers value pre-wired systems. Such partnerships create stable, repeat volume for suppliers.
⮞Statistics South Africa reported on 21 October 2026 that retail sales of household furniture, appliances and equipment rose 3.0% year on year in real terms in August 2026.
Recent Developments:
- 2025: LG Electronics and Dolby Laboratories unveiled the LG Sound Suite, led by the H7 soundbar that uses Dolby Atmos FlexConnect and scales to a 13.1.7-channel configuration.
- 2026: Sonos announced the portable Sonos Play speaker, offering up to 24 hours of battery life, an IP67 rating, Wi-Fi and Bluetooth connectivity, and a power bank function.
- 2026: Samsung confirmed U.S. availability of its Music Studio 5 and Music Studio 7 speakers and its 2026 soundbar line, including the Q990H with an 11.1.4-channel configuration.
- 2026: Bose launched its Lifestyle Collection, comprising the Lifestyle Ultra Speaker, a 5.2-channel Ultra Soundbar expandable to 7.1.4, and an Ultra Subwoofer.
Home Audio Equipment Market Key Players are:
-
Sonos, Inc.
-
Bose Corporation
-
Sony Group Corporation
-
Samsung Electronics Co., Ltd.
-
LG Electronics Inc.
-
HARMAN International (JBL, Harman Kardon, Denon, Marantz, Bowers & Wilkins, Polk Audio)
-
Yamaha Corporation
-
Klipsch Audio Technologies
-
Devialet
-
Bang & Olufsen A/S
-
Sennheiser Electronic GmbH & Co. KG
-
KEF Audio
-
Apple Inc.
-
Google LLC
-
Cambridge Audio
-
Focal-JMlab
Home Audio Equipment Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 39.25 Billion |
| Market Size by 2035 | USD 95.33 Billion |
| CAGR | CAGR of 9.28% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Speakers, Soundbars, Home Theater Systems, AV Receivers and Amplifiers, Multi-room Audio Systems, Turntables, and Others) • By Technology (Wireless and Wired) • By Installation (Fixed and Portable) • By Distribution Channel (Offline and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Sonos, Inc., Bose Corporation, Sony Group Corporation, Samsung Electronics Co., Ltd., LG Electronics Inc., HARMAN International (JBL, Harman Kardon, Denon, Marantz, Bowers & Wilkins, Polk Audio), Yamaha Corporation, Klipsch Audio Technologies, Devialet, Bang & Olufsen A/S, Sennheiser Electronic GmbH & Co. KG, KEF Audio, Apple Inc., Google LLC, Cambridge Audio, Focal-JMlab |

Frequently Asked Questions
The key players in the Home Audio Equipment Market include Sonos, Inc., Bose Corporation, Sony Group Corporation, Samsung Electronics Co., Ltd., LG Electronics Inc., among others.
Key opportunities include rising household incomes in emerging markets and smart home integration, where speakers act as hubs for media, lighting and security control.
The major growth factor is the popularity of streaming music and video, which leads households to upgrade from built-in television speakers to soundbars, speakers and home theater systems.
The Speakers segment dominated the Home Audio Equipment Market with approximately 37.64% share in 2025, because the category spans a wide price range and benefits from steady upgrades.
Asia Pacific dominated the Home Audio Equipment Market with a 34.63% share in 2025, supported by large populations, rising incomes and a strong base of audio manufacturers.
