
HVDC Capacitor Market Report Scope & Overview:
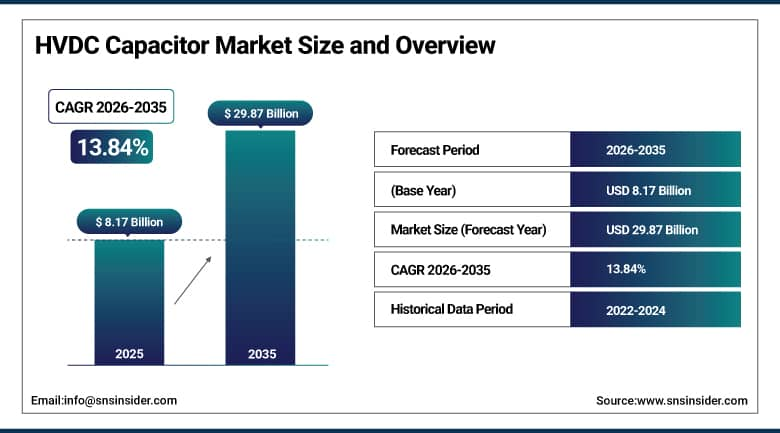
The HVDC Capacitor Market was valued at USD 8.17 Billion in 2025 and is estimated at USD 9.30 Billion in 2026. The market is projected to reach USD 29.87 Billion by 2035, expanding at a CAGR of 13.84% from 2026 to 2035. High voltage direct current capacitors filter harmonics, smooth direct current, and absorb switching surges inside converter stations that move bulk power over long distances and under the sea. Growth is supported by long-distance transmission projects, offshore wind connections, and the shift toward voltage source converters that use compact dry-type capacitors.
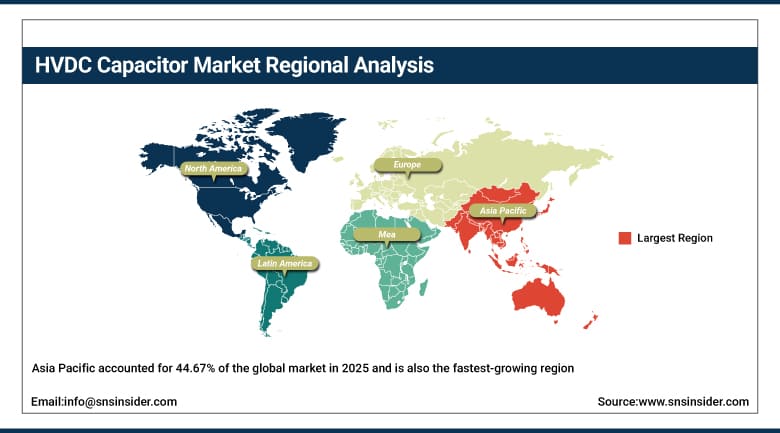
Asia Pacific was the largest regional market in 2025, with a 44.67% share. China operates the largest fleet of ultra high voltage direct current lines in the world and keeps adding new corridors that carry hydro, wind, and solar power to coastal load centers. India has started its own program of 800 kV links, while Japan, South Korea, and Australia add interconnector and offshore projects. Local manufacturers supply a large part of converter station demand, and international suppliers keep plants inside the region to serve these projects with short delivery times.
To Get More Information On HVDC Capacitor Market - Request Free Sample Report
Key Report Takeaways
-
By technology, line-commutated converters held a 53.10% share in 2025, while voltage source converters are the fastest growing.
-
By capacitor type, plastic film capacitors held a 46.50% share in 2025, while aluminum electrolytic capacitors are the fastest growing.
-
By function, DC filter capacitors held a 32.90% share in 2025, while DC link capacitors are the fastest growing.
-
By application, bulk power transmission held a 41.50% share in 2025, while renewable energy integration is the fastest growing.
-
By region, Asia Pacific held a 44.67% share in 2025 and is also the fastest growing.
Market Trends and Insights
Dry-type metallized film capacitors are taking a larger role. Voltage source converters need compact DC link banks that avoid oil handling, and manufacturers are expanding dry-type capacity so that offshore platforms and city-edge converter stations can use lighter, self-healing units with a smaller footprint.
Rated voltages keep rising. Transmission planners are standardizing on 525 kV for offshore and underground links and on 800 kV or higher for overland corridors, which pushes capacitor makers toward larger stacks, better insulation systems, and tighter loss control across the full thermal range.
Condition monitoring is moving into capacitor banks. Sensors track capacitance drift, temperature, and partial discharge so that owners can plan maintenance during outages and extend the life of aging converter stations without waiting for a failure to occur.
Regional manufacturing is expanding. Grid owners prefer suppliers that can build, test, and service capacitors close to the project, and that preference is leading to new plants and local partnerships in China, India, and Europe.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Long-Distance and Ultra High Voltage Transmission Build-Out |
+3.06% |
Asia Pacific, Europe, North America |
Medium term (2 to 4 years) |
|
Offshore Wind and Renewable Integration |
+2.61% |
Europe, Asia Pacific |
Medium term (2 to 4 years) |
|
Shift to Voltage Source Converters |
+2.17% |
Global |
Long term (4 years or more) |
|
Cross-Border Interconnection and Refurbishment of Aging Links |
+1.74% |
Europe, Middle East & Africa, Latin America |
Medium term (2 to 4 years) |
|
Government Grid Investment Programs |
+1.46% |
Asia Pacific, North America |
Short term (2 years or less) |
|
Dielectric Film and Compact Design Advances |
+1.12% |
Global |
Long term (4 years or more) |
Long-Distance and Ultra High Voltage Transmission Build-Out
Moving large blocks of power over more than 1,000 kilometers is cheaper and more stable with direct current, and every converter station at either end needs filter, DC link, and snubber capacitors. Countries with distant generation and dense load centers keep ordering links in the 800 kV class. The International Energy Agency estimates that annual global grid spending must more than double to above USD 600.00 Billion by 2030, with long lines and interconnectors taking a growing share. Each new station adds hundreds of capacitor units to the order book.
Offshore Wind and Renewable Integration
Offshore wind farms located far from the coast rely on direct current export cables, and every offshore and onshore converter platform carries capacitor banks. Solar and wind plants in remote regions also need long links to reach demand. In June 2025, ENTSO-E reported 180 transmission projects with 354 investments and 51 storage projects submitted in the first collection window of its 2026 development plan, and many of these are direct current connections that will require capacitors in coming years. Utilities also value fast delivery.
Shift to Voltage Source Converters
Voltage source converters allow black start, independent control of active and reactive power, and multi-terminal operation, so grid owners now prefer them for offshore, urban, and weak-grid connections. They use compact DC link capacitors and a different filter design from older thyristor stations. The International Electrotechnical Commission published IEC 62501 in April 2024 with updated electrical testing rules for valves used in these converters, which supports consistent design and wider supplier participation across new projects. Suppliers with proven experience gain an edge.
Cross-Border Interconnection and Refurbishment of Aging Links
Neighboring countries are building interconnectors to share reserves and balance variable generation, and subsea and underground direct current cables are the usual choice for long crossings. At the same time, first-generation links from the 1970s and 1980s are reaching the end of their design life, and owners are replacing valves, controls, and capacitors during upgrades. This creates a steady replacement stream beyond the demand from entirely new transmission corridors, and it supports consistent aftermarket orders for suppliers. Suppliers with global service networks hold advantages.
Government Grid Investment Programs
Public planning and funding programs convert energy transition targets into approved grid projects. In June 2026, the National Energy Administration of China said that grid fixed-asset investment will exceed 5 trillion yuan during the 15th Five-Year Plan, a program that includes ultra high voltage direct current corridors. Comparable programs in Europe, India, and Brazil are underwriting converter stations, which gives capacitor suppliers a visible multi-year pipeline of orders. Contract awards usually follow approvals, so suppliers monitor these milestones closely when planning production.
Dielectric Film and Compact Design Advances
Improvements in polypropylene film, metallization patterns, and impregnation fluids raise energy density and lower losses, which allows smaller capacitor units for the same rating. Self-healing dry designs reduce fire and spill risk, while modular racks speed up installation inside valve halls and on offshore platforms. Better thermal design supports higher ripple currents in modern converters. Suppliers that invest in film processing and testing capacity can win larger orders for next-generation stations. These advances also help suppliers meet tighter loss limits.
Restraints Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Long Equipment Lead Times and Project Cycles |
-1.34% |
Global |
Long term (4 years or more) |
|
Raw Material and Component Cost Volatility |
-1.12% |
Global |
Medium term (2 to 4 years) |
|
Stringent Qualification and Reliability Requirements |
-0.93% |
Global |
Medium term (2 to 4 years) |
|
Permitting, Financing, and Policy Uncertainty |
-0.74% |
North America, Europe |
Short term (2 years or less) |
Long Equipment Lead Times and Project Cycles
A direct current link is built over five to fifteen years, and cables, transformers, and valves compete for limited factory slots. Waits for cable systems of more than five years have been reported in some cases, so capacitor orders arrive in large and irregular batches tied to project milestones. Suppliers carry long working capital cycles, and a delay at any one component maker can hold up the entire station. Small capacitor producers have difficulty planning capacity under such lumpy demand, which limits the speed of market expansion.
Raw Material and Component Cost Volatility
Capacitors depend on polypropylene film, aluminum foil, zinc and aluminum metallization, insulating fluids, and ceramic or metal housings, and the prices of these inputs move with energy costs and trade policy. Tariffs on imported aluminum, films, and ceramics add further uncertainty for cross-border supply. Supply contracts for grid projects often run for years at fixed prices, which squeezes margins when input costs rise. Suppliers respond with indexation clauses and local sourcing, though these steps take time to negotiate with utility buyers.
Stringent Qualification and Reliability Requirements
Converter stations are expected to run for forty years or more, and a capacitor failure can force an outage on a link worth billions of dollars. Buyers therefore demand long type tests, factory witness testing, and proven track records before approving a supplier. Qualification of a new design can take several years, which locks in incumbents and slows entry for newer producers. Compliance with partial discharge, endurance, and safety standards adds cost to every product line and limits how quickly innovations can reach commercial projects.
Permitting, Financing, and Policy Uncertainty
Transmission projects need land, environmental, and cost allocation approvals that often take longer than construction. In July 2025, the United States Department of Energy terminated a conditional loan guarantee of up to USD 4.90 Billion for the Grain Belt Express HVDC line, a reminder that financing support can change. Delays and cancellations postpone converter station orders and the capacitor demand that follows, particularly in markets where regional cooperation among states and utilities is needed before a project can proceed. Suppliers therefore watch approvals closely.
HVDC Capacitor Market Segment Analysis
By Technology, Line-Commutated Converters Dominate HVDC Capacitor Market; Voltage Source Converters to Register Fastest Growth.
Line-commutated converters lead because most of the installed HVDC capacity, including the largest overland corridors, uses thyristor valves. These stations accounted for 53.10% of the market in 2025. They need large AC and DC filter banks and sizable oil-impregnated capacitor units, which creates a high volume of orders for each project. Established links also need capacitor replacement and expansion as filters are retuned, so the technology continues to generate dependable demand for suppliers. Utilities keep ordering them for upgrades.
Voltage source converters are projected to expand at a CAGR of 16.12% from 2026 to 2035. They suit offshore wind connections, city infeed, and multi-terminal grids because they can start without grid support and control power flow in both directions. Their stations use compact dry-type DC link capacitors, which raises demand for metallized film units with high ripple current ratings. Standardized 525 kV designs are also speeding approvals and repeat orders from utilities and transmission operators. Offshore developers prefer them.
By Capacitor Type, Plastic Film Capacitors Dominate HVDC Capacitor Market; Aluminum Electrolytic Capacitors to Register Fastest Growth.
Plastic film capacitors hold the leading position, with 46.50% of the market in 2025. Polypropylene film combines low dielectric loss with high voltage endurance, and it can be built into oil-impregnated or dry self-healing units for filters, DC link banks, and snubbers. Converter station designers have long relied on this construction, and its track record helps buyers approve it for critical equipment with service lives of forty years, which keeps replacement and new project orders flowing steadily. Utilities trust them.
Aluminum electrolytic capacitors are forecast to grow at a CAGR of 15.60% over 2026 to 2035. They offer high capacitance in a small volume, which suits energy storage and smoothing duties in power electronics modules and auxiliary converter systems. Growth in modular multilevel converters, where each submodule holds its own capacitor, increases the count of such units per station. Better lifetime and ripple performance are also widening their use in demanding duty cycles. Suppliers keep improving lifetime ratings steadily.
By Function, DC Filter Capacitors Dominate HVDC Capacitor Market; DC Link Capacitors to Register Fastest Growth.
DC filter capacitors accounted for 32.90% of the market in 2025. Every line-commutated and many voltage source stations need filters that remove harmonic currents so that lines and nearby communication systems stay clear of interference. These filters use high voltage capacitor stacks that are large, custom designed, and tested individually, which gives the function the highest value per station. Operators also retune filters as networks change, adding a steady stream of replacement orders. Retuning projects also create spare demand.
DC link capacitors are projected to expand at a CAGR of 15.04% from 2026 to 2035. In voltage source and modular multilevel converters they stabilize the direct current voltage, absorb ripple, and supply energy during switching. Each new offshore platform and flexible link adds many such units, and manufacturers are introducing dry designs with higher energy density and longer service life. Growth in back-to-back stations and multi-terminal projects widens demand for these capacitors further. Operators like compact valve halls.
By Application, Bulk Power Transmission Dominates HVDC Capacitor Market; Renewable Energy Integration to Register Fastest Growth.
Bulk power transmission is the leading application, holding 41.50% of the market in 2025. Long overland lines and subsea links that move thousands of megawatts between regions need large converter stations at each end, and every one carries a full set of capacitor banks. National grid plans in China, India, Europe, and Brazil have placed many such projects in the pipeline, which supports a deep and visible backlog of capacitor orders over the coming years. Utilities keep reinforcing corridors too.
Renewable energy integration is projected to expand at a CAGR of 15.78% from 2026 to 2035. Offshore wind clusters, large solar parks in deserts, and hydro plants far from cities all depend on direct current export links. Offshore platforms need compact converters with dry capacitors, while onshore stations connect remote generation to demand centers. Government targets for renewable capacity are turning these plans into funded projects that create new capacitor demand every year. Reliable component supply matters throughout these projects.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.40% |
|
Europe |
Germany |
31.20% |
|
Asia Pacific |
China |
58.30% |
|
Middle East & Africa |
Saudi Arabia |
34.50% |
|
Latin America |
Brazil |
52.40% |
Asia Pacific HVDC Capacitor Market
Asia Pacific accounted for 44.67% of the global market in 2025 and is also the fastest-growing region, with a projected CAGR of 15.21% from 2026 to 2035. China is the leading country, supported by a large program of ultra high voltage corridors. The ±800 kV Ningxia-Hunan link, 1,634 kilometers long and rated at 8,000 MW, was commissioned in 2025 and shows the scale of current projects. Local manufacturers and international suppliers both operate capacitor plants across the country. Capacity additions continue every year.
India is the next major buyer, with 6,000 MW links at ±800 kV planned to carry renewable power from Gujarat and Rajasthan to load centers in Maharashtra, and its first projects are scheduled for the second half of the decade. Japan, South Korea, and Australia contribute interconnector and offshore wind projects, while Southeast Asian countries study regional power trade. Domestic supply chains are expanding, and international suppliers form partnerships to qualify for these large orders. Regional power trade studies add longer term interest.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America HVDC Capacitor Market
North America held a 22.84% share of the global market in 2025. The United States market was valued at USD 1.59 Billion in 2025 and is projected to grow at a CAGR of 13.47% from 2026 to 2035. The SunZia link, rated at 3,000 MW and 525 kV, has been described as the largest voltage source converter HVDC installation in the country. Large renewable developers and transmission companies are the main buyers of converter station equipment. Developers also sign long supply agreements early.
The Champlain Hudson Power Express, a 1,250 MW link that carries hydropower from Quebec to New York City, entered commercial operation in 2026. Other proposed lines face permitting and financing hurdles, yet the pipeline of merchant and utility projects remains active. Canada contributes through hydropower exports and provincial interconnections, and Mexico plans grid reinforcement. Buyers value local test facilities and service teams, which favors suppliers with regional capacity and long maintenance agreements. Utilities also plan upgrades to existing lines over the coming years.
Europe HVDC Capacitor Market
Europe held a 24.91% share of the global market in 2025, with Germany as the leading country, followed by the United Kingdom, France, and the Netherlands. In October 2025, the Bundesnetzagentur approved the final section of SuedLink, about 76 kilometers long, completing the approvals for two underground 2 GW lines at 525 kV that are due to connect to the grid in 2028. North Sea wind and north-south transfer needs sustain converter station orders. Offshore hubs and onshore reinforcements are scheduled across the decade.
The United Kingdom is building several subsea and onshore reinforcements, and Nordic and Baltic countries are linking their grids with neighbors. In May 2026, EirGrid reported that onshore cable installation for the Celtic Interconnector between Ireland and France was complete. The 700 MW link is typical of the projects driving demand for compact voltage source converter equipment, and European buyers also emphasize low-loss designs, recyclability, and long-term service commitments from suppliers. Equipment makers expect repeat orders as other countries copy this standardized approach.
Latin America HVDC Capacitor Market
Latin America is a smaller regional market, led by Brazil, followed by Chile, Mexico, and Argentina. Brazil has used direct current links for decades to bring hydropower from the Amazon to the southeast. In June 2026, the environmental agency Ibama issued the installation license for the Graca Aranha-Silvania ±800 kV line, about 1,500 kilometers long, crossing Maranhao, Tocantins, and Goias. The project will require a full converter station at each end. Hydropower exports from the Amazon remain central to national planning and investment.
Chile is building the Kimal-Lo Aguirre line to carry solar power from the Atacama desert to Santiago. In February 2026, the National Energy Commission and ministers marked the start of construction on the 1,346 kilometer line, which is due to enter operation in 2029. Mexico and Argentina are studying grid reinforcement, but financing conditions slow decisions. Most capacitor equipment is imported through converter station contractors, who select suppliers through global tenders held in advance. Local content rules also influence the choice of contractors.
Middle East & Africa HVDC Capacitor Market
The Middle East & Africa region holds a smaller share of the market but is expected to grow quickly from a low base. Saudi Arabia and the United Arab Emirates are the main buyers, followed by Egypt and South Africa. In October 2025, the Egypt-Saudi Arabia interconnection, rated at 3,000 MW and ±500 kV over about 1,300 kilometers of overhead line and 23 kilometers of submarine cable, was reported to be roughly 95.00% built, a milestone for regional power trade.
Gulf states are strengthening their links with neighbors and planning renewable export projects, while African countries study long lines that would carry hydropower and solar power across borders. Funding and project preparation are the main constraints, though multilateral lenders are supporting several studies. Most capacitor equipment is imported through contractors, and winning supply contracts usually depends on the converter station package and the ability to provide local service support. Regional utilities are also training engineers to operate and maintain these complex stations.
Competitive Landscape
The HVDC Capacitor Market is moderately concentrated. A small group of global grid equipment suppliers and specialist capacitor makers, including Hitachi Energy, Electronicon, Wuxi CRE, and Flair Electronics, serve converter stations, and several system integrators also build capacitor banks for their own projects. Qualification barriers are high because buyers demand proven reliability, which protects incumbents. Competition rests on dielectric quality, test capability, delivery schedules, and service support.
Suppliers invest in new dry-type production lines, higher voltage ratings, and local manufacturing close to major projects. Partnerships with converter station contractors and framework agreements with transmission operators secure long-term volume. Some firms expand test facilities and condition monitoring offerings to differentiate their products, while system integrators evaluate in-house sourcing.
HVDC Capacitor Market Industry Leaders
1. Hitachi Energy: Wet-type DC filter capacitors and DryDCap dry DC link capacitors for HVDC converter stations, produced at plants including Xi'an.
2. Electronicon: High voltage DC film capacitor series with ratings in the 50 kV range and converter DC link capacitors.
3. Wuxi CRE: Film capacitors for HVDC power transmission and flexible DC link applications.
4. Flair Electronics Wuxi: Dry metallized film DC link support capacitors rated for 7,000 VDC and above, used in flexible HVDC converter valves.
Companies Covered in this Report
-
Hitachi Energy
-
Electronicon
-
Wuxi CRE
-
Flair Electronics Wuxi
Recent Industry Developments
-
October 2025: Hitachi Energy marked the 25th anniversary of its Xi'an capacitor plant, noting that the first phase of its dry-type expansion had tripled dry-type capacity.
-
September 2025: Vishay introduced the MKP1848e automotive grade DC link film capacitor rated from 500 V to 1,300 V.
-
April 2026: KYOCERA AVX introduced FFLK traction-grade DC link film capacitors rated from 900 VDC to 3,800 VDC.
-
June 2026: TDK launched the B25696H series of MKP DC film capacitors rated from 900 VDC to 2,000 VDC for silicon carbide power electronics.
-
June 2026: Siemens Energy and its shipyard partner began supplying electrical technology for the 50Hertz North Sea Connector 2 converter platform of up to 2 GW.
-
August 2026: Wuxi CRE presented DC link film capacitor solutions at PCIM Asia Shenzhen 2026.
-
September 2026: GE Vernova received an order from POWERGRID for 6,000 MW, ±800 kV HVDC terminal stations in India.
Scope and Research Methodology
This study covers the HVDC Capacitor Market, which includes capacitors designed for high voltage direct current converter stations, such as DC filter, DC link, AC filter, snubber, and grading capacitors, built with plastic film, aluminum electrolytic, ceramic, and other dielectrics. The base year is 2025, the forecast period is 2026 to 2035, and all values are expressed in USD. The market is segmented by technology, capacitor type, function, application, and region. Capacitors sold for general power factor correction, automotive inverters, and low voltage industrial drives are excluded, as are valves, transformers, and cables. Replacement and refurbishment sales are counted with new station supply. Capacitors used in static var compensators and conventional alternating current substations are excluded unless installed within a direct current converter station.
The research program combines secondary and primary research. Secondary research draws on company annual reports, investor presentations and filings, regulator and system operator databases, grid development plans, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, procurement leaders, and end-user stakeholders across the value chain, including capacitor makers, converter station contractors, transmission operators, and engineering firms. These conversations validate assumptions, order timing, and pricing. Project pipelines and commissioning schedules are reviewed to confirm demand trends.
Market engineering follows a bottom-up build from converter station counts, capacitor content per station, and supplier revenue, which is cross-checked top-down against grid investment and sector indicators. Triangulation across these views confirms segment and regional estimates. Regional figures are built from project pipelines and procurement data, then adjusted for pricing and regulation. Forecasts consider adoption of voltage source converters, rated voltage trends, permitting timelines, and macroeconomic conditions, and every dataset passes an analyst quality review before it is published. Price trends are tracked by dielectric type and function, and demand is modeled by application and region.
HVDC Capacitor Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 8.17 Billion |
| Market Size by 2035 | USD 29.87 Billion |
| CAGR | CAGR of 13.84% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Line-Commutated Converter and Voltage Source Converter) • By Capacitor Type (Plastic Film, Aluminum Electrolytic, Ceramic, and Others) • By Function (DC Filter, DC Link, AC Filter, Snubber and Grading, and Others) • By Application (Bulk Power Transmission, Renewable Energy Integration, Grid Interconnection, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Hitachi Energy, Electronicon, Wuxi CRE, Flair Electronics Wuxi |

Frequently Asked Questions
The market was valued at USD 8.17 Billion in 2025 and is estimated at USD 9.30 Billion in 2026. It is projected to reach USD 29.87 Billion by 2035.
The market is projected to grow at a CAGR of 13.84% from 2026 to 2035, supported by long-distance transmission, offshore wind connections, and voltage source converter adoption.
Asia Pacific leads, with a 44.67% share in 2025, owing to the large program of ultra high voltage direct current corridors in China and the start of similar projects in India.
Asia Pacific is also the fastest-growing region, with a CAGR of 15.21% from 2026 to 2035, driven by grid investment in China and India.
Line-commutated converters, plastic film capacitors, DC filter capacitors, and bulk power transmission lead their axes. Voltage source converters, aluminum electrolytic capacitors, DC link capacitors, and renewable energy integration grow fastest.
Hitachi Energy, Electronicon, Wuxi CRE, and Flair Electronics Wuxi are among the suppliers active in HVDC capacitors.
Long equipment lead times, raw material cost swings, strict qualification requirements, and permitting and financing uncertainty restrain faster growth.
