
Industrial Sugar Market Report Scope & Overview:
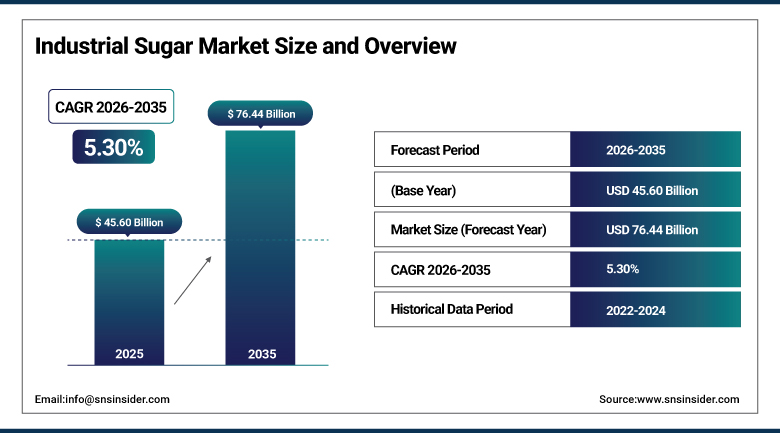
The Industrial Sugar Market was valued at USD 45.60 Billion in 2025 and is expected to reach USD 76.44 Billion by 2035, growing at a CAGR of 5.30% from 2026 to 2035.
Industrial sugar market is experiencing continuous growth as there is a rise in the demand for its usage in the processing of foods & beverages, increased consumption of bakery & confectionery products, and increased application in preservation and stabilization of food on a large scale. Industrial sugar is extracted mainly from sugarcane and sugar beets and serves as a basic raw material in beverages, bakery, confectionery, pharmaceuticals, and animal feed segments as it provides sweetness and is available economically in large quantities. Increasing infrastructure for food processing in developing countries, increased demand for packaged foods driven by urbanization trends, and increased preference for specialty & clean label sugar variants among manufacturers drive the growth potential for this ingredient.
Soft drink, sports drink, and alcoholic beverages represent over one-third of total sugar usage in the industrial sector, given that sugar is an important ingredient in such products despite the shift to specialty sugars being adopted by bakeries and confectioneries in the formulation of their products due to the added functionality of these sugars.
To Get more information Industrial Sugar Market - Request Free Sample Report
Industrial Sugar Market Trends
- Rising demand for specialty and clean-label sugar variants is expanding premium bakery and confectionery formulation adoption.
- Growing beverage industry consumption is driving sustained demand for consistent, large-volume industrial sugar supply.
- Increasing adoption of automated sugar processing and refining technology is improving production efficiency and consistency.
- Expanding food processing infrastructure across emerging economies is broadening industrial sugar procurement and distribution demand.
- Strategic capacity expansions and sustainable sourcing partnerships are strengthening traceable cane and beet sugar supply chains.
The U.S. Industrial Sugar Market Outlook
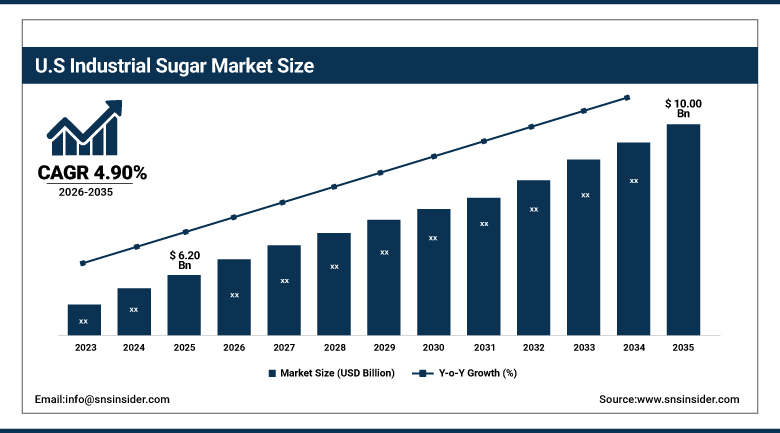
The U.S. Industrial Sugar Market was valued at USD 6.20 Billion in 2025 and is projected to reach USD 10.00 Billion by 2035, growing at a CAGR of 4.90% during 2026–2035.
Major companies in beverages and bakery products sector in the nation are increasingly turning to the use of industrial sugar due to increasing demand for packaged foods and beverages among consumers in the country. Increasing use of different types of specialty and clean-label sugars along with increased use of sugar in the manufacture of pharmaceutical products and candies is expected to drive domestic demand in the future. Increased domestic capacity to refine sugar from sugar beets and sugar cane, along with increased automation by processors, is expected to drive domestic consumption of industrial sugar in the country.
The United States has historically established its place as the largest regional industrial sugar market, mainly due to extensive sugarcane cultivation and expanding food processing infrastructure, while Latin America is registering the fastest regional growth rate as demand accelerates across both beverage and bakery production applications.
Industrial Sugar Market Segment Analysis
- By Type, white sugar dominated the industrial sugar market with a 42.50% share in 2025, while specialty sugar is the fastest-growing type segment with a CAGR of 6.60% from 2026–2035.
- By Form, granulated sugar dominated the industrial sugar market with a 51.15% share in 2025, while powdered sugar is the fastest-growing form segment with a CAGR of 5.90% from 2026–2035.
- By Source, cane sugar dominated the industrial sugar market with a 65.78% share in 2025, while beet sugar is the fastest-growing source segment with a CAGR of 6.30% from 2026–2035.
- By Application, beverages dominated the industrial sugar market with a 37.67% share in 2025, while bakery & confectionery is the fastest-growing application segment with a CAGR of 6.90% from 2026–2035.
By Type, white sugar dominated the industrial sugar market, while specialty sugar is the fastest-growing segment.
White sugar was the leading player in the market in 2025, recording more than 42.50% share due to its cheap price, easy availability, and high versatility across multiple uses in the manufacturing of food and beverages products. Manufacturers use white sugar because of its sweetness levels and its technological advancement, which allows it to fit easily into bulk processing and blending systems; and since there is ongoing investment in refining technologies, manufacturers can ensure that they have high purity levels of white sugar production.
The specialty sugar segment will hold the largest share of the CAGR 6.60% over the period 2018-2035, as the demand for clean-label and minimally processed types of sugar increases due to their inclusion in high-value bakery and confectionery products. Increasing preference of consumers for more naturally-sourced sugars has compelled food producers to produce specialty sugar segments like demerara sugar, turbinado sugar, and organic cane sugar, amongst others.
By Form, granulated sugar dominated the industrial sugar market, while powdered sugar is the fastest-growing segment.
Granulated sugar had the maximum market share in 2025 of above 51.15%, owing to its wide application in beverage, bakery, and confectionary industries due to its convenient nature to handle and store as well as its suitability with standard industrial mixing machines. The food industry prefers granulated sugar because of its definite particle size and dissolution properties; and growing bulk availability and efficient distribution channels further consolidate the dominance of the product in the industrial sugar form category.
Powdered sugar is expected to grow at the fastest CAGR of 5.90% during the forecast period, supported by increasing demand for fine-particle sugar in icing, confectionery coating, and premium bakery decoration applications. Growing consumer preference for visually refined bakery and dessert products is prompting manufacturers to expand powdered sugar production capacity, while advances in milling and anti-caking technology continue to accelerate segment growth across specialty bakery and confectionery categories worldwide.
By Source, cane sugar dominated the industrial sugar market, while beet sugar is the fastest-growing segment.
The dominant source in the market was cane sugar, with a share of 65.78%, which could be attributed to the widespread growing of sugarcane in the major producers, such as Brazil, India, and Thailand, backed by advanced technology in processing and refining the product. The preference of the industry for cane sugar is due to the cost-effective production of the commodity and its availability, with technological advancements in processing the cane further consolidating cane sugar's dominance in the industrial sugar market.
The market for beet sugar is forecast to experience the fastest growth rate of 6.30% till 2035 due to the rising cultivation of beets in temperate zones such as Europe and North America where climatic factors are more conducive to beet than cane farming. The growing interest among manufacturers in diversification of materials to mitigate risks related to cane prices will lead to investments in beet sugar refining.
By Application, beverages dominated the industrial sugar market, while bakery & confectionery is the fastest-growing segment.
The largest market share, amounting to more than 37.67%, belonged to the beverages segment owing to continuous demand from soft drinks, sports drinks, and alcoholic beverages that require regular availability of huge quantities of sugar for the manufacture of such beverages. The continuously increasing preference of millennial and young consumers for flavored and functional beverages in Asian countries and emerging economies has been contributing to the continued strength of the beverages segment, besides growing beverage manufacturing capabilities in emerging economies.
Bakery & confectionery is expected to grow at the fastest CAGR of 6.90% during the forecast period, supported by rising global demand for packaged bakery products, confections, and desserts across both developed and emerging markets. Growing consumer preference for premium and specialty baked goods is prompting manufacturers to expand sugar procurement for bakery formulation, further accelerating segment growth across the global processed food and confectionery ingredient market.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Germany |
24.00% |
|
Asia Pacific |
China |
38.00% |
|
Middle East & Africa |
UAE |
20.00% |
|
Latin America |
Brazil |
55.00% |
North America Industrial Sugar Market Insights
North America is a significant region in the industrial sugar market, supported by extensive beverage and bakery manufacturing infrastructure, established beet sugar refining capacity, and strong consumer demand for packaged food and confectionery products across the region.
The United States was the dominant player in the North America industrial sugar market in 2025, owing to the presence of large production capacities of beverages and increasing consumer preference for packaged baked goods and confectioneries. Canada is supporting the region’s growth by way of its rapidly developing beet sugar refining industry and investments in food processing facilities.
Europe Industrial Sugar Market Insights
The Europe industrial sugar market was a significant contributor in 2025, attributed to the region's strong beet sugar cultivation base, established food regulatory frameworks, and growing consumer demand for clean-label, sustainably sourced sugar ingredients across member states.
Germany is one of the major markets in Europe owing to its strong beet sugar processing base and growing consumer demand for specialty, sustainably sourced sugar variants. Other countries such as France and Poland are also contributing to market growth through extensive beet cultivation and refining capacity.
Asia Pacific Industrial Sugar Market Insights
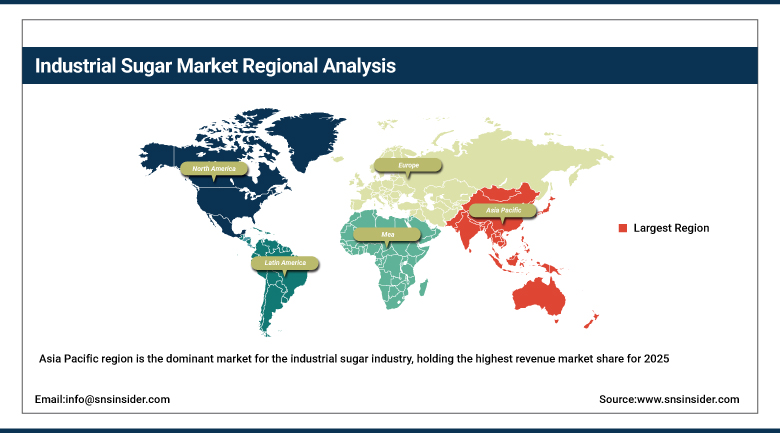
The Asia Pacific region is the dominant market for the industrial sugar industry, holding the highest revenue market share for 2025. China and India are key manufacturers and consumers of industrial sugar, backed by large areas of sugarcane production and growing food processing capacity due to favorable agricultural policy by the government.
China ranks among the major growth markets of the Asia Pacific industrial sugar market on account of growing food and beverages manufacturing facilities and large processing capacity domestically. India and Thailand are helping fuel regional growth through growing cane production and growing sugar refining and export capabilities.
Get Customized Report as per Your Business Requirement - Enquiry Now
Middle East & Africa and Latin America Industrial Sugar Market Insights
Middle East & Africa and Latin American regions continue to expand industrial sugar production and consumption as food processing and beverage manufacturing investment grows across both regions, supported by favorable sugarcane cultivation conditions and expanding export infrastructure.
Brazil is the fastest growing and leading Latin America country due to its status as the world's leading producer of sugarcane and rising capacity to export processed foods and beverages. The MEA region comprises the UAE and Saudi Arabia that have established state-of-the-art food processing facilities resulting in increased demand for industrial sugar within their growing industries.
Market Dynamics
Growth Drivers: Rising processed food demand and beverage manufacturing expansion driving market growth
Increasing demand for processed and packaged food products, combined with rising urbanization and changing dietary patterns, are among the primary drivers of the industrial sugar market. Growing middle-class disposable income across developing economies continues to push consumption of convenience foods and beverages containing sugar as a primary ingredient, while expanding food processing industries in emerging markets further reinforce long-term structural demand for industrial sugar across multiple end-use sectors worldwide.
The industry is being driven by expanding applications in pharmaceuticals, cosmetics, and bioplastics, where industrial sugar serves as a functional excipient and feedstock alongside its traditional food and beverage uses. Growing beverage industry demand for consistent, large-scale sugar supply, combined with manufacturers' continued investment in refining efficiency and automated processing technology, are further supporting demand across the forecast period.
Restraints: Rising health concerns and raw material price volatility limiting market expansion
One of the factors that acts as a barrier to market growth is rising consumer health concerns regarding excessive sugar consumption, prompting regulatory sugar taxes and reformulation mandates across several major markets that can restrict industrial sugar usage in price-sensitive and health-conscious food and beverage segments.
Furthermore, changing costs of raw materials due to variations in weather conditions that affect the harvest of sugarcane and sugar beets keep contributing to cost variability that can pose restrictions on margins for manufacturers. The government mandate regarding biofuels, which results in diversion of cane to make ethanol in countries like Brazil and India, also restricts availability of sugar.
Opportunities: Expansion into bio-based alternatives and specialty sugar blends creating new growth avenues
The market is witnessing new growth avenues driven by increasing manufacturer investment in bio-based sugar alternatives and customized sugar blends tailored for specific industrial applications, addressing rising demand for differentiated, functional sweetening solutions across premium food and beverage product categories.
There is considerable growth opportunity in expanding industrial sugar penetration across emerging pharmaceutical and cosmetics applications requiring high-purity, specialized sugar grades. Continued investment in automated sugar processing technology and sustainable, traceable sourcing infrastructure is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: Cargill expanded its sugar refining capacity to support growing beverage industry demand for consistent, large-scale supply across key regional markets.
- 2025: Nordzucker invested in a new specialty sugar production line for clean-label bakery and confectionery applications.
- 2026: EID Parry launched an expanded beet sugar sourcing initiative to diversify raw material supply amid cane price volatility.
- 2026: AB Sugar, the sugar division of Associated British Foods, commissioned a processing facility upgrade integrating automated refining technology.
Industrial Sugar Market key players are:
- Cargill, Incorporated
- Nordzucker AG
- EID Parry (India) Limited
- Südzucker AG
- American Crystal Sugar Company
- Associated British Foods plc (AB Sugar)
- Tereos S.A.
- Wilmar International Limited
- Mitr Phol Sugar Corporation
- COFCO Sugar Holding Co., Ltd.
- Louis Dreyfus Company B.V.
- Imperial Sugar Company
- Domino Foods, Inc.
- Bunge Limited
- Sucden (Sucres et Denrées)
- Thai Roong Ruang Sugar Group
- Shree Renuka Sugars Limited
- Rana Sugars Limited
- Balrampur Chini Mills Limited
- Al Khaleej Sugar Co. LLC
Industrial Sugar Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 45.60 Billion |
| Market Size by 2035 | USD 76.44 Billion |
| CAGR | CAGR of 5.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (White Sugar, Brown Sugar, Specialty Sugar) • By Form (Granulated Sugar, Powdered Sugar, Liquid Sugar) • By Source (Cane Sugar, Beet Sugar) • By Application (Beverages, Bakery & Confectionery, Pharmaceuticals, Animal Feed, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Cargill, Incorporated, Nordzucker AG, EID Parry (India) Limited, Südzucker AG, American Crystal Sugar Company, Associated British Foods plc (AB Sugar), Tereos S.A., Wilmar International Limited, Mitr Phol Sugar Corporation, COFCO Sugar Holding Co., Ltd., Louis Dreyfus Company B.V., Imperial Sugar Company, Domino Foods, Inc., Bunge Limited, Sucden (Sucres et Denrées), Thai Roong Ruang Sugar Group, Shree Renuka Sugars Limited, Rana Sugars Limited, Balrampur Chini Mills Limited, Al Khaleej Sugar Co. LLC. |

Frequently Asked Questions
The Industrial Sugar Market is expected to grow at a CAGR of 5.30% from 2026 to 2035.
The Industrial Sugar Market was valued at USD 45.60 Billion in 2025.
The market is driven by rising demand for processed and packaged food products and increasing consumption of beverages, bakery, and confectionery items requiring consistent industrial sugar supply.
The Beverages segment dominated the Industrial Sugar Market in 2025, accounting for more than 37.67% market share.
The Asia Pacific region dominated the Industrial Sugar Market in 2025, accounting for the largest share of total revenue.
