
Liquid Handling System Market Report Scope & Overview:
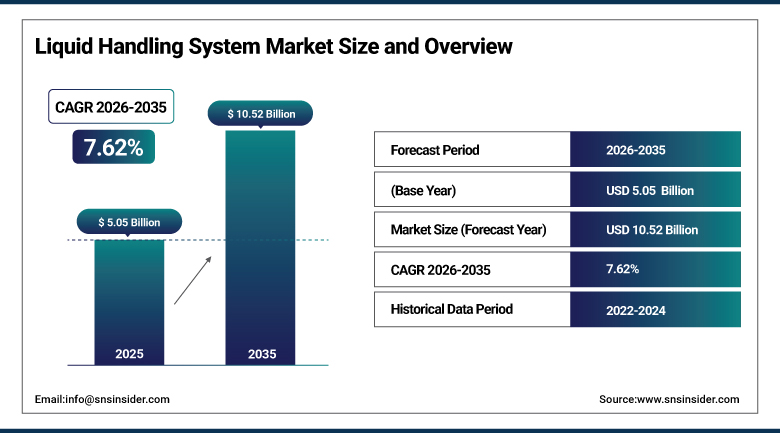
The Liquid Handling System Market was valued at USD 5.05 Billion in 2025 and is expected to reach USD 10.52 Billion by 2035, growing at a CAGR of 7.62% from 2026-2035.
The Liquid Handling System Market is expanding as laboratories automate pipetting to handle more samples with fewer errors. Drug discovery, genomic sequencing, diagnostics and cell therapy workflows all depend on precise transfer of small volumes. Automated workstations are replacing manual pipetting in high-volume labs. Electronic pipettes and benchtop robots bring automation to smaller teams. Miniaturized assays cut reagent cost, and acoustic and low-volume dispensers support that shift. Software now schedules runs and records every step for audit. Budget pressure in academic research can slow orders, yet pharmaceutical and biotechnology demand remains firm. The market is expected to grow as screening and genomic workloads rise.
⮞In February 2026, INTEGRA Biosciences reported that its 2025 sales rose about 3% on a currency-adjusted basis, supported by new pipetting and magnetic bead products. The result shows steady demand for liquid handling tools even in a cautious laboratory spending climate.
To Get more information Liquid Handling System Market - Request Free Sample Report
Liquid Handling System Market Trends
-
Benchtop automated liquid handlers bringing robotics to small and mid-sized laboratories
-
Automated library preparation workflows for next-generation sequencing
-
Low-volume and acoustic dispensing that reduces reagent consumption
-
Cell and gene therapy manufacturing creating new automation demand
-
Cloud software and compliance-ready controls for regulated laboratories
U.S. Liquid Handling System Market Outlook
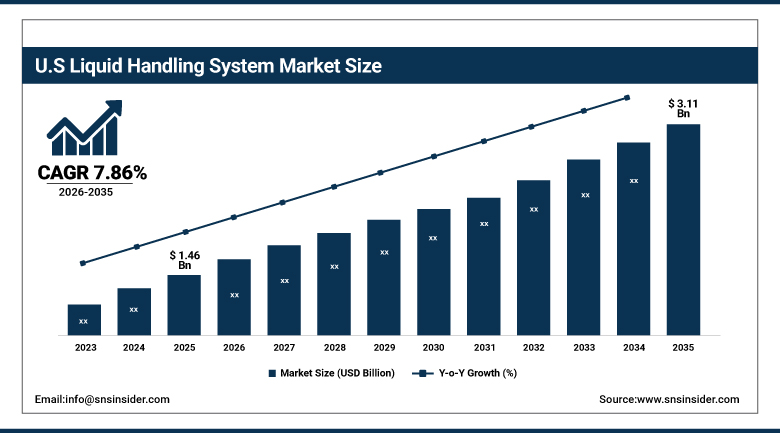
The U.S. Liquid Handling System Market was valued at USD 1.46 Billion in 2025 and is expected to reach USD 3.11 Billion by 2035, growing at a CAGR of 7.86% from 2026-2035.
The U.S. Liquid Handling System Market is the largest national market, supported by a dense base of pharmaceutical, biotechnology and academic laboratories. Drug developers use automated workstations for screening, assay development and sequencing preparation. Federal research funding sets the pace of purchases at universities and institutes. Contract research organizations add steady demand for high-throughput systems. Clinical laboratories automate sample preparation to handle larger test volumes. Venture-backed life science firms favor flexible benchtop robots. Grant uncertainty and long service contracts can delay replacement cycles. Reagent rental contracts are also common in this segment. Instrument makers with local service teams hold an advantage in this market. Growth is expected to remain steady as drug developers expand screening capacity and sequencing volumes.
⮞In February 2026, the Society for Neuroscience reported that Congress passed fiscal year 2026 funding with a National Institutes of Health base budget of USD 47.2 billion, up USD 415 million. The funding level supports continued purchases of laboratory automation at U.S. research institutions.
Liquid Handling System Market Segment Analysis
-
By Type, the Automated segment dominated the Liquid Handling System Market with approximately 48.73% share in 2025 and is also the fastest growing with a CAGR of approximately 9.40%.
-
By Product, the Automated Workstations segment dominated the Liquid Handling System Market with approximately 33.75% share in 2025, while the Pipettes segment is the fastest growing with a CAGR of approximately 8.92%.
-
By Application, the Drug Discovery segment dominated the Liquid Handling System Market with approximately 40.37% share in 2025, while the Cell and Gene Therapy segment is the fastest growing with a CAGR of approximately 11.47%.
-
By End User, the Pharmaceutical and Biotechnology Companies segment dominated the Liquid Handling System Market with approximately 43.88% share in 2025, while the CROs and CMOs segment is the fastest growing with a CAGR of approximately 10.71%.
By Type, Automated Dominates the Liquid Handling System Market and Is Also the Fastest Growing
Automated systems lead because laboratories need consistent results at high sample volumes. Robotic platforms load plates, move liquids and track samples without constant supervision, which frees staff for analysis. Pharmaceutical and sequencing labs run assays that would be impractical by hand. Reproducibility matters for regulated work, and automation reduces variation between operators. Falling prices of benchtop robots now make automation affordable for smaller laboratories. Service networks, validated methods and links to laboratory software support further adoption, which sustains the segment's leading share over manual and semi-automated tools. Pharmaceutical quality systems also favor documented, repeatable processes.
Automated systems are also the fastest growing type as new platforms target midsized labs. Compact instruments with open deck layouts and ready-made protocols cut setup time, and software lets scientists build methods without programming. Integration with plate readers, incubators and sequencers allows full workflows to run overnight. Labs facing staffing limits value this capacity. Manual pipettes and semi-automated tools remain important for low-volume work, teaching and flexible tasks, but electronic features and connectivity are gradually moving buyers toward automation for repeat work. Vendors also offer upgrade paths so labs can add modules over time.
⮞In December 2025, Beckman Coulter Life Sciences stated that its Biomek i3 benchtop liquid handler offers an eight-channel tool for 1 to 1,000 microliters and a deck with 15 standard and 5 flex positions. The design targets laboratories moving from manual work to automation.
By Product, Automated Workstations Dominates the Liquid Handling System Market and Pipettes Grows Fastest
Automated workstations lead because they combine pipetting heads, deck space and software in one platform. Drug discovery groups use them for plate replication, serial dilution and assay setup, and genomics labs use them for library preparation. Buyers prefer systems that can be reconfigured as projects change. High unit prices give workstations a large share of value even though pipettes sell in far greater numbers. Vendors also earn recurring revenue from service contracts, tips and software upgrades, which strengthens the position of this product group. Standard plate formats let labs reuse tips and labware across projects.
Pipettes are growing fastest because electronic models are replacing mechanical ones in routine work. Programmable pipettes reduce repetitive strain, record volumes and connect to laboratory records. Multichannel versions speed plate work, and ergonomic designs improve comfort. Dispensers, burettes and consumables such as tips and plates support every workflow and generate repeat sales. Low-volume and acoustic dispensers are gaining use in miniaturized assays. Quality rules in clinical and pharmaceutical labs encourage calibrated, traceable tools, and replacement of aging pipette fleets adds volume. Labs also buy pipette management software to schedule calibration.
⮞In March 2026, Mettler-Toledo launched the Rainin Vero electronic pipettes in one, eight and twelve-channel formats, with single-channel ranges from 0.5 to 1,000 microliters. The range shows manufacturers extending electronic features to routine laboratory work.
By Application, Drug Discovery Dominates the Liquid Handling System Market and Cell and Gene Therapy Grows Fastest
Drug discovery leads because screening programs test thousands of compounds against biological targets. Automated systems prepare plates, add reagents and transfer samples with exact volumes, which makes results reliable. Miniaturized assays reduce the amount of costly reagent used per test. Biotechnology start-ups and large pharmaceutical groups both invest in automation to speed lead selection. Regulators are also encouraging non-animal testing methods, which depend on cell-based assays and organ models that need precise liquid handling. These factors keep drug discovery the largest application. Collaboration between pharmaceutical groups and academic centers adds further screening work.
Cell and gene therapy is growing fastest as manufacturers scale from research batches to commercial supply. Production steps such as cell seeding, media exchange and formulation need sterile, repeatable handling. Closed automated systems reduce contamination risk and operator time. Clinical diagnostics, genomics and proteomics remain large users, with sequencing library preparation a key workload. Growth in these fields adds demand for low-volume dispensers and workstations. Forensic, environmental and food testing laboratories add smaller but steady volumes as they adopt automated sample preparation. Public health laboratories also add demand during outbreak response.
⮞In January 2026, the Alliance for Regenerative Medicine reported that cell and gene therapy financing reached USD 11.1 billion across 216 financings in 2025. The investment level shows the capital flowing into therapy development that relies on automated handling.
By End User, Pharmaceutical and Biotechnology Companies Dominates the Liquid Handling System Market and CROs and CMOs Grows Fastest
Pharmaceutical and biotechnology companies lead because they run the largest screening, assay development and quality programs. They have budgets for integrated robotic systems and employ specialists to operate them. Pipeline expansion and the need to shorten discovery timelines keep capital spending steady. Companies also standardize methods across sites, which favors a small group of trusted vendors. Service agreements and software add recurring revenue for suppliers. The scale of their operations makes this group the main buyer of both workstations and consumables. Global procurement contracts further concentrate purchases among a few suppliers.
Contract research and manufacturing organizations are growing fastest as drug developers outsource more work. These providers must run many client projects in parallel, so they buy flexible automation that can switch between assays. Academic and research institutes remain a large user group but face budget pressure, and clinical laboratories use automation for high test volumes. Core facilities share instruments among many research teams. Providers that offer financing, rental and application support are well placed to serve these varied buyers. Training and application support strongly influence repeat purchases.
⮞In February 2026, Charles River Laboratories reported fiscal 2025 revenue of USD 4.02 billion, including USD 2.40 billion from its discovery and safety assessment segment. The scale shows the size of the outsourced research market served by automation.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
70.01 |
|
Europe |
Germany |
27.52 |
|
Asia Pacific |
China |
34.38 |
|
Latin America |
Brazil |
48.65 |
|
Middle East & Africa |
Saudi Arabia |
26.34 |
North America Liquid Handling System Market Insights
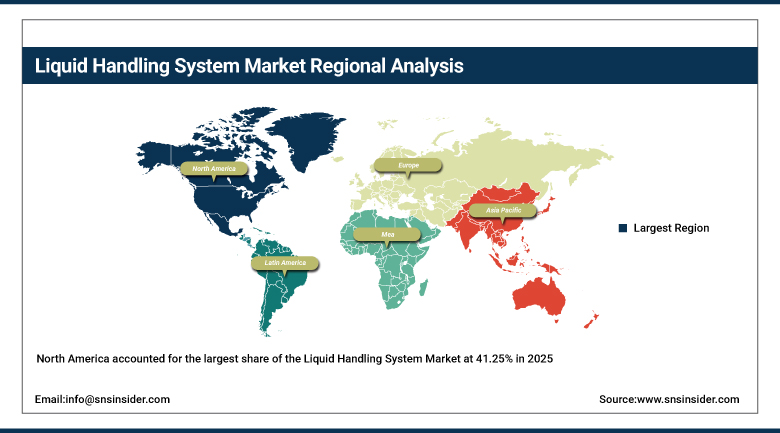
North America accounted for the largest share of the Liquid Handling System Market at 41.25% in 2025, led by the United States. The region hosts a dense cluster of drug developers, genomics companies and research universities, and many leading suppliers such as Hamilton, Beckman Coulter, Opentrons and Revvity serve it directly. Spending is driven by sequencing, cell therapy and screening programs. Canada adds demand through university research and a growing biotechnology sector in Ontario, Quebec and British Columbia. Mexico adds demand through contract manufacturing and clinical laboratories.
Funding and regulation shape purchasing. Federal research budgets decide how much academic laboratories can spend, and recent grant uncertainty has slowed some orders. Clinical laboratories weigh Food and Drug Administration oversight of laboratory developed tests, which has been in flux. Contract research organizations and biotechnology firms continue to invest in benchtop robots, and vendors are adding compliance-ready software and remote service to meet quality demands. Hospital systems in the region are also consolidating laboratory networks, which favors high-throughput platforms. Large systems also standardize on one platform to simplify training.
⮞In September 2025, the American Hospital Association reported that the FDA rescinded its 2024 rule applying device regulation to laboratory developed tests. The reversal removes a compliance cost for clinical laboratories planning automation.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Liquid Handling System Market Insights
Europe is the second largest region and is led by Germany, the United Kingdom, France, Italy and Spain. The region is home to major instrument makers such as Tecan, Eppendorf, Analytik Jena, BRAND and INTEGRA, which supports research, manufacturing and export. Pharmaceutical groups in Switzerland, Germany and the United Kingdom run large screening programs. Universities and public research institutes buy pipettes and workstations through national and European Union funding schemes. Cross-border research programs also create demand for standardized, shareable methods.
In vitro diagnostic regulation shapes the clinical segment, since instruments used for patient testing need conformity marking under European rules. Procurement is often by tender, which favors established suppliers with service coverage. Sustainability goals are increasing interest in reduced plastic use and lower reagent volumes. Germany leads in sales volume, while the United Kingdom and the Nordic countries show strong growth in genomics. Currency changes and cautious academic budgets can affect order timing. Suppliers also compete on service response time and local application scientists.
⮞In 2026, the European Federation of Pharmaceutical Industries and Associations reported that the sector invested an estimated EUR 60.0 billion in research and development in Europe in 2025. The spending supports continued demand for screening and laboratory automation.
Asia Pacific Liquid Handling System Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 9.34% during 2026-2035. China, Japan, India, South Korea and Australia lead regional demand. Government programs are funding biotechnology parks, genomics centers and local drug development, and rapid growth in clinical trials is adding laboratory capacity. Local manufacturers offer lower-priced pipettes and workstations, while global suppliers expand sales and service teams. Japan and South Korea are mature markets with strong demand for high-precision instruments. Australia adds demand through genomics centers and medical research institutes.
India and Southeast Asia are building contract research and manufacturing capacity, which creates demand for flexible automation. Training and service coverage are still limited outside major cities, and price sensitivity favors manual and semi-automated tools in smaller labs. Governments are funding autonomous laboratories and artificial intelligence in drug discovery. Regional distributors play a large role in sales, and international suppliers are forming partnerships to reach hospitals and universities. Rapid expansion of private hospital chains adds demand for automated clinical laboratories.
⮞In June 2026, South Korea's Ministry of Science and ICT announced 49.5 billion won in funding through 2028 for an AI-native autonomous laboratory project under its drug development mission. The program signals state support for automated laboratory infrastructure.
MEA & Latin America Liquid Handling System Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Colombia. Clinical trials and local pharmaceutical production are increasing laboratory investment, and public universities add steady demand for pipettes and consumables. Many buyers rely on distributors for import, service and training. Currency swings and import duties can raise instrument prices, so manual and semi-automated tools remain common. Local assembly and training programs would help suppliers reduce delivery times. Argentina and Brazil are building clinical research capacity that favors automated sample handling. Mexico is adding contract manufacturing and diagnostic capacity.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Israel and South Africa lead demand. Saudi Arabia has launched a national biotechnology strategy that targets large growth in specialized jobs, and Gulf states are building genomics and diagnostics centers. In Africa, public health laboratories are the main buyers, supported by donor programs for disease testing. Limited technical staff and service networks restrain adoption, though regional distributors are expanding training. Universities in Saudi Arabia and South Africa are building core facilities that share automated platforms.
⮞In May 2026, the Argentine government announced that the national pharmaceutical chamber pledged USD 8 billion over six years for clinical research in Argentina. The commitment points to growing laboratory demand in Latin America.
Market Dynamics
Growth Drivers: Drug Discovery Investment and Genomic Workloads Drive Growth in the Liquid Handling System Market
Drug discovery investment is the main source of demand. Screening programs, assay development and lead optimization require thousands of precise transfers each day, which manual work cannot sustain. Drug developers also use miniaturized assays to cut reagent cost, and low-volume dispensers support that practice. Biotechnology funding and large pharmaceutical pipelines keep new laboratories opening. Outsourcing to contract research partners adds further volume, and academic spin-outs create new small buyers of pipetting tools. Regulators are encouraging cell-based and organ-model testing, which relies on accurate, repeatable liquid handling.
Genomic workloads and technology advances add momentum. Sequencing library preparation is a repetitive task well suited to automation, and clinical genomics is growing quickly. Robotics, acoustic dispensing and software scheduling improve throughput and reduce errors. Vendors are offering ready-to-run protocols with reagent kit makers, which lowers adoption barriers. Cell and gene therapy production, diagnostics growth and the need for traceable records in regulated laboratories further raise demand for automated systems. Each new application increases the number of workflows that benefit from reliable transfer, and suppliers respond with dedicated modules.
⮞In 2026, the U.S. Food and Drug Administration reported that its drug center approved 46 novel drugs in 2025. The approvals reflect the steady output of discovery and development programs that use liquid handling equipment.
Restraints: High Capital Cost and Research Funding Pressure Restrain Growth in the Liquid Handling System Market
Costly installation and process complexity act as deterrents. Automated workstations can be priced at hundreds of thousands of dollars, and the user also pays for the service, software, and training. The maintenance, upgrades, and training costs make up a significant portion of total ownership cost. Small laboratories do not have the expertise in their engineering department to program and maintain robotic systems. Longer procurement times for precision consumables can cause disruptions, while cross contamination problems in some dispensing technologies require special care in method development. Automation engineers are in short supply, making the salaries and training costs of laboratories using complex methods more expensive.
Research funding issues further constrain the market. The laboratories are reliant on grants from the government. The low success rates of grant applications delay purchases. The uncertainty regarding the rules on indirect costs and budgeting practices makes the organization cautious. The tariffs and fluctuations in currency rates increase the import costs in several countries. Developing countries suffer due to poor service infrastructures and smaller budgets, which make them use manual tools. Some customers keep their old systems for long periods, causing longer replacement cycles and slower growth in revenues of suppliers.
⮞In April 2026, the Congressional Research Service reported that the National Institutes of Health research project grant success rate fell from 19% in fiscal 2024 to 13% in fiscal 2025. The decline shows the funding pressure facing academic buyers.
Opportunities: Workflow Partnerships and Compliance-Ready Software Create Opportunities in the Liquid Handling System Market
Collaborative relationships with instrument makers and reagent manufacturers represent lucrative business opportunities. Library prep, cell culture and test setups with proven procedures allow for less work when automating. Labs lacking automation experts require easy to use instruments, while manufacturers can charge money for assistance and software. The introduction of bench-top and beginner level automation tools increases customers to smaller labs and educational facilities. Subscriptions and rental schemes reduce initial costs and ensure repeat purchases. Software solutions making development of methods simpler can be another opportunity for broadening the customer base with researchers having no programming skills.
Software and applications represent additional market prospects. Regulatory requirements-compliant monitoring, tracking and cloud scheduling enable regulated labs to introduce automation safely. Cell and gene therapy manufacturing, point-of-care diagnostics and non-animal testing techniques all require precise operation of small volumes of liquid. Up-and-coming markets in Asia Pacific, Latin America and Middle East are developing their research and clinical capabilities. Local assembly and collaborations with regional distribution partners can facilitate sales and increase availability for foreign companies. Regional training centers will train and retain new customers and decrease the likelihood of instrument idleness.
⮞In March 2026, Hamilton announced a partnership with Takara Bio USA to automate its SMART-Seq mRNA LP library preparation on the Microlab STAR platform. The agreement shows how method partnerships lower the barrier to automation.
Recent Developments:
-
In January 2025, Tecan launched Veya, a liquid handling platform that covers volumes from 1 microliter to 5 milliliters and includes analytics software. The system is designed for IVDR compliance and targets laboratories that want scalable, digital workflows.
-
In January 2025, Opentrons launched the Flex High Throughput NGS Workstation for hands-free library preparation of 96 or more samples. The system is priced under USD 100,000, which lowers the entry cost for genomics laboratories.
-
In April 2025, Revvity announced automated methods for all Watchmaker DNA and RNA library preparation kits on its Sciclone G3 NGSx workstation. The methods process up to 96 samples per run and cover low-input and FFPE samples.
-
In February 2026, Gilson announced the PIPETMAX 278, which joins the PIPETMAX 268 as an application-configured system for qPCR, NGS and bioassay workflows. The launch gives laboratories ready-to-run configurations that shorten setup.
Liquid Handling System Market Key Players
-
Tecan Group Ltd.
-
Hamilton Company
-
Beckman Coulter Life Sciences (Danaher)
-
Thermo Fisher Scientific Inc.
-
Eppendorf SE
-
Agilent Technologies, Inc.
-
Revvity, Inc.
-
Mettler-Toledo International Inc. (Rainin)
-
Gilson, Inc.
-
Opentrons Labworks, Inc.
-
SPT Labtech Ltd.
-
Analytik Jena GmbH+Co. KG
-
INTEGRA Biosciences AG
-
BRAND GmbH + CO KG
-
DISPENDIX GmbH
-
Formulatrix, Inc.
Liquid Handling System Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.05 Billion |
| Market Size by 2035 | USD 10.52 Billion |
| CAGR | CAGR of 7.62% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Automated, Semi-Automated, and Manual) • By Product (Automated Workstations, Pipettes, Dispensers, Consumables, and Others) • By Application (Drug Discovery, Cell and Gene Therapy, Clinical Diagnostics, Genomics and Proteomics, and Others) • By End User (Pharmaceutical and Biotechnology Companies, CROs and CMOs, Academic and Research Institutes, Clinical Laboratories, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Tecan Group Ltd., Hamilton Company, Beckman Coulter Life Sciences (Danaher), Thermo Fisher Scientific Inc., Eppendorf SE, Agilent Technologies, Inc., Revvity, Inc., Mettler-Toledo International Inc. (Rainin), Gilson, Inc., Opentrons Labworks, Inc., SPT Labtech Ltd., Analytik Jena GmbH+Co. KG, INTEGRA Biosciences AG, BRAND GmbH + CO KG, DISPENDIX GmbH, Formulatrix, Inc. |

Frequently Asked Questions
Key players include Tecan Group, Hamilton Company, Beckman Coulter Life Sciences, Thermo Fisher Scientific, Eppendorf, Agilent Technologies, Revvity, Mettler-Toledo, Gilson, Opentrons, SPT Labtech, Analytik Jena, INTEGRA Biosciences, BRAND, DISPENDIX and Formulatrix.
Key opportunities include benchtop automation for smaller laboratories, validated workflows for genomics, cell and gene therapy manufacturing, and compliance-ready software.
Rising drug discovery investment and sequencing workloads, together with the need for accurate, reproducible sample handling, are the main growth factors.
By Type, the Automated segment dominated the market in 2025 with an estimated 48.73% share, supported by demand for consistent results at high sample volumes.
North America dominated the market with a share of 41.25% in 2025, driven by a dense base of drug developers, genomics companies and research universities.
