
Medical Gas Analyzers Market Report Scope & Overview:
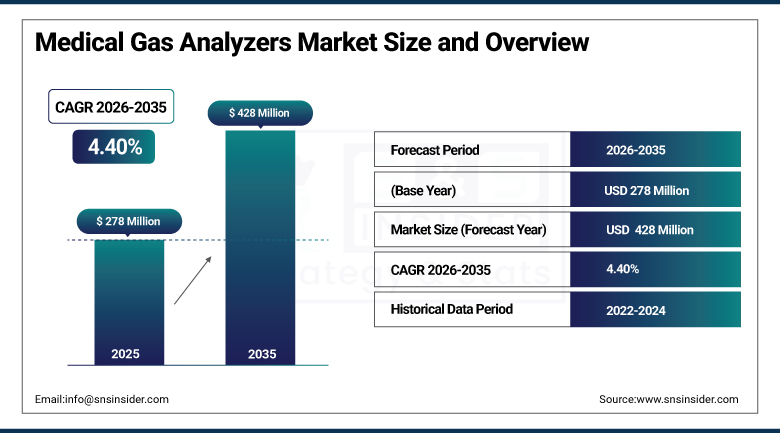
The Medical Gas Analyzers Market was valued at USD 278 Million in 2025 and is expected to reach USD 428 Million by 2035, growing at a CAGR of 4.40% from 2026-2035.
Medical gas analyzers constitute an essential category within clinical instrumentation, used for the qualitative measurement and quantitative verification of pure medical gases including oxygen, nitrogen, carbon dioxide, and nitrous oxide across hospitals and healthcare facilities. Rising numbers of hospitalized patients, expanding intensive care and operating room infrastructure, and increasingly stringent regulatory standards governing medical gas purity continue to broaden the clinical base requiring these instruments. Hospitals, ambulatory surgical centers, and an expanding base of outpatient clinics rely on medical gas analyzers to verify gas purity and concentration, ensuring patient safety across anesthesia delivery, respiratory therapy, and critical care applications.
On September 17, 2025, Servomex launched a new online purchasing request system for its SERVOFLEX portable gas analysis range, including instruments used in medical gas verification applications across laboratories and healthcare facilities. The company stated the system enables faster access to portable oxygen and carbon dioxide analyzers featuring advanced paramagnetic and infrared sensing technologies.
To Get more information On Medical Gas Analyzers Market - Request Free Sample Report
Medical Gas Analyzers Market Trends:
-
Growing adoption of portable and handheld analyzers supporting bedside and point-of-care gas verification.
-
Rising demand for multiple gas analyzers capable of simultaneous measurement across several gas streams.
-
Expanding regulatory emphasis on medical gas purity verification across hospital and ambulatory settings.
-
Increasing manufacturer investment in infrared and optical sensing technology improving measurement accuracy.
-
Rising need for basic gas monitoring across outpatient and diagnostic clinic settings.
-
Growing integration of digital connectivity features supporting streamlined compliance documentation.
-
Expanding calibration service infrastructure supporting distributed portable analyzer fleets across facilities.
U.S. Medical Gas Analyzers Market Overview:
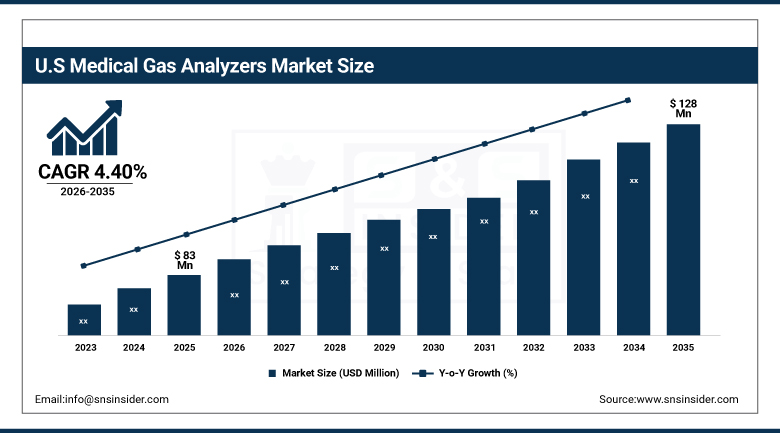
The U.S. Medical Gas Analyzers Market was valued at USD 83 Million in 2025 and is expected to reach USD 128 Million by 2035, growing at a CAGR of 4.40% from 2026-2035.
U.S. demand continues to be underpinned by advanced healthcare infrastructure and stringent regulatory standards governing medical gas purity verification across the country's hospital and ambulatory surgical center networks. Leading manufacturers continue expanding their gas analysis instrumentation portfolios, addressing rising compliance testing requirements across healthcare facility commissioning and routine verification cycles, while continued investment in portable analyzer technology keeps strengthening competitive positioning. Growing intensive care and operating room capacity further supports market expansion across the U.S. as hospital networks continue investing in verified, reliable medical gas delivery systems nationwide.
In 2025, Teledyne Technologies continued expanding its gas analysis instrumentation portfolio, supporting healthcare facility compliance testing requirements across hospital and ambulatory surgical center commissioning cycles. The company stated its continued investment reflects sustained demand for precise, reliable gas measurement technology across regulated healthcare environments.
Medical Gas Analyzers Market Segment Analysis:
-
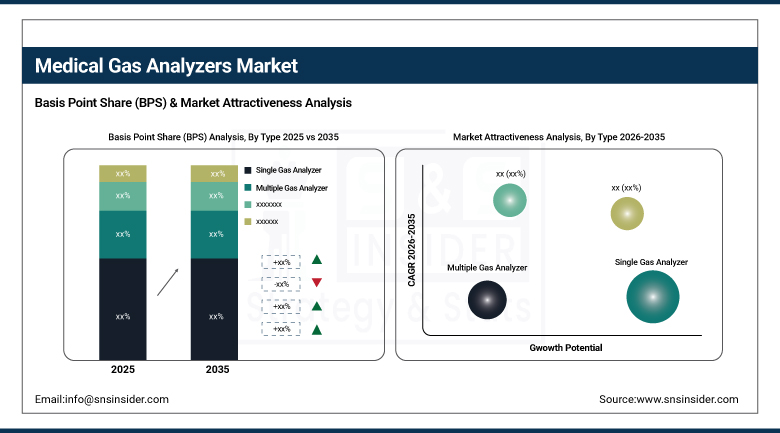
By Type, the Single Gas Analyzer segment dominated the market with a 58.60% share in 2025, while the Multiple Gas Analyzer segment is the fastest growing with a CAGR of 5.90% during 2026-2035.
-
By Technology, the Electrochemical segment dominated the market with a 44.60% share in 2025, while the Infrared segment is the fastest growing with a CAGR of 6.20% during 2026-2035.
-
By Modality, the Table-Top/Benchtop segment dominated the market with a 45.00% share in 2025, while the Portable/Handheld segment is the fastest growing with a CAGR of 6.60% during 2026-2035.
-
By End User, the Hospitals & Ambulatory Surgical Centers segment dominated the market with a 52.60% share in 2025, while the Clinics segment is the fastest growing with a CAGR of 6.80% during 2026-2035.
By Type, Single Gas Analyzer Dominates the Market and Multiple Gas Analyzer Grows Fastest
Single Gas Analyzers dominated the market in 2025, a position built on their cost-effective, straightforward design suited to routine verification of individual medical gases such as oxygen or nitrous oxide across the widest range of healthcare facility types. Facility operators favour this instrument category precisely because it delivers dependable, focused measurement capability at a lower price point than multi-gas alternatives, a combination that continues to make single gas analyzers the default specification across smaller clinics and routine compliance testing applications worldwide, even as multi-gas instruments continue to expand around it for more complex facility requirements.
Multiple Gas Analyzers are projected to be the fastest-growing type category over the forecast period. Rising demand for instruments capable of simultaneously verifying several gas streams continues to expand the addressable application base for this instrument category as larger hospital networks increasingly seek to streamline compliance testing workflows across complex, multi-gas medical delivery systems. As healthcare facilities continue consolidating testing protocols to reduce inspection time and labor costs, multiple gas analyzers continue closing the gap with single-gas alternatives in overall market demand.
By Technology, Electrochemical Dominates the Market and Infrared Grows Fastest
Electrochemical technology led in the market during 2025. This sensing technology continues to provide an effective, proven measuring technique for a wide array of commonly available gases used in the medical sector that has had extensive clinical experience and well-defined calibration and maintenance procedures used in biomedical engineering departments in health care facilities. This continued reliability will help keep electrochemical technology leading in the market, especially for regular, high-frequency verification purposes.
Infrared technology will lead in terms of growth among all other sensing technologies over the forecast period. Increased interest in achieving higher measurement precision and fast response times will continue to increase the number of addressable applications for this sensing technology in healthcare facilities that increasingly rely on precise measurement for verifying critical care and anesthesia administration. Continued miniaturization and lowering of costs in infrared sensors will narrow the market gap with traditional electrochemical sensors.
By Modality, Table-Top/Benchtop Dominates the Market and Portable/Handheld Grows Fastest
Table-Top/Benchtop analyzers dominated the market in 2025, accounting for close to half of overall global market share. This modality continues to be primarily used within hospitals, laboratories, and specialized healthcare facilities where fixed installation and consistent power supply support higher measurement precision and more comprehensive testing capability than portable alternatives typically offer. This precision advantage continues to sustain table-top and benchtop instruments as the dominant modality category across dedicated testing and calibration laboratory environments.
Portable/Handheld analyzers are expected to be the fastest-growing modality category over the forecast period. Rising demand for on-site, bedside gas verification continues to expand the addressable application base for this modality as healthcare facilities increasingly require flexible testing capability that does not depend on transporting samples to a dedicated laboratory setting. As manufacturers continue improving portable analyzer accuracy and battery life, this modality continues closing the gap with table-top instruments in overall market demand, particularly across facility commissioning and field verification applications.
By End User, Hospitals & Ambulatory Surgical Centers Dominates the Market and Clinics Grows Fastest
Hospitals & Ambulatory Surgical Centers dominated the market in 2025. The scale and regulatory complexity of gas delivery systems supporting intensive care units, operating rooms, and recovery areas continues to require the broadest and most comprehensive medical gas verification infrastructure of any single facility type. This breadth of clinical and regulatory need, combined with the sheer testing volume that major hospital networks require, continues to sustain this end-user category as the clear leading segment across the broader market.
Clinics are expected to be the fastest-growing end-user category over the forecast period, driven by the growing need for basic gas monitoring in outpatient and diagnostic settings. As routine and specialized medical procedures continue migrating toward lower-cost outpatient clinic settings, demand for compliant medical gas verification capability continues expanding beyond traditional hospital-based testing. As standalone and multi-site clinic networks continue building out procedural capability, this end-user category continues to close the gap with hospitals and ambulatory surgical centers in overall market demand.
Regional Analysis:
North America Medical Gas Analyzers Market Insights
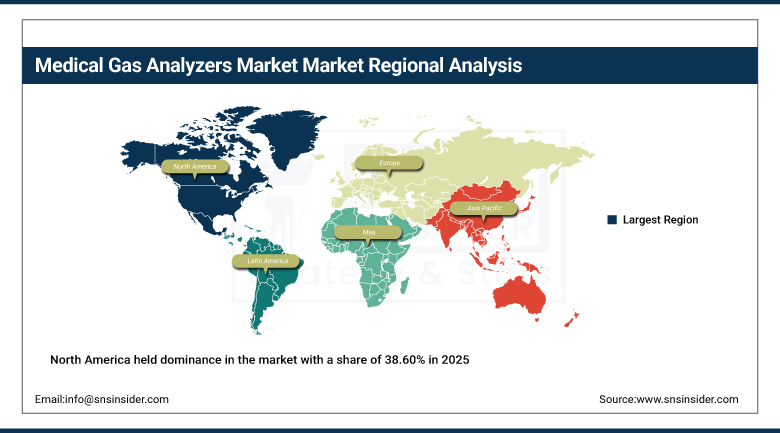
North America held dominance in the market with a share of 38.60% in 2025. The advanced healthcare infrastructure along with the strict standards for the purity of medical gas in the region are some of the key factors supporting the dominant position of North America across the hospitals and ASCs. The U.S., being home to some prominent gas analysis instruments suppliers, influences the demand pattern in the region.
Canada contributes additional regional demand through its participation in North American healthcare capital equipment procurement and regulatory compliance frameworks. Continued domestic investment in portable analyzer technology and compliance testing infrastructure is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets building out hospital infrastructure from a considerably smaller existing base. Mexico's growing healthcare facility construction activity further contributes to the broader North American market's scale advantage.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Medical Gas Analyzers Market Insights
The Asia Pacific region will be the fastest-growing one, achieving a compound annual growth rate of 6.40% between 2026 and 2035, driven by increased health expenditure, development of hospital infrastructure, and increasing regulatory focus on the verification of purity of medical gases in the region. China will be the key driver for the regional demand as hospitals develop more intensive care and operating room capacity in both well-established and upcoming healthcare institutions in the country.
Indian hospitals are adding to the regional growth due to their development of the hospital infrastructure and increased regulation that allows for the verification of medical gases in the region. Other major contributors to regional growth include Japan and South Korea with their advanced healthcare systems and their potential to achieve the fastest growth rate among all regions until 2035.
Europe Medical Gas Analyzers Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established gas analysis instrumentation manufacturers and continued advancement in precision measurement technology developed for hospital and laboratory applications. Germany's substantial hospital and manufacturing base anchors regional demand, supported by a well-developed regulatory framework that continues to favour early adoption of next-generation medical gas verification technology across the country and neighbouring markets.
The United Kingdom, France, and other major European markets contribute consistent demand as national health systems keep extending advanced gas analysis technology into routine facility compliance practice. Continued European Union regulatory emphasis on medical gas purity standards supports steady regional demand for advanced, compliant verification instruments.
MEA & Latin America Medical Gas Analyzers Market Insights
The Middle East & Africa market is supported by growing healthcare infrastructure spending across the United Arab Emirates and Saudi Arabia, where rising hospital and surgical center investment continues to lift demand for modern medical gas verification equipment across both public hospital networks and an expanding private healthcare sector. Regional governments continue channeling substantial investment into expanding diagnostic and surgical capacity, including dedicated facilities designed to reduce reliance on overseas treatment for complex cases. Qatar and Saudi Arabia's continued hospital expansion programs further reinforce regional demand for verified, compliant gas delivery infrastructure.
Latin America's market is anchored by Brazil, where a sizeable domestic healthcare sector sustains steady equipment demand across both public and private hospital systems. Mexico contributes further incremental growth as healthcare access continues to widen across the broader region, though adoption of the most advanced portable and multi-gas verification instruments across Latin America as a whole still lags meaningfully behind more established markets in North America and Europe. Argentina and Chile contribute additional incremental regional demand as domestic hospital infrastructure investment continues to expand.
Market Dynamics:
Growth Drivers: Rising Hospitalization and Regulatory Compliance Requirements
Rising numbers of hospitalized patients stand as a primary growth driver, as the medical gas analyzer is more frequently required and used within intensive care units and operating rooms, where the number of hospitalized patients continues increasing alongside broader population growth worldwide. This dynamic is reinforced by increasingly stringent regulatory standards governing medical gas purity, as healthcare facilities across major markets continue facing mandatory verification and compliance testing requirements throughout facility commissioning and routine operational cycles. Rising surgical and anesthesia procedure volumes further compound this trend, as each new operating suite and recovery area requires its own dedicated verification testing before achieving regulatory clearance for patient use.
Further addition to this would be the increasing need for intensive care and OR infrastructure, as more and more hospitals globally continue to invest in building their critical care capabilities, which need reliable and verified medical gases systems. Increase in the need for portable and handheld devices is another factor fueling the growth of the market, as health care facilities look for ways to test their facilities and comply with regulations through the use of such devices.
Restraints: High Equipment Costs and Calibration Complexity
High equipment prices continue to represent an actual restraint on market development due to the fact that advanced multi-gas and infrared analysis instruments continue to require sizable capital investment, which may be hard for smaller clinics and price-sensitive markets to justify against tight budgets. Cost restraint is particularly relevant for smaller clinics and facilities operating in emerging markets, where high investments needed for the most advanced currently available measuring devices may significantly outstrip any reasonable amount of money, which can be allocated for such equipment in a budget period.
Another restraining factor is calibration, as the need to maintain high accuracy of measurements for different types of medical gases continues to require high technical skills and regular calibrations, which might not always be easy to organize for smaller health care facilities due to limited resources of their biomedical engineers. Manufacturers and facilities will have to continue making sizable investments into technical support and training, which could significantly complicate the process of compliance testing. The fact that the number of specialized sensor suppliers is relatively limited represents another cost factor for manufacturers.
Opportunities: Portable Technology Advancement and Multi-Gas Instrument Development
Continued advancement of portable and handheld analyzer technology offers a substantial opportunity, as manufacturers developing instruments delivering laboratory-grade accuracy in field-deployable formats stand to capture meaningful new demand from facilities seeking flexible, on-site verification capability. Healthcare facilities increasingly view portable technology not as a novelty feature but as a genuine operational necessity capable of reducing testing turnaround time while maintaining regulatory compliance across distributed care settings. Manufacturers that successfully combine portability with laboratory-grade precision stand to capture disproportionate share as facilities increasingly consolidate vendor relationships around instrumentation partners capable of serving both fixed and mobile testing needs.
The continued development of multiple gas analyzer instruments presents a further avenue for growth, as healthcare facilities increasingly seek to streamline compliance testing workflows across complex, multi-gas medical delivery systems. This innovation pathway continues to open substantial new demand for manufacturers with established multi-sensor integration capabilities serving large hospital networks managing extensive gas delivery infrastructure.
Recent Developments:
-
2025, Prior Care Science Technology received FDA 510(k) clearance for its AG200 Medical Gas Analyzer, designed to monitor CO₂, N₂O, and multiple anesthetic agents in breathing circuits during anesthesia, recovery, and respiratory care.
-
2025, TSI expanded its Certifier Flow Analyzer family with a new Anesthesia Sensor, alongside ISO 17025-accredited calibration services in the UK. The sensor is designed for testing anesthesia machines, ventilators, and oxygen-delivery systems.
-
2025, Servomex expanded access to its portable gas-analysis portfolio through a new online purchasing system, covering the SERVOFLEX MiniMP 5200 and Micro i.s. 5100. The analyzers support O₂ and CO₂ measurement and applications including medical-gas verification and respiratory research.
-
2025, Dräger introduced the Atlan A100 anesthesia workstation, adding a new anesthesia platform to its portfolio for operating-room applications. The system integrates gas-delivery and patient-monitoring functions within the anesthesia workflow.
Medical Gas Analyzers Market Key Players:
-
Drägerwerk AG & Co. KGaA
-
Teledyne Technologies Incorporated
-
Servomex Group Limited
-
Fluke Biomedical
-
Maxtec, LLC
-
Bacharach, Inc.
-
MSA Safety Incorporated
-
Analytical Industries, Inc.
-
Oxigraf, Inc.
-
Air Liquide S.A.
-
NOVAIR Medical
-
Praxair Technology, Inc. (Linde)
-
Taiyo Nippon Sanso Corporation
-
GCE Group
-
Beacon Medaes (Atlas Copco)
-
Amico Corporation
-
Powerex, Inc.
-
Geotechnical Instruments (UK) Ltd.
-
TSI Incorporated
-
WITT-GASETECHNIK GmbH & Co KG
Medical Gas Analyzers Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 278 Million |
| Market Size by 2035 | USD 428 Million |
| CAGR | CAGR of 4.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Single Gas Analyzer and Multiple Gas Analyzer) • By Technology (Electrochemical, Infrared, and Optical) • By Modality (Portable/Handheld and Table-Top/Benchtop) • By End User (Hospitals & Ambulatory Surgical Centers, Clinics, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Drägerwerk AG & Co. KGaA, Teledyne Technologies Incorporated, Servomex Group Limited, Fluke Biomedical, Maxtec, LLC, Bacharach, Inc., MSA Safety Incorporated, Analytical Industries, Inc., Oxigraf, Inc., Air Liquide S.A., NOVAIR Medical, Praxair Technology, Inc. (Linde), Taiyo Nippon Sanso Corporation, GCE Group, Beacon Medaes (Atlas Copco), Amico Corporation, Powerex, Inc., Geotechnical Instruments (UK) Ltd., TSI Incorporated, WITT-GASETECHNIK GmbH & Co KG |

Frequently Asked Questions
Key players include Drägerwerk, Teledyne Technologies, Servomex Group, Fluke Biomedical, Maxtec, Bacharach, MSA Safety, Analytical Industries, Oxigraf, and Air Liquide, among others.
Continued advancement of portable and handheld analyzer technology and the continued development of multiple gas analyzer instruments represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by rising numbers of hospitalized patients, combined with increasingly stringent regulatory standards governing medical gas purity verification.
By Modality, Table-Top/Benchtop analyzers dominated the market with a 45.00% share in 2025, reflecting their use in hospitals, laboratories, and specialized healthcare facilities requiring higher measurement precision.
North America dominated the market with a 38.60% share in 2025, supported by the region's advanced healthcare infrastructure and stringent regulatory standards
