
Medical Textile Industry Market Report Scope & Overview:
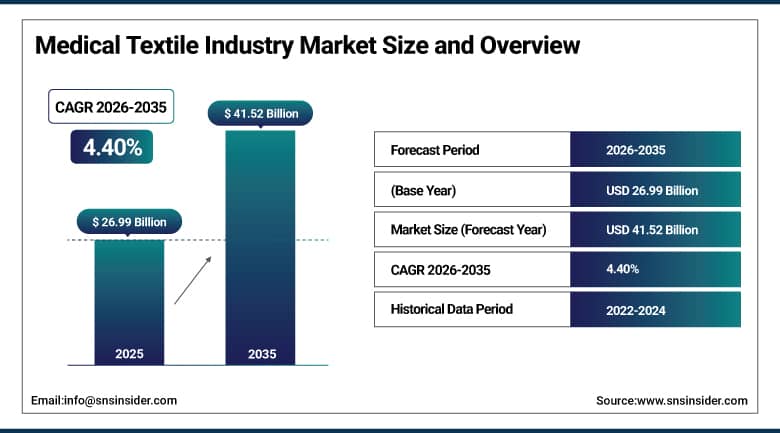
The Medical Textile Industry Market was valued at USD 26.99 Billion in 2025 and is expected to reach USD 41.52 Billion by 2035, growing at a CAGR of 4.40% from 2026-2035.
The Medical Textile Industry Market is growing steadily as hospitals, clinics and home care providers use more engineered fabrics for protection, wound management and implants. Non-woven materials lead because they are low in cost, compatible with sterilization and suited to single-use gowns, drapes and hygiene products. Wound dressings and compression products add value as chronic conditions rise. Implantable textiles such as meshes and grafts offer smaller volumes at higher prices. Infection control rules keep barrier fabrics in routine use. Reusable gown programs and biodegradable fibers are changing purchasing in some health systems. Asia Pacific leads production and consumption. The market is expected to expand as surgical volumes, ageing populations and hygiene standards increase together.
⮞In December 2025, INDA released its 13th North American Nonwovens Industry Demand and Forecast report, covering 2019 to 2024 history and a forecast to 2029. The report treats medical nonwovens as a short-life segment, which shows how closely the market follows demand for disposable products.
To Get More Information On Medical Textile Industry Market - Request Free Sample Report
Medical Textile Industry Market Trends:
-
Shift from disposable to reusable surgical gowns in sustainability-focused health systems
-
Growth of antimicrobial and infection-sensing wound dressings built on textile substrates
-
Rising use of resorbable and bio-based fibers in hernia meshes and vascular grafts
-
Capacity additions for medical nonwovens in Asia Pacific, North Africa and Eastern Europe
-
Regulatory reform of device rules and gown standards raising testing and documentation needs
U.S. Medical Textile Industry Market Outlook:
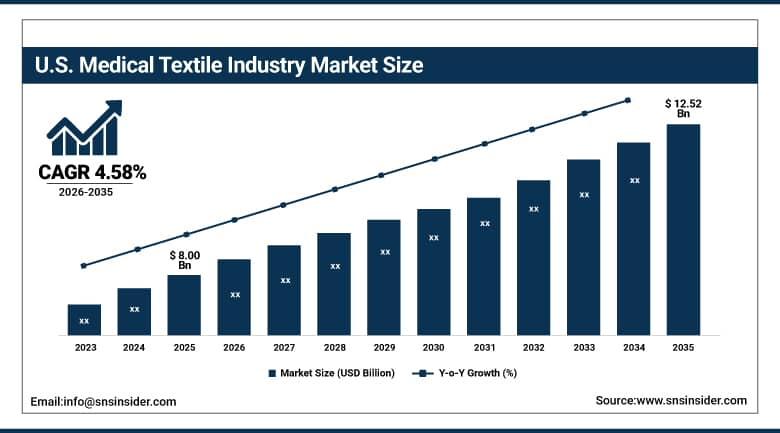
The U.S. Medical Textile Industry Market was valued at USD 8.00 Billion in 2025 and is expected to reach USD 12.52 Billion by 2035, growing at a CAGR of 4.58% from 2026-2035.
The U.S. Medical Textile Industry Market is the largest national market in North America, supported by high surgical volumes and strict infection control rules. Hospitals buy disposable and reusable gowns, drapes and sterilization wraps through group purchasing contracts. The Food and Drug Administration reviews gowns, drapes and dressings as medical devices, and AAMI standards define protection levels. Wound care is a large category because of diabetes and an ageing population. Implantable meshes and grafts are made by established device companies. Federal programs and private firms are exploring U.S. production of nonwovens and protective apparel. Reusable gown programs are growing in some health systems. Demand is expected to rise with procedure volumes and supply chain resilience efforts.
⮞For example, in June 2026 the U.S. Food and Drug Administration cleared a 510(k) for Tuff Cuff disposable surgical gowns, rated AAMI Level 4 and supplied sterile, submitted by New York Embroidery Studio. The clearance shows the continuing regulatory pipeline for protective surgical apparel.
Medical Textile Industry Market Segment Analysis:
-
By Fabric Type, the Non-Woven segment dominated the Medical Textile Industry Market with approximately 50.81% share in 2025, and is also the fastest growing with a CAGR of approximately 5.40%.
-
By Application, the Healthcare and Hygiene Products segment dominated the Medical Textile Industry Market with approximately 44.58% share in 2025, while the Implantable Goods segment is the fastest growing with a CAGR of approximately 7.48%.
-
By End User, the Hospitals and Clinics segment dominated the Medical Textile Industry Market with approximately 57.49% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of approximately 6.60%.
-
By Biodegradability, the Non-Biodegradable segment dominated the Medical Textile Industry Market with approximately 73.85% share in 2025, while the Biodegradable segment is the fastest growing with a CAGR of approximately 5.56%.
By Fabric Type, Non-Woven Dominates the Medical Textile Industry Market and Is Also the Fastest Growing
Non-woven fabrics dominate as spunbond, meltblown and spunlace processes enable rapid manufacturing at low prices with controllable pore size and fluid resistance. Surgical gowns, drapes, sterilization wraps, masks and wound pads depend on laminated multi-layer non-woven constructions. Single-use products decrease the risk of cross-infection, and hospitals order them under uniform contracts beneficial to large converters. The main material used is polypropylene, and it allows for efficient treatment providing repellency and antistatic properties. Established production capacities in Asia, Europe and North America provide plenty of potential suppliers, making prices low and supply stable. Also, converters invest in automated inspection and lamination lines to make the process more consistent and allow suppliers to better comply with higher standards set by hospitals.
Non-wovens are the fastest-growing structure due to advances in bonding and finishing techniques that expand application areas. Electro-spun and nanofiber layers provide filtration and cell scaffolding capabilities, while hydro-entangled blends of cellulose and synthetic fibers increase softness and absorbency in dressings. Bio-based polymers, antimicrobial finishes and flushable or compostable grades are the responses to increasing environmental concerns. Orders from home care, ambulatory surgery and infection prevention programs increase sales volumes, and manufacturers are establishing clean room facilities to produce medical-grade products.
⮞In June 2025, Nonwovenn announced a new Class 8 cleanroom medical manufacturing suite at its Bridgwater site in the United Kingdom as part of a three-year growth plan for its MediTech division. The investment shows demand for medical-grade nonwoven capacity.
By Application, Healthcare and Hygiene Products Dominates the Medical Textile Industry Market and Implantable Goods Grows Fastest
Healthcare and hygiene products lead because they cover the widest range of everyday items, including gowns, drapes, masks, bed linen, incontinence products, wipes and bandages. Hospitals, nursing homes and home care users consume these items continuously, and infection prevention rules require frequent replacement. Ageing populations raise demand for adult incontinence and pressure injury products, while public health programs promote hand and surface hygiene. Large manufacturers supply these goods in bulk to health systems and retailers, and standardized specifications keep entry costs manageable for new regional producers. Hospitals also value that implantable textiles are supported by long-term clinical follow-up, which builds surgeon confidence and repeat purchasing across procedures.
Implantable goods are growing fastest because aging populations and surgical innovation increase the use of hernia meshes, vascular grafts, sutures, heart valve sewing rings and tissue scaffolds. Knitted, woven and braided polyester, PTFE and polypropylene structures are being redesigned with resorbable fibers and coated surfaces that reduce infection and promote tissue growth. Volumes are small compared with hygiene goods, but unit prices are high and regulatory barriers protect established suppliers. Clinical trials of resorbable meshes and vascular prostheses support wider adoption in hospitals.
⮞In August 2026, BD announced that enrollment was complete in its PREVENT trial of Phasix resorbable mesh, with 477 patients at 32 sites in the United States and Europe. The trial tests an implantable textile structure for preventing incisional hernia.
By End User, Hospitals and Clinics Dominates the Medical Textile Industry Market and Ambulatory Surgical Centers Grows Fastest
Hospitals and clinics lead because they run the highest number of surgical procedures, wound treatments and patient admissions, and they purchase gowns, drapes, dressings and linens in large lots. Group purchasing organizations and national tenders set specifications and pricing. Infection control committees decide which barrier level and fabric type to use, and sterilization departments manage reusable textiles and wraps. Hospital building programs in emerging markets add new demand, and replacement cycles for linens and curtains keep volumes stable in mature markets. Strong adoption of surgical procedure packs among smaller outpatient providers is expected to keep the segment growing faster than hospital purchasing.
Ambulatory surgical centers are growing fastest as procedures move from inpatient wards to lower-cost outpatient settings. Orthopedic, ophthalmic, gastrointestinal and cosmetic procedures now take place in these centers, which buy single-use drape and gown packs sized for short cases. Procedure kits that bundle gowns, drapes and dressings simplify purchasing for small facilities. Payers support the shift because it lowers cost, and centers are adopting infection prevention protocols that match hospital standards, which raises demand for certified protective textiles. Because these centers run short cases with fast turnover, they favor pre-packed kits that reduce handling time and storage needs.
⮞In April 2025, The Ottawa Hospital said it had moved its operating rooms to reusable surgical gowns across its three campuses, replacing disposable gowns. The hospital expects to cut annual waste by almost 33,000 kilograms.
By Biodegradability, Non-Biodegradable Dominates the Medical Textile Industry Market and Biodegradable Grows Fastest
Non-biodegradable materials lead because polypropylene, polyester, nylon and PTFE meet the strength, barrier and sterilization needs of medical use at low cost. These fibers hold their performance through gamma, ethylene oxide and steam sterilization, and they resist fluids and microbes. Regulatory files for synthetic medical fabrics are well established, which shortens approval for new products. Buyers often choose them for proven performance in high-risk settings such as operating rooms. Because these materials are cheap and widely produced, they remain the base of gowns, drapes, masks and many implants. Hospital sustainability teams now request life-cycle data from suppliers, which pushes manufacturers to document the origin and disposal of every fiber used.
Biodegradable materials are growing fastest as health systems face waste targets and suppliers look for alternatives to single-use plastics. Polylactic acid, regenerated cellulose, alginate, chitosan and silk are used in dressings, sutures, scaffolds and hygiene products. Resorbable implants avoid a second surgery and reduce long-term foreign body reactions. Cost, shelf life and sterilization compatibility remain hurdles, but investments in bio-based fibers and compostable nonwovens are increasing as procurement rules reward lower environmental impact. Hospitals also pilot compostable wipes and biodegradable hygiene items to test cost and performance before wider adoption.
⮞In October 2026, Solventum received U.S. FDA 510(k) clearance for Restrata, a synthetic electrospun fiber matrix used with V.A.C. Therapy. The clearance shows continued development of engineered fibrous materials for wound healing.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
86.42 |
|
Europe |
Germany |
24.78 |
|
Asia Pacific |
China |
38.47 |
|
Latin America |
Brazil |
46.35 |
|
Middle East & Africa |
Saudi Arabia |
29.61 |
Asia Pacific Medical Textile Industry Market Insights
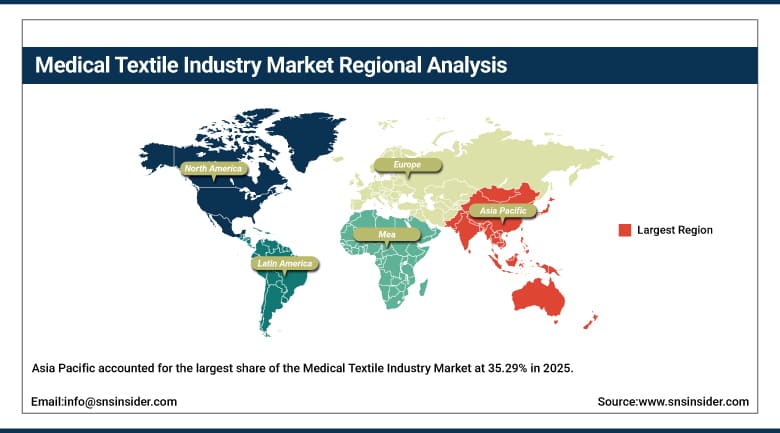
Asia Pacific accounted for the largest share of the Medical Textile Industry Market at 35.29% in 2025, led by China, Japan, India and Vietnam. The region is the main production base for non-woven fabrics, gauze, bandages and protective apparel, supported by cotton and polypropylene supply chains and low labor costs. China holds a large export business in dressings and masks, while Japan focuses on premium wound care and implantable textiles. India is expanding hospital capacity and domestic manufacturing of medical consumables. Large cotton and polypropylene supply bases keep input costs lower than in other regions.
Asia Pacific is also projected to be the fastest growing region, with a CAGR of 5.86% during 2026-2035. Rising healthcare spending, ageing populations in Japan, China and South Korea, and expansion of hospital networks in India and Southeast Asia lift demand. Producers are building plants in Vietnam, Cambodia and Thailand to serve buyers who want supply diversification. Quality systems, international certifications and adherence to ISO and AAMI standards remain key factors for exporters, and regional brands are moving into premium dressings. Growing outpatient surgery and home care networks add further demand.
⮞In January 2026, Winner Medical received an investment certificate for a USD 60.5 million plant in Quang Ninh, Vietnam, with full operation due by December 2027. The plant shows regional expansion of medical dressing and surgical supply capacity.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Medical Textile Industry Market Insights
North America is the second largest region, led by the United States and supported by Canada. High surgical volumes, large hospital networks, a big wound care population and strict infection control rules keep demand strong. Leading device and dressing makers operate in the region, and group purchasing organizations shape specifications. Medical gowns must meet AAMI protection levels and FDA requirements, which favors suppliers with documented testing and quality systems. Demand is also supported by broad insurance coverage for wound care and elective surgery, which keeps procedure volumes high across the region.
Supply chain resilience is a central theme. Experience with imported shortages has led hospitals and governments to seek local sources of nonwovens, gowns and dressings, and several manufacturers are expanding U.S. plants. Reusable gown programs in Canadian and U.S. health systems are reducing waste and creating demand for durable laundering and sterilization services. Higher labor and energy costs limit price competitiveness against Asian imports, so manufacturers stress quality, automation and supply security. Local sourcing efforts are supported by public health preparedness programs that favor suppliers with local plants and reliable raw material access.
⮞In September 2025, Mölnlycke Health Care broke ground on an expansion of its wound care manufacturing plant in Brunswick, Maine, with the aim of raising U.S. capacity significantly. The company expects headcount at the site to grow about 10% over five years.
Europe Medical Textile Industry Market Insights
Europe is a mature and technology-led region, led by Germany, the United Kingdom, France, Italy and Sweden. The region hosts several of the world's largest wound care, compression and incontinence producers, as well as leading nonwoven material suppliers. National health systems buy dressings and gowns through tenders, and the Medical Device Regulation and Personal Protective Equipment Regulation set high documentation requirements. Sustainability policy is influential, with hospitals piloting reusable gowns and suppliers developing recyclable and bio-based materials. Environmental policy and hospital procurement guidelines are also pushing suppliers to document product recyclability and chemical safety.
Cost and compliance are the main pressures. Energy prices and labor costs lift production expense, and Asian imports compete on price in basic products, so European makers focus on advanced dressings, compression garments and specialty barrier fabrics. Notified body capacity has affected product certification timelines, and regulators are working on simplification. Germany, Italy and Eastern European countries host textile and nonwoven plants that serve both regional hospitals and export customers. Hospitals in the region also place high value on suppliers that offer complete technical files, which favors established producers over new entrants.
⮞In December 2025, the European Commission proposed a simplification of the Medical Device Regulation, including removal of the default five-year limit on notified body certificate validity. The proposal is still in the legislative process and would reduce compliance burden for manufacturers.
MEA & Latin America Medical Textile Industry Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Colombia. Public hospital systems and private clinics buy gowns, drapes, gauze and bandages, and cosmetic and orthopedic surgery volumes support demand for dressings and compression garments. Brazil has a sizeable local textile and nonwoven industry, while much of the region imports advanced wound care and implantable products. Currency swings, import duties and registration timelines at regulators such as ANVISA influence pricing and product availability. Public tenders in Brazil and Mexico also favor suppliers that can show local registration and dependable delivery.
⮞In May 2026, Hindernis DE Mexico received U.S. FDA 510(k) clearance for BAÜMER surgical gowns. The clearance shows Latin American manufacturers seeking access to the U.S. market.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Egypt and South Africa lead demand. Gulf health programs are building new hospitals and encouraging local production of medical consumables, while North African countries are attracting garment and textile plants that serve European buyers. Much of sub-Saharan Africa depends on imports and donated supplies, so affordability and procurement systems limit use. Growth in private hospitals and medical tourism is raising demand for certified gowns, drapes and advanced dressings. Local converters are also investing in sterilization and packaging services to meet hospital expectations.
⮞In May 2026, Jiangsu Aishelun Medical Technology Group broke ground on its first African plant at Tanger Tech City in Morocco, which will make surgical gowns and operating drapes for Europe, the Middle East and North Africa. The project shows nearshoring of medical textile production close to European buyers.
Market Dynamics:
Growth Drivers: Surgical Volumes, Infection Control and Ageing Populations Drive Growth in the Medical Textile Industry Market
Rising surgical and hospital activity is the base of demand. Ageing populations need more joint replacements, cataract operations, cardiovascular procedures and wound care, and each procedure consumes gowns, drapes, wraps and dressings. Infection control programs and regulations require barrier fabrics in operating rooms, and hospital-acquired infection data keep managers focused on protective textiles. Chronic diseases such as diabetes increase the number of long-term wounds, which supports dressings, bandages and compression garments used in hospitals and at home. Procurement teams also favor suppliers that can document barrier performance, which supports established producers with strong testing records and consistent quality.
Product innovation adds value to the market. Antimicrobial finishes, moisture-managing layers and breathable barrier laminates improve comfort and performance, and smart dressings with sensors are moving from laboratories to clinics. Home healthcare is growing as payers shift care out of hospitals, which creates demand for easy-to-use dressings and compression products. Expansion of hospital capacity in India, the Middle East and Southeast Asia, together with public health programs on hygiene, further lifts volume across the product range. Rising investment in medical device clusters further supports local demand for textile components.
⮞In July 2026, the U.S. Centers for Disease Control and Prevention reported that about 518,000 healthcare-associated infections occurred in U.S. hospitals in 2023. Surgical site infections showed little change, which keeps barrier gowns, drapes and dressings in steady demand.
Restraints: Input Costs, Regulatory Burden and Waste Scrutiny Restrain Growth in the Medical Textile Industry Market
Raw material and energy costs weigh on margins. Polypropylene and polyester prices follow oil and petrochemical markets, and supply disruptions can lift costs quickly. Non-woven production is energy intensive, which hurts European and Japanese producers in periods of high power prices. Low-cost imports from large Asian producers compete in basic products such as masks, gauze and gowns, and price competition limits the ability of local manufacturers to recover higher input costs. Shipping delays and fluctuating freight rates add uncertainty for importers and raise the landed cost of finished goods in many regions.
Compliance and sustainability add further pressure. Device rules in the United States and Europe require testing, clinical evidence and quality audits, and implantable textiles face the longest approval timelines. Hospitals and regulators are scrutinizing the volume of single-use plastic waste, and some health systems are switching to reusable products that reduce demand for disposables. Reimbursement gaps for advanced dressings in some countries also slow adoption, and fragmented procurement in emerging markets makes it difficult for premium suppliers to scale. Smaller suppliers also struggle with the cost of maintaining certifications across several countries.
⮞In April 2026, EDANA reported that nonwovens production in Greater Europe fell about 2.2% in 2025. The decline shows the cost and demand pressure facing European producers.
Opportunities: Reusable Gowns, Resorbable Fibers and Smart Textiles Create Opportunities in the Medical Textile Industry Market
Sustainability programs are opening new product categories. Reusable gowns that can be laundered many times offer hospitals lower waste and predictable supply, and textile service companies are investing in laundering, tracking and sterilization systems. Producers that can certify durability and barrier performance across repeated washes can win long-term contracts with health systems. Recycled and bio-based fibers are also attracting interest from buyers who track carbon emissions and waste. Hospitals that adopt reusable programs also generate data on durability, which helps suppliers refine fabrics and win further contracts. Textile service providers are also adding digital tracking to manage wash cycles and replacement.
Advanced materials create higher-value uses. Resorbable meshes and vascular grafts, drug-eluting dressings, electrospun scaffolds and textile-based sensors extend the market beyond commodity fabrics. Wearable and smart textiles that track wound pH, temperature or moisture can support remote patient monitoring and home care. Regional production capacity in North Africa, Eastern Europe and the United States may serve buyers who want shorter supply lines, which opens space for new suppliers and joint ventures. Partnerships between fiber makers, device companies and hospitals are expected to speed commercialization of these products.
⮞In July 2025, Island Health in British Columbia said its reusable gown program, launched in February 2025, allows gowns to be reused up to 100 times. The program shows demand for durable gowns in large health systems.
Recent Developments:
-
In July 2026, Freudenberg Performance Materials acquired Foshan United Medical, a China-based supplier of advanced wound care products including foam, alginate and chitosan dressings. The acquisition adds Asian wound care manufacturing capacity and customer access.
-
In August 2026, Attindas Hygiene Partners signed a binding agreement to acquire Activ Médical Disposable, a France- and Spain-based maker of adult incontinence and disposable medical products with nearly 300 employees, subject to regulatory approval. The deal widens its European hygiene and medical disposable footprint.
-
In August 2026, Hartmann Group reported the development of a wound dressing with a support layer that detects infection in wound fluid through an enzymatic reaction. The development shows the shift toward dressings that give clinicians early infection signals.
-
In August 2025, iFabric announced publication in the Journal of Hospital Infection of a clinical trial of scrubs treated with its ProtX2 antimicrobial technology, which reported statistically significant reductions in bacterial load in real-world use. The study supports demand for antimicrobial healthcare apparel.
Medical Textile Industry Market Key Players:
-
Freudenberg Performance Materials (Freudenberg SE)
-
Ahlstrom Oyj
-
Magnera Corporation
-
Avgol Industries 1953 Ltd
-
Mölnlycke Health Care AB
-
PAUL HARTMANN AG
-
Lohmann & Rauscher
-
Convatec Group PLC
-
Smith & Nephew plc
-
Essity Aktiebolag (publ)
-
medi SE & Co. KG
-
Thuasne
-
Winner Medical Co., Ltd.
-
Alpha Pro Tech, Ltd.
-
W. L. Gore & Associates, Inc.
-
Vascutek Ltd (Terumo Aortic)
-
Bally Ribbon Mills
-
Medline Inc.
Medical Textile Industry Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 26.99 Billion |
| Market Size by 2035 | USD 41.52 Billion |
| CAGR | CAGR of 4.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Fabric Type (Non-Woven, Woven, Knitted, and Others) • By Application (Non-Implantable Goods, Implantable Goods, Healthcare and Hygiene Products, and Others) • By End User (Hospitals and Clinics, Ambulatory Surgical Centers, Home Care Settings, and Others) • By Biodegradability (Non-Biodegradable and Biodegradable) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Freudenberg Performance Materials (Freudenberg SE), Ahlstrom Oyj, Magnera Corporation, Avgol Industries 1953 Ltd, Mölnlycke Health Care AB, PAUL HARTMANN AG, Lohmann & Rauscher, Convatec Group PLC, Smith & Nephew plc, Essity Aktiebolag (publ), medi SE & Co. KG, Thuasne, Winner Medical Co., Ltd., Alpha Pro Tech, Ltd., W. L. Gore & Associates, Inc., Vascutek Ltd (Terumo Aortic), Bally Ribbon Mills, Medline Inc. |

Frequently Asked Questions
Key players include Freudenberg Performance Materials, Ahlstrom, Magnera, Avgol, Mölnlycke Health Care, Hartmann, Lohmann & Rauscher, Convatec, Smith & Nephew, Essity, medi, Thuasne, Winner Medical, Alpha Pro Tech, W. L. Gore & Associates, Vascutek, Bally Ribbon Mills and Medline.
Key opportunities include reusable surgical gowns, resorbable and bio-based fibers, smart and infection-sensing dressings, implantable textiles, and regional production capacity that shortens supply chains.
Rising surgical volumes, strict infection control requirements and ageing populations with chronic wounds are the main growth factors, supported by product innovation and hospital capacity expansion in emerging markets.
Ans: Strict regulations regarding biocompatibility, sterility, and disposal of medical textiles hamper the market growth.
Asia Pacific dominated the market with a share of 35.29% in 2025, driven by large production bases for nonwovens, dressings and protective apparel and by expanding healthcare capacity.
