
Metal Cleaning Chemicals Market Report Scope & Overview:
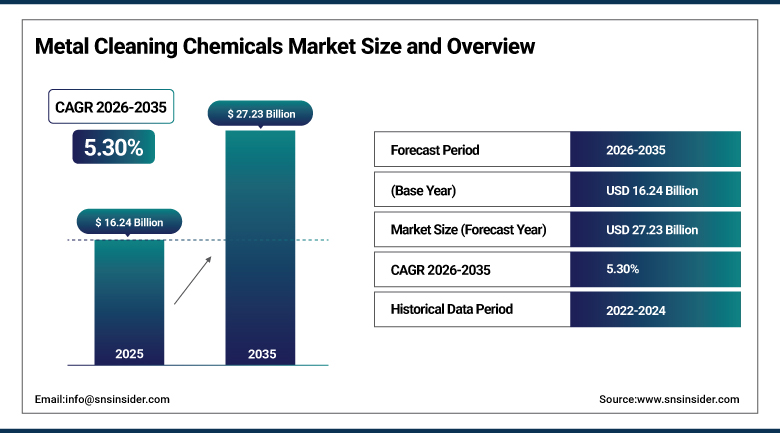
The Metal Cleaning Chemicals Market was valued at USD 16.24 Billion in 2025 and is expected to reach USD 27.23 Billion by 2035, growing at a CAGR of 5.30% from 2026-2035.
The Metal Cleaning Chemicals Market growth is being driven primarily by the rise in the manufacturing and automotive industry, which is because metal cleaning chemicals are required to ensure that metal parts in automobiles, machines, and architectures have good finishes and operate efficiently. These products, which include acidic cleaners, alkaline cleaners, neutral cleaners, and solvent cleaners, are still being employed in the removal of organic and inorganic matter such as grease, corrosion oxide, oil, and particle matters from metal components as part of the metal finishing process. Another reason behind the rise in the demand for metal cleaning products is the introduction of green metal cleaning chemicals as a result of the rising number of environmental-friendly and safe metal cleaning products.
On April 1, 2025, Quaker Houghton successfully concluded its purchase of Dipsol Chemicals Co., Ltd., a top supplier of surface treatment and plating products and services to the automotive and other industries, at a cost of about 23 billion Japanese yen, equivalent to around USD 153 million. This acquisition, involving a company with annual revenues of about USD 82 million and a market presence in Japan in the plating chemicals market segment, is an example of consolidation within the industry, as leading metal cleaning chemical companies strive to diversify their surface treatment product lines.
To Get more information Metal Cleaning Chemicals Market - Request Free Sample Report
Metal Cleaning Chemicals Market Trends
- Growing adoption of regeneration technologies reclaiming free acid and reducing sludge output in acidic cleaning.
- Rising demand for aqueous-based, environmentally sustainable metal cleaning formulations.
- Continued industry consolidation as leading suppliers acquire specialized surface treatment companies.
- Increasing focus on advanced chemistries meeting quality and sustainability expectations in precision sectors.
- Expanding strategic cooperation between specialty chemical producers serving mining and metal processing customers.
U.S. Metal Cleaning Chemicals Market Outlook
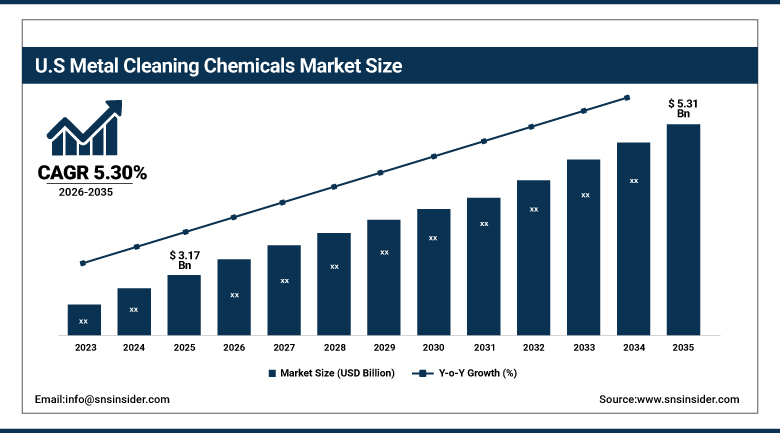
The U.S. Metal Cleaning Chemicals Market was valued at USD 3.17 Billion in 2025 and is expected to reach USD 5.31 Billion by 2035, growing at a CAGR of 5.30% from 2026-2035.
Growth in the U.S. Metal Cleaning Chemicals market continues to get bolstered by consistent demand from the auto, manufacturing, and aerospace industries, as well as ongoing infrastructure investments driving demand for acidic pickling solutions in carbon steel strips. Domestic demand is also aided by the presence of many of the world’s top specialty chemicals firms in the country that operate their manufacturing and research facilities on a global scale. Investment in the field of regeneration and sustainable formulations is also aiding demand due to growing environmental sustainability standards.
In April 2025, BASF launched Trilon G chelating agent in the Americas, expanding its U.S.-relevant sustainable cleaning portfolio with GLDA chemistry containing approximately 56% renewable carbon. Designed for industrial and institutional cleaning, the ingredient binds metal ions, softens water, and improves surfactant efficiency, enabling stronger cleaning performance. BASF positioned Trilon G as a partially biobased alternative supporting formulators seeking lower-impact cleaning solutions. The launch was announced by BASF Care Chemicals in the United States, making it a more directly relevant development for the U.S. metal-cleaning chemicals ecosystem.
Metal Cleaning Chemicals Market Segment Analysis
- By Type, the Acidic Cleaners segment dominated the Metal Cleaning Chemicals Market with approximately 37.68% share in 2025, and is also the fastest growing with a CAGR of approximately 5.56%.
- By Form, the Aqueous segment dominated the Metal Cleaning Chemicals Market with approximately 54.62% share in 2025, while the Powder segment is the fastest growing with a CAGR of approximately 5.60%.
- By Metal Type, the Steel & Ferrous Alloys segment dominated the Metal Cleaning Chemicals Market with approximately 44.92% share in 2025, while the Aluminum & Light Alloys segment is the fastest growing with a CAGR of approximately 5.47%.
- By End-User, the Automotive segment dominated the Metal Cleaning Chemicals Market with approximately 31.74% share in 2025, while the Electrical & Electronics segment is the fastest growing with a CAGR of approximately 5.41%.
By Type, Acidic Cleaners dominates and grows fastest
The Acidic Cleaners continue to be the largest and most rapidly growing product segment within the Metal Cleaning Chemicals Market, owing to the increased use of hydrochloric acid pickling baths for carbon steel strip processing. This product segment enjoys a technological advance in terms of regeneration, which is capable of regenerating the free acid and removing iron salts, resulting in a 90 percent reduction in sludge generation.
This segment also focuses on infrastructure spending in the United States and India, where new capacity investment continues to drive demand for acid-based pickling solutions across steel processing operations. As global steel production capacity continues to expand and environmental regeneration technology adoption accelerates, this segment is positioned to sustain its leadership across both current market share and forward growth relative to alkaline, neutral, and solvent cleaner alternatives.
By Form, Aqueous dominates and Powder grows fastest
Aqueous Formulations Segment is still the market leader, considering the environmental friendliness and absence of artificial substances in water-based formulations, which makes them more preferred for the environmentally conscious industry. The reason is lower waste generation, energy use, and water use compared to solvent-based products. In such a way, water-based formulations continue to attract research and development attention among manufacturers.
Powdered formulations are seen to be gaining the highest growth rate among form segments owing to high storage stability, easy transportation, and increased shelf-life compared to liquid counterparts. This form segment concentrates on producing formulations that can be easily diluted and mixed, giving an opportunity for powdered metal cleaning chemicals to gain popularity among industrial consumers.
By Metal Type, Steel & Ferrous Alloys dominates and Aluminum & Light Alloys grows fastest
Steel & Ferrous Alloys continue to be the leading metal type category in the Metal Cleaning Chemicals Market because steel is the most used structural and industrial metal around the world in the auto, construction, and other sectors. The size of the production and processing of steel globally helps this category since there is constant demand for cleaning and pickling chemicals for metal.
Aluminum & Light Alloys are emerging as the fastest-growing metal type segment, driven by increasing use of lightweight aluminum components across automotive and aerospace applications pursuing improved fuel efficiency and reduced emissions. This segment focuses on specialized cleaning chemistries suited to aluminum's distinct surface properties, positioning aluminum and light alloy cleaning chemicals to capture growing demand as vehicle and aircraft lightweighting trends continue to accelerate globally.
By End-User, Automotive dominates and Electrical & Electronics grows fastest
The automotive application continues to be the leading end user segment in the Metal Cleaning Chemicals Market due to the consistent need for such metal cleaning and surface preparation chemicals in the production of vehicles. This is attributed to the high volume of vehicle production worldwide and the pre-existing relationship between the metal cleaning chemical producers and automobile producers.
Application in the Electrical & Electronics category is expected to become the fastest growing end-user application area due to the rising requirement for clean metal surfaces in semiconductor manufacturing, circuit board manufacturing and electronic components manufacturing operations, which demand very high levels of surface cleanliness. This end-user application area is based on the use of high purity cleaning fluids for electronics component manufacturing.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
44.60% |
|
North America |
United States |
85.50% |
|
Europe |
Germany |
34.60% |
|
Latin America |
Brazil |
38.60% |
|
Middle East & Africa |
United Arab Emirates |
34.60% |
Asia Pacific Metal Cleaning Chemicals Market Insights
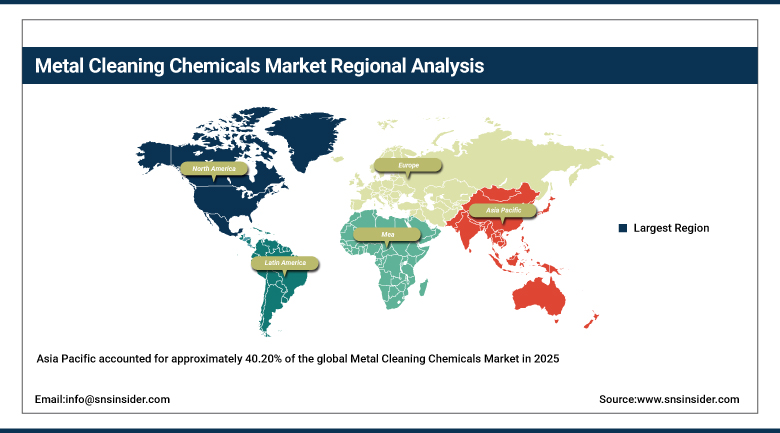
Asia Pacific accounted for approximately 40.20% of the global Metal Cleaning Chemicals Market in 2025 and is also projected to expand at the fastest pace at a CAGR of approximately 5.18% during the 2026-2035 forecast period, supported by the region's massive manufacturing and automotive production base. China represents the largest single contributor within the region, supported by its extensive steel production capacity and dense network of automotive and industrial component manufacturers.
India and Japan provide significant additional regional demand, with India aided by the existing infrastructure investment driving steel pickling solution demand, and Japan aided by their experience in the manufacture of surface treatment and plating chemicals. Regional manufacturing capacity increases add further to the importance of Asia Pacific as the largest and fastest-growing market for metal cleaning chemicals worldwide.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Metal Cleaning Chemicals Market Insights
North America represents a significant regional market for metal cleaning chemicals, anchored by the United States' substantial automotive, manufacturing, and aerospace industries. The United States accounts for the substantial majority of regional demand, reflecting both its industrial manufacturing scale and its concentration of leading specialty chemical companies.
Another factor contributing to regional market growth is that Canada provide regional volume through cross-border automotive and industrial manufacturing supply chains. Domestic infrastructure investment to support steel pickling solution demand continues to drive regional market growth.
Europe Metal Cleaning Chemicals Market Insights
Europe represents a significant regional market for metal cleaning chemicals, owing to the considerable presence of manufacturing companies in Germany. The German share of the regional market is influenced not only by the country’s share in regional manufacturing but also by the fact that the country is home to many specialty chemical companies.
Other countries in Europe that generate regional demand include France and Italy due to the presence of automotive and manufacturing industries. Environmental sustainability and workplace safety regulations prevalent in Europe contribute to consistent regional demand.
MEA & Latin America Metal Cleaning Chemicals Market Insights
Latin America's Metal Cleaning Chemicals Market is led by Brazil, which accounts for the majority of regional demand on the strength of its substantial domestic automotive and industrial manufacturing sector. Gradual growth in domestic manufacturing production continues to support steady regional market development.
There is an ongoing rise in the strategic importance of the Middle East & Africa region, with the demand being focused in Gulf Cooperation Council countries including the UAE, with rising investments in industries as well as the mining sector leading to rising demand for specialty metal cleaners and processors. South Africa remains the dominant demand driver in Africa, owing to the more developed mining and industrial infrastructure in the country.
Growth Drivers: Manufacturing Expansion and Sustainable Formulation Demand
The growing manufacturing and automobile industry is what drives the Metal Cleaning Chemicals Market, as the need for metal cleaning chemicals is still very important to ensure that the metal parts of the vehicles, machines, and buildings maintain good quality finishing and functioning. This trend is further fueled by the move towards sustainable and eco-friendly metal cleaning chemicals, as the aqueous cleaning chemicals continue to be in demand.
New regeneration technologies that reclaim free acid and remove iron salts provide an additional significant source of demand, as these innovations dramatically reduce sludge output while improving overall process economics. Increasing importance of advanced chemistries meeting quality, safety, and sustainability expectations across industrial and high-precision sectors further supports market growth.
Restraints: Regulatory Compliance Costs and Raw Material Volatility
The stringent nature of regulations relating to environmental sustainability and employee safety presents itself as an important constraint within the Metal Cleaning Chemicals Market since there is a constant need for companies to keep on revising their products as per the changing regulations in different regions. This situation is further aggravated by the fact that changing from traditional solvent-based products to aqueous products is technically difficult.
Continued raw material cost volatility for specialty surfactants, chelating agents, and acid-based inputs adds uncertainty to long-term manufacturing cost and pricing planning across the industry. Intense competition among established manufacturers and emerging regional players continues to pressure pricing, particularly in commoditized product categories.
Opportunities: Regeneration Technology Adoption and Lightweight Metal Processing Expansion
The consistent use of acid regeneration equipment will create a significant growth potential for the Metal Cleaning Chemicals Market, owing to the fact that such equipment helps to significantly reduce waste production while at the same time increasing the efficiency of the process. The companies that will manage to validate their regeneration technology will be in a good position to capture market share.
Rising demand for specialized aluminum and light alloy cleaning chemistries presents a longer-term opportunity for suppliers to extend their product portfolios beyond traditional steel-focused formulations. As automotive and aerospace lightweighting trends continue to accelerate, suppliers with established lightweight metal cleaning expertise are positioned to capture a disproportionate share of this emerging demand.
Recent Developments
- 2025: BASF Mining Solutions and FUCHS entered a cooperation agreement in Australia to strengthen specialty chemical offerings and technical support for mining and metal processing customers.
- 2026: Evonik expanded its metal-cleaning portfolio with sustainable surfactants and specialties supporting low-temperature, low-VOC, immersion, spray, scrub, and ultrasonic cleaning processes.
- 2026: Hubbard-Hall promoted AquaEase Infinity membrane technology, designed to extend cleaner bath life, reclaim cleaning chemistry, reduce waste, and lower operating costs.
Metal Cleaning Chemicals Companies are:
- BASF SE
- Evonik Industries AG
- DuPont de Nemours, Inc.
- Eastman Chemical Company
- Stepan Company
- Air Products and Chemicals, Inc.
- Dow Inc.
- Quaker Houghton
- Oxiteno S.A.
- Rochester Midland Corporation
- Hubbard-Hall Inc.
- PCC Chemax, Inc.
- NuGenTec
- Lincoln Chemical Corporation
- KYZEN Corporation
- FUCHS Petrolub SE
- Chemetall GmbH
- Ecolab Inc.
- Henkel AG & Co. KGaA
- The Chemours Company
Metal Cleaning Chemicals Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 16.24 Billion |
| Market Size by 2035 | USD 27.23 Billion |
| CAGR | CAGR of 5.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Acidic Cleaners, Alkaline Cleaners, Neutral Cleaners) • By Form (Aqueous, Solvent, Powder, Gel, Aerosol) • By Metal Type (Steel & Ferrous Alloys, Aluminum & Light Alloys, Copper, Others) • By End-User (Automotive, Manufacturing, Aerospace, Electrical & Electronics, Construction, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | BASF SE, Evonik Industries AG, DuPont de Nemours, Inc., Eastman Chemical Company, Stepan Company, Air Products and Chemicals, Inc., Dow Inc., Quaker Houghton, Oxiteno S.A., Rochester Midland Corporation, Hubbard-Hall Inc., PCC Chemax, Inc., NuGenTec, Lincoln Chemical Corporation, KYZEN Corporation, FUCHS Petrolub SE, Chemetall GmbH, Ecolab Inc., Henkel AG & Co. KGaA, The Chemours Company. |
Frequently Asked Questions
Leading companies in the Metal Cleaning Chemicals Market include BASF, Evonik Industries, DuPont, Eastman Chemical Company, and Quaker Houghton, among others.
Key opportunities include continued adoption of acid regeneration technologies reducing waste generation, and rising demand for specialized aluminum and light alloy cleaning chemistries.
The expanding manufacturing and automotive industries, combined with the shift toward environmentally friendly and sustainable metal cleaning solutions, is the major factor driving market growth.
The Steel & Ferrous Alloys segment dominated the Metal Cleaning Chemicals Market with approximately 44.92% share in 2025.
Asia Pacific dominated the Metal Cleaning Chemicals Market in 2025 with approximately 40.20% share, supported by the region's massive manufacturing and automotive production base, led by China.
