
Microsurgery Market Report Scope & Overview:
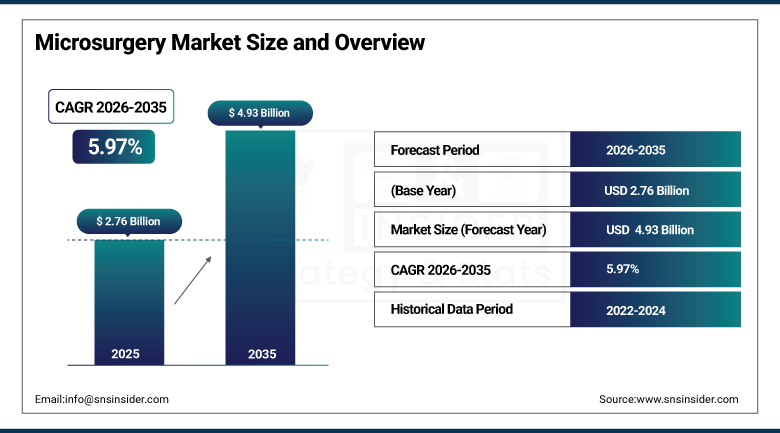
The Microsurgery Market was valued at USD 2.76 Billion in 2025 and is expected to reach USD 4.93 Billion by 2035, growing at a CAGR of 5.97% from 2026-2035.
Microsurgery covers operations performed under magnification with fine instruments and sutures, allowing surgeons to reconnect blood vessels, nerves, and lymphatic channels only a fraction of a millimetre wide. It underpins free flap reconstruction after cancer, limb and digit replantation, lymphatic repair, and delicate neurosurgical and ophthalmic procedures. Demand is supported by rising trauma cases, a growing volume of reconstructive surgery, and the burden of chronic disease and cancer worldwide. Technology is changing the field quickly, with high-definition microscopes, intraoperative imaging, and robotic systems that filter tremor and scale down hand movements. Training shortages and equipment cost remain obstacles, yet steady clinical adoption keeps the market on a stable growth path, and hospital investment in premium visualisation and imaging continues across major centres.
On July 10, 2025, Medical Microinstruments completed the first clinical use of its NanoWrist dissection instruments and the Synaptix Digital Surgery Platform with the Symani Surgical System at The Royal Marsden NHS Foundation Trust in London. The case allowed precise tissue dissection and an integrated digital workflow to be used together in robotic-assisted microsurgery for the first time.
To Get more information On Microsurgery Market - Request Free Sample Report
Microsurgery Market Trends
-
Rising adoption of robotic-assisted platforms that scale movement and filter physiological tremor.
-
Growing use of digital microscopes and intraoperative fluorescence imaging for vessel assessment.
-
Expanding application of supermicrosurgery for lymphatic repair and fine perforator reconstruction.
-
Increasing integration of AI-enabled visualisation and data capture within the operating room.
-
Rising demand for breast and head and neck reconstruction following cancer treatment.
-
Growing efforts to shorten the learning curve through simulation and robotic training programs.
U.S. Microsurgery Market Outlook
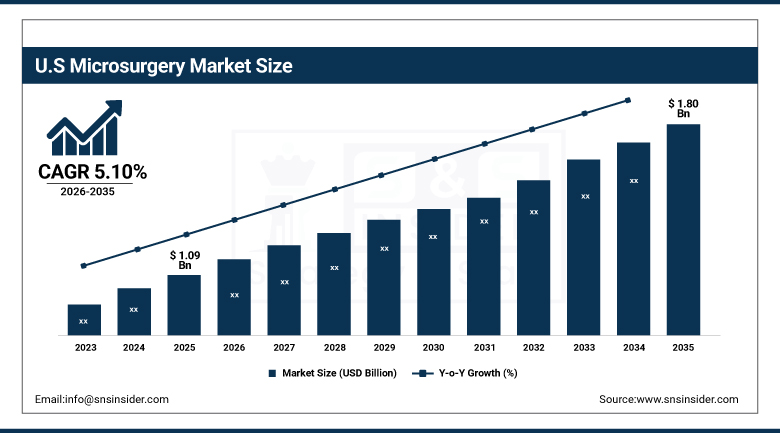
The U.S. Microsurgery Market was valued at USD 1.09 Billion in 2025 and is expected to reach USD 1.80 Billion by 2035, growing at a CAGR of 5.10% from 2026-2035.
The domestic market is the largest national market for microsurgery, backed by a dense network of academic medical centers, a mature reimbursement framework, and the presence of many leading device companies. Hundreds of thousands of microsurgical procedures are performed each year in plastic and reconstructive surgery, neurosurgery, and ophthalmology, and demand from breast cancer reconstruction and lymphatic surgery continues to grow. Hospitals are investing in digital microscopes, exoscopes, and robotic platforms to raise precision and address a shortage of specialised microsurgeons. Federal and private research funding supports clinical trials of new devices, while reimbursement support for selected robotic procedures is improving the economics of adoption. Ambulatory surgical centers are also taking a larger share of suitable reconstructive and hand surgery cases.
On December 9, 2025, Medical Microinstruments received U.S. Food and Drug Administration 510(k) clearance for its NanoWrist Scissors and Forceps, which are indicated for soft tissue dissection. The first U.S. clinical use of the cleared instruments was completed at Tampa General Hospital, extending the Symani system beyond anastomosis into additional steps of complex reconstructive surgery.
Microsurgery Market Segment Analysis
-
By Procedure, the Vascular Anastomoses segment dominated the market with a 31.70% share in 2025, while the Free Flap Tissue Transfer segment is the fastest growing with a CAGR of 7.28% during 2026-2035.
-
By Equipment, the Surgical Microscopes segment dominated the market with a 38.90% share in 2025, while the Robotic-Assisted Systems segment is the fastest growing with a CAGR of 9.35% during 2026-2035.
-
By Application, the Reconstructive & Plastic Surgery segment dominated the market with a 29.60% share in 2025, while the Oncology segment is the fastest growing with a CAGR of 7.12% during 2026-2035.
-
By End-User, the Hospitals & Clinics segment dominated the market with a 58.40% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of 7.35% during 2026-2035.
By Procedure, Vascular Anastomoses Dominates the Market and Free Flap Tissue Transfer Grows Fastest
Vascular anastomosis dominated the market in 2025. Reconnecting small arteries and veins is the technical core of nearly every microsurgical operation, from free tissue transfer to replantation and transplantation, so the procedure sits beneath much of the demand for microscopes, fine instruments, and micro-sutures. Its use spans specialties and care settings, and improvements in coupling devices and suture technology continue to support consistent volumes. Because success depends on precise vessel closure, hospitals invest steadily in the equipment and training that make reliable anastomosis possible.
Free flap tissue transfer is expected to be the fastest-growing procedure over the forecast period. Moving skin, muscle, or bone with its own blood supply from one part of the body to another is increasingly common after cancer resection, trauma, and burns. Breast reconstruction after mastectomy and head and neck reconstruction are major drivers, and growing patient awareness of reconstructive options is adding volume. Advances in perforator flap techniques and imaging are widening eligibility while reducing donor site morbidity.
By Equipment, Surgical Microscopes Dominates the Market and Robotic-Assisted Systems Grows Fastest
Surgical microscopes dominated the market in 2025. They are the indispensable visualisation tool for every microsurgical discipline and represent a large capital purchase for hospitals and specialty clinics. Manufacturers continue to add motorised positioning, integrated fluorescence, and high-definition camera systems, which encourage replacement of older units. Sales are supported by neurosurgery, ophthalmology, and plastic surgery departments that rely on them for every case, giving the category a broad and stable installed base.
Robotic-assisted systems are projected to be the fastest-growing equipment category over the forecast period. Purpose-built platforms with wristed micro-instruments can scale surgeon hand movements, remove tremor, and make it feasible to operate on vessels below one millimetre. Regulatory clearances for these platforms in the United States and Europe are opening the door to commercial rollout, and centres are beginning to build dedicated robotic microsurgery programs. As clinical evidence and reimbursement support develop, this category is expected to expand far faster than conventional equipment.
By Application, Reconstructive & Plastic Surgery Dominates the Market and Oncology Grows Fastest
Reconstructive and plastic surgery dominated the market in 2025. Breast, limb, head and neck, and trauma reconstruction all rely on microvascular techniques, and the number of such procedures has grown alongside cancer survivorship and public interest in restorative surgery. Cosmetic and aesthetic surgery volumes have also risen, adding to overall demand for microsurgical tools. Specialised centres of excellence concentrate expertise and equipment, which reinforces the category's leading position.
Oncology is expected to be the fastest-growing application over the forecast period. Surgeons increasingly combine tumour removal with immediate microsurgical reconstruction to preserve function and appearance, and lymphatic procedures to treat swelling after cancer therapy are gaining acceptance. The rising incidence of cancer, particularly in ageing populations, is enlarging the patient base. Improved imaging and robotic assistance are also making complex oncologic reconstruction more reliable and more widely available.
By End-User, Hospitals & Clinics Dominates the Market and Ambulatory Surgical Centers Grows Fastest
Hospitals and clinics dominated the market in 2025. They perform the complex, long-duration operations that microsurgery involves and have the multidisciplinary teams, intensive care support, and capital budgets required for high-end microscopes and robotic systems. Academic medical centres in particular act as hubs for training and clinical research, and their purchasing decisions influence adoption across the wider market. The severity of trauma and cancer cases keeps most procedures within the hospital setting.
Ambulatory surgical centers are projected to be the fastest-growing end-user category over the forecast period. Hand surgery, nerve repair, and selected reconstructive cases can be managed safely on an outpatient basis, and payers favour the lower cost of these facilities. Centers are investing in modern microscopes and instrument sets to attract surgeons, and specialised plastic surgery groups are opening their own facilities. This shift is expected to widen the customer base for compact and cost-efficient microsurgical systems.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
88.60% |
|
Europe |
Germany |
28.10% |
|
Asia Pacific |
China |
36.40% |
|
Latin America |
Brazil |
41.60% |
|
Middle East & Africa |
United Arab Emirates |
22.90% |
North America Microsurgery Market Insights
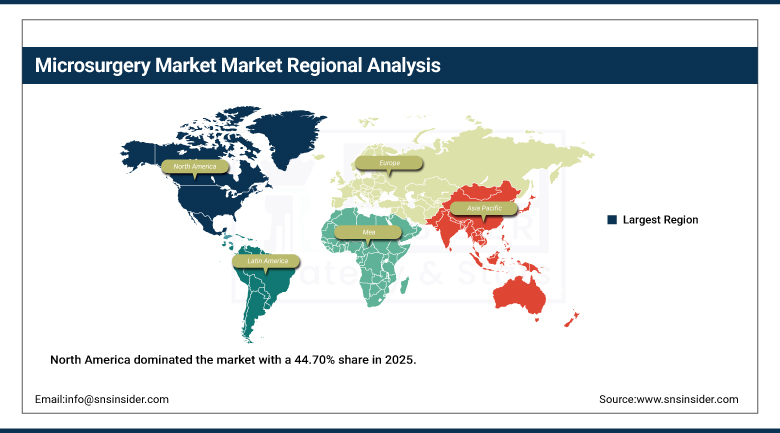
North America dominated the market with a 44.70% share in 2025. A highly developed healthcare system, early adoption of robotic and AI-enabled microsurgery, and a large number of specialised surgical centres underpin the region's lead. Strong research funding and the presence of major device manufacturers speed up clinical validation and commercial launch, while established reimbursement for reconstructive procedures supports steady case volumes.
Canada adds demand through its academic hospitals and publicly funded reconstructive programs. Continued investment in digital visualisation, robotic platforms, and training is expected to keep North America ahead through the forecast period, although growth in percentage terms will trail faster-scaling Asia Pacific markets that are still building microsurgical capacity from a smaller base.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Microsurgery Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 7.60% during 2026-2035. A rising share of elderly people, growing trauma caseloads, expanding cancer care, and rapid hospital construction are increasing the need for microsurgical services. Governments are funding tertiary care centres and surgical training, and medical tourism in several countries is adding demand for reconstructive and cosmetic procedures.
China anchors regional demand through its large hospital sector and growing domestic device industry. Japan has a long tradition of microsurgery, including pioneering work in lymphatic surgery, and continues to adopt advanced instruments and microscopes. India and South Korea add strong growth as private hospital groups expand and surgeons seek modern equipment. Local manufacturers are broadening access with lower-priced microscopes and instruments.
Europe Microsurgery Market Insights
Europe holds a significant share of the global market, supported by well-organised public health systems, a strong base of academic microsurgery training, and leading manufacturers of surgical microscopes and precision instruments. Germany anchors regional demand with its large hospital network and its role as a home to major optics and medical technology companies, while regional expertise in supermicrosurgery keeps clinical standards high.
The United Kingdom, France, and Italy add consistent demand, with reconstructive centres growing in size and scope. Italy is also the base for a prominent robotic microsurgery developer, and European hospitals have been among the first to use these systems clinically. Stricter device regulation raises development costs but reinforces confidence in approved products.
MEA & Latin America Microsurgery Market Insights
The Middle East & Africa region is supported by growing healthcare investment in the United Arab Emirates and Saudi Arabia, where new tertiary hospitals and specialist centres are adding microsurgical capability. Trauma volumes and rising cancer incidence are widening demand, and governments are encouraging local training to reduce reliance on treatment abroad.
Latin America is anchored by Brazil, which has a strong tradition of plastic and reconstructive surgery and a large private hospital sector. Mexico adds further growth through medical tourism and expanding private care. Budget constraints in public systems limit purchases of high-end equipment, but demand for refurbished and mid-range microscopes remains healthy.
Market Dynamics
Growth Drivers: Trauma, Cancer, and Reconstructive Surgery Demand
Rising trauma cases, cancer incidence, and chronic disease-related surgical needs are the primary growth drivers. Road accidents, industrial injuries, and sports trauma produce limb and digit injuries that require replantation and free tissue transfer, while cancer resection creates defects that surgeons increasingly repair with microvascular flaps. A growing elderly population adds further demand for reconstruction and vascular procedures.
Technological advances are a second major driver. High-definition microscopes, intraoperative imaging, exoscopes, and robotic platforms are improving precision and enabling operations on smaller vessels than ever before. Growing preference for minimally invasive approaches, together with rising patient awareness of reconstructive options, sustains demand for modern microsurgical equipment across both developed and emerging health systems.
Restraints: High Equipment Costs and Skill Shortages
High cost of equipment and its implementation is a notable limitation for the development of the microsurgery market. Advanced surgical microscopes, robotic surgery systems, high precision instruments used for microsurgical procedures, visualization and operating equipment demand heavy initial investments. Moreover, healthcare organizations need to allocate resources for regular expenses related to maintenance of equipment, software updates, equipment calibration, training of medical staff and single-use microsurgical instruments. This issue is especially relevant for small hospitals, ASCs and publicly funded health care organizations working with tight budgets. It becomes even more difficult to finance technological innovations in emerging countries where the expenditure on health care infrastructure is limited and some surgical procedures may lack proper reimbursement.
As a result, many healthcare facilities keep using their equipment longer and do not update technology which results in lower penetration rate of advanced microsurgical solutions. A shortage of trained microsurgeons is a further constraint. The discipline demands years of specialised training and steady practice, and many regions have too few experienced surgeons to meet demand. This limits case volumes and concentrates procedures in a small number of centres, although simulation training and robotic assistance are starting to shorten the learning curve. Developing proficiency in vascular anastomosis, nerve repair, tissue transfer, replantation, and other complex techniques can require several years, creating a relatively limited pool of qualified specialists
Opportunities: Robotic Microsurgery and Supermicrosurgery Expansion
Robotic microsurgery is a substantial opportunity. Platforms that scale motion and remove tremor could allow more surgeons to perform delicate anastomoses and extend the field into procedures that human hands cannot reliably perform. Companies that secure clearances, build clinical evidence, and win reimbursement stand to open a new category of high-value procedures.
Expansion of lymphatic surgery and neurosurgical applications offers a further avenue for growth. Surgical treatment of lymphedema is gaining acceptance, and early clinical studies are exploring microsurgical techniques in neurological conditions. Emerging markets also offer headroom as hospital capacity and surgical training expand, supporting demand for both premium and mid-range equipment.
Recent Developments:
-
2024: Medical Microinstruments raised a USD 110 million Series C financing round to fund the rollout of its Symani robotic microsurgery system.
-
2024: the U.S. Food and Drug Administration granted de novo clearance for the Symani Surgical System, making it the first commercially available robotic platform for reconstructive microsurgery in the country.
-
2026: Medical Microinstruments announced completion of the first robotic-assisted procedure in REMIND, a U.S. study of its Symani system in patients with Alzheimer's disease.
-
2026: the Symani Surgical System won the top award in the Health, Medical and Biotech category of the Edison Awards.
Microsurgery Market Key Players are
-
Leica Microsystems (Danaher Corporation)
-
Stryker Corporation
-
Medtronic plc
-
Johnson & Johnson (Ethicon)
-
B. Braun Melsungen AG
-
Mitaka Kohki Co., Ltd.
-
Synaptive Medical Inc.
-
Haag-Streit Group
-
Alcon Inc.
-
Karl Storz SE & Co. KG
-
Accurate Surgical & Scientific Instruments Corporation
-
Moller-Wedel GmbH
-
Medical Microinstruments, Inc.
-
Kaps GmbH & Co. KG
-
Sutter Instrument Company
-
Titan Medical Inc.
-
Scanlan International, Inc.
-
Ellex Medical Lasers Ltd.
Microsurgery Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.76 Billion |
| Market Size by 2035 | USD 4.93 Billion |
| CAGR | CAGR of 5.97% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Procedure (Vascular Anastomoses, Free Flap Tissue Transfer, Transplantation, Replantation, Others) • By Equipment (Surgical Microscopes, Microsurgical Instruments, Robotic-Assisted Systems, Suture Materials) • By Application (Reconstructive & Plastic Surgery, Neurosurgery, Ophthalmology, General Surgery, Oncology, Others) • By End-User (Hospitals & Clinics, Ambulatory Surgical Centers, Research Organizations, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Carl Zeiss Meditec AG, Leica Microsystems (Danaher Corporation), Olympus Corporation, Stryker Corporation, Medtronic plc, Johnson & Johnson (Ethicon), B. Braun Melsungen AG, Mitaka Kohki Co., Ltd., Synaptive Medical Inc., Haag-Streit Group, Alcon Inc., Karl Storz SE & Co. KG, Accurate Surgical & Scientific Instruments Corporation, Moller-Wedel GmbH, Medical Microinstruments, Inc., Kaps GmbH & Co. KG, Sutter Instrument Company, Titan Medical Inc., Scanlan International, Inc., Ellex Medical Lasers Ltd. |
Frequently Asked Questions
Key players include Carl Zeiss Meditec AG, Leica Microsystems, Olympus Corporation, Stryker Corporation, Medtronic plc, and B. Braun Melsungen AG, among other medical technology companies.
Development of robotic microsurgery platforms and expansion of lymphatic and neurosurgical applications represent the primary opportunities for manufacturers.
Growth is primarily driven by rising trauma, cancer, and reconstructive surgery volumes, together with advances in visualisation and robotic technology.
By Procedure, Vascular Anastomoses dominated the market with a 31.70% share in 2025, reflecting their central role in nearly every microsurgical operation.
North America dominated the market with a 44.70% share in 2025, supported by advanced healthcare infrastructure and early adoption of robotic technology.
