
MPLS IP VPN Market Report Scope & Overview:
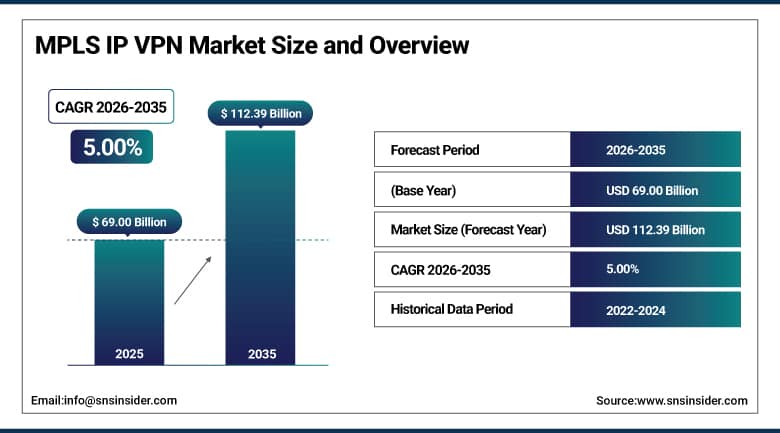
The MPLS IP VPN Market was valued at USD 69.00 Billion in 2025 and is estimated at USD 72.45 Billion in 2026. The market is projected to reach USD 112.39 Billion by 2035, expanding at a CAGR of 5.00% from 2026 to 2035. MPLS IP VPN services are carrier-operated private networks that connect branch offices, data centers, and cloud gateways using label-switched routing with guaranteed performance, and they are sold as managed services with service level agreements. Growth is moderate because hybrid designs keep these circuits for critical traffic while other traffic moves to broadband and software-defined overlays.
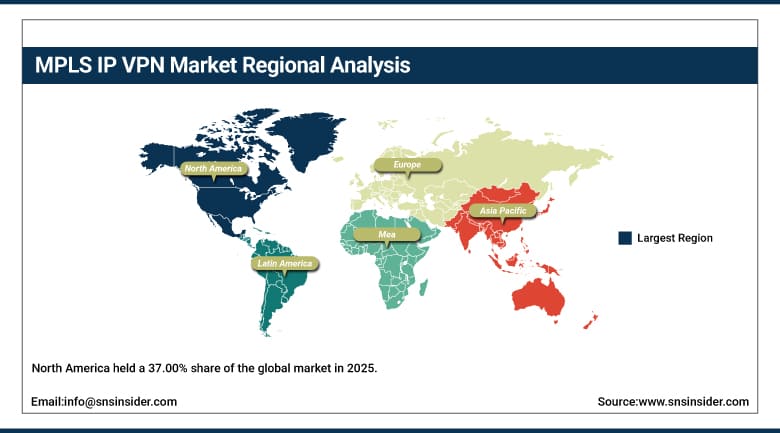
North America was the largest regional market in 2025, with a 37.00% share. The region has the largest base of multi-site enterprises, financial institutions, and carriers that sell managed private networks, and buyers favor service level guarantees. Europe follows, supported by cross-border corporate networks and regulated industries, while Asia Pacific is the fastest-growing region, supported by expanding enterprise networks in India, Southeast Asia, and China, where licensed carriers carry cross-border traffic. Latin America and the Middle East & Africa are smaller but are widening steadily. Together these regions form a stable base of contracted revenue.
To Get More Information On MPLS IP VPN Market - Request Free Sample Report
Key Report Takeaways
- By service type, Layer 3 VPN held a 67.50% share in 2025, while Layer 2 VPN is the fastest growing.
- By service model, managed services held a 63.40% share in 2025, while co-managed hybrid is the fastest growing.
- By organization size, large enterprises held a 74.50% share in 2025, while small and medium enterprises are the fastest growing.
- By end user, IT and telecom held a 31.20% share in 2025, while education is the fastest growing.
- By region, North America held a 37.00% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Hybrid wide area networks are becoming the norm. Enterprises keep private circuits for voice, financial, and industrial traffic that needs guaranteed performance, and they add broadband and software-defined overlays for cloud and branch traffic.
Carriers are bundling private connectivity with managed software-defined networking and secure access services. A single contract and portal now cover circuits, overlays, and security policy, which keeps carriers in control of the customer relationship.
Consolidation and asset sales are reshaping supplier lines. Carriers are combining enterprise units, selling consumer fiber assets, and exiting weaker regions, so large multinational buyers deal with fewer, larger providers.
Automation is lowering operating cost. Intent-based provisioning, network analytics, and artificial intelligence for operations help providers shorten delivery times and detect faults before customers do.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
SLA-Backed Private Connectivity for Critical Traffic |
+2.18% |
Global |
Long term (4 years or more) |
|
Hybrid WAN Architectures |
+1.82% |
North America, Europe |
Medium term (2 to 4 years) |
|
Cloud On-Ramps and Network-as-a-Service |
+1.46% |
Global |
Medium term (2 to 4 years) |
|
Regulated Sector and Data Residency Requirements |
+1.21% |
Europe, Asia Pacific |
Long term (4 years or more) |
|
Carrier Consolidation and Managed Service Bundling |
+0.94% |
North America, Europe |
Short term (2 years or less) |
|
Emerging Market Enterprise Expansion |
+0.78% |
Asia Pacific, Latin America |
Long term (4 years or more) |
SLA-Backed Private Connectivity for Critical Traffic
Banks, hospitals, utilities, and manufacturers run applications that cannot tolerate variable latency, packet loss, or public internet exposure, and they need contractual service levels with fault repair commitments. MPLS IP VPN services provide traffic classes, predictable performance, and carrier-managed routing across many sites and countries. Voice, payment, trading, and industrial control traffic remain on private circuits, and risk managers value a single accountable supplier, which keeps demand steady even as less demanding traffic moves elsewhere. Audit trails also help. Costs stay predictable.
Hybrid WAN Architectures
Most large enterprises do not replace private circuits outright but combine them with broadband links and software-defined overlays. The private core carries traffic that needs guarantees, while internet links carry cloud and web traffic, and an overlay selects the path for each application. Carriers sell these hybrid designs as managed services that include the MPLS core, which preserves revenue and supports renewals, and network teams choose the arrangement because it lowers total cost while limiting migration risk. Renewal rates remain high.
Cloud On-Ramps and Network-as-a-Service
Providers are connecting private networks directly to major cloud platforms, data centers, and internet exchanges, and they offer on-demand bandwidth and self-service portals. Enterprises use these on-ramps to reach cloud applications with consistent performance and to avoid exposing sensitive traffic to the public internet. Network-as-a-service pricing lets buyers scale capacity quickly, and it helps carriers modernize older private networks and keep customers who might otherwise leave for pure internet services. Direct interconnects also reduce egress fees and security exposure for enterprises.
Regulated Sector and Data Residency Requirements
Financial supervisors, health authorities, and public agencies require secure, auditable networks and sometimes require that traffic stay within national boundaries. Private carrier networks meet many of these rules with documented controls, and in some countries cross-border corporate traffic may legally pass only through licensed carriers. Data protection laws and sector guidance push institutions toward private connectivity for sensitive applications, which creates a stable base of long-term contracts. Auditors accept carrier attestations as evidence, which shortens approval cycles for new connections and encourages institutions to renew contracts.
Carrier Consolidation and Managed Service Bundling
Carriers are combining enterprise units, selling non-core assets, and concentrating on managed services, which creates larger providers with broader reach and stronger bargaining power with access suppliers. Bundled contracts that combine private circuits, software-defined overlays, security services, and monitoring are attractive to multinational buyers who want to reduce the number of suppliers. Consolidation also funds investment in automation and platforms that improve delivery times. Larger scale also improves buying power with equipment makers and allows carriers to offer global coverage through one contract and one portal.
Emerging Market Enterprise Expansion
Companies in India, Southeast Asia, Latin America, and the Gulf are opening branches, factories, data centers, and retail outlets, and they need dependable connectivity between sites where public internet quality varies. Private network services give these firms predictable performance and local support, and carriers there are extending coverage to new cities. Growing financial inclusion, e-commerce logistics, and industrial investment add sites and bandwidth, which supports demand in markets that are still building enterprise networks. Local partners help carriers reach mid-sized firms.
Restraints Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Migration to SD-WAN and Direct Internet Access |
-2.74% |
Global |
Short term (2 years or less) |
|
Legacy Access Retirement and Carrier Divestitures |
-1.68% |
North America, Europe |
Medium term (2 to 4 years) |
|
Bandwidth Price Erosion |
-1.32% |
Global |
Medium term (2 to 4 years) |
|
Convergence with SASE and Cloud Security Services |
-0.96% |
Global |
Long term (4 years or more) |
Migration to SD-WAN and Direct Internet Access
Enterprise surveys show that the share of sites connected by MPLS has fallen sharply over several years, while direct internet access and software-defined networking have grown quickly. Cloud applications make backhauling traffic through a private core inefficient, and broadband prices are far lower per unit of capacity. Network teams therefore reduce circuit counts at renewal, move branches to internet links, and negotiate lower contract values, which slows revenue growth even where customer numbers remain stable. Competition from internet providers intensifies.
Legacy Access Retirement and Carrier Divestitures
Regulators in several regions are easing the process for retiring copper and time-division multiplexing networks, and carriers are shutting down legacy access that supports older private circuits. Customers must migrate to fiber or Ethernet access, which adds cost and complexity, and some choose this moment to switch to internet-based services. Carriers are also selling or exiting parts of their enterprise portfolios, which creates uncertainty for buyers and reduces the number of suppliers with full coverage. Transition projects take many months.
Bandwidth Price Erosion
The price per megabit of enterprise connectivity continues to decline as fiber coverage grows and competition increases among wholesale and retail suppliers. Buyers benchmark private circuit prices against internet and Ethernet services and ask for discounts at every renewal. Higher capacity at lower cost lets customers keep spending flat while receiving more bandwidth, so revenue grows more slowly than traffic, and carriers must find new managed services to offset the decline. Smaller carriers face the sharpest margin pressure from this trend.
Convergence with SASE and Cloud Security Services
Security and networking are being combined into cloud-delivered secure access services that apply policy at the edge and in the cloud rather than inside a private core. Vendors of these services sell directly to security teams, and the buying decision moves away from the network group that has traditionally purchased carrier circuits. Carriers respond with their own bundles, but the shift reduces the strategic role of private networks in new architecture designs. Procurement teams are also merging network and security budgets.
MPLS IP VPN Market Segment Analysis
By Service Type, Layer 3 VPN Dominates MPLS IP VPN Market; Layer 2 VPN to Register Fastest Growth.
Layer 3 VPN held 67.50% of the market in 2025. The service routes customer traffic through the provider network using customer-specific routing tables, which lets carriers manage addressing, traffic classes, and any-to-any connectivity across many sites. Large enterprises prefer it because the provider operates the routing and enforces service levels. It suits mixed voice, video, and application traffic, and it remains the standard offer in carrier catalogs worldwide. Enterprises also value the detailed traffic reporting that comes with it.
Layer 2 VPN is projected to expand at a CAGR of 6.20% from 2026 to 2035. These services extend Ethernet networks between sites and data centers, give customers control of their own routing, and support latency-sensitive storage and disaster recovery links. Demand rises with data center interconnection, cloud connectivity, and financial networks that need transparent transport. Carriers increasingly sell Ethernet-based private networks as a modern alternative to older circuits. Providers also bundle it with managed backup links. Pricing is predictable.
By Service Model, Managed Services Dominate MPLS IP VPN Market; Co-Managed Hybrid to Register Fastest Growth.
Managed services held 63.40% of the market in 2025. The carrier designs, provisions, monitors, and repairs the network, including routers at customer sites, and offers reporting and service level credits. Enterprises with small network teams prefer to outsource operations to a single supplier, and global organizations value one contract covering many countries. Packaged managed services also include security and cloud connectivity options that raise revenue per customer. Customers rely on a single help desk for faults. Reports are detailed.
Co-managed hybrid is forecast to grow at a CAGR of 6.90% over 2026 to 2035. In this model the carrier runs the private core and the customer or a partner controls overlay policies, internet links, and security tools through shared portals. It suits organizations that want flexibility without giving up service levels. Growth is supported by managed software-defined networking offers that include the private core as one transport option. This arrangement lets customers adjust policies themselves. Portals show live status.
By Organization Size, Large Enterprises Dominate MPLS IP VPN Market; Small and Medium Enterprises to Register Fastest Growth.
Large enterprises accounted for 74.50% of the market in 2025. They operate hundreds or thousands of sites, run global applications, and carry voice, payment, and industrial traffic that requires guaranteed performance. Their contracts are multi-year, multi-country, and often include managed security and cloud connectivity. Procurement teams negotiate large bundles with a few global carriers, and the scale of their networks keeps spending well above that of smaller firms. Banks, manufacturers, and retailers account for much of this demand.
Small and medium enterprises are projected to expand at a CAGR of 6.80% from 2026 to 2035. Carriers now offer packaged private network services with standard bandwidth tiers, portals, and bundled internet backup, which lowers entry cost and complexity. Growing multi-site businesses in logistics, retail, and professional services adopt these offers to connect branches and cloud applications reliably, while resellers and managed service partners extend reach. Payment terminals, point-of-sale systems, and warehouse scanners all benefit from reliable links.
By End User, IT and Telecom Dominates MPLS IP VPN Market; Education to Register Fastest Growth.
IT and telecom accounted for 31.20% of the market in 2025. Technology companies, outsourcing providers, and carriers themselves operate large distributed networks that link offices, delivery centers, and data centers, and they buy private connectivity for service delivery and for resale to customers. Round-the-clock operations, strict uptime commitments, and a high share of international traffic keep spending strong in this segment, which also acts as an early adopter of new service features. Cloud migration adds more interconnects. Uptime is critical.
Education is projected to expand at a CAGR of 7.50% from 2026 to 2035. Universities, school districts, and research networks are connecting campuses, laboratories, and remote learning platforms, and public funding for digital infrastructure supports new circuits. Demand for secure access to research data, online examinations, and administrative systems adds sites and bandwidth, while consortium purchasing lowers prices. Growth in online degree programs adds bandwidth demand across rural and urban campuses, and research funding supports high-capacity links between universities.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
89.00% |
|
Europe |
United Kingdom |
27.00% |
|
Asia Pacific |
China |
33.50% |
|
Middle East & Africa |
Saudi Arabia |
26.50% |
|
Latin America |
Brazil |
41.60% |
North America MPLS IP VPN Market
North America held a 37.00% share of the global market in 2025. The United States market was valued at USD 22.72 Billion in 2025 and is projected to grow at a CAGR of 4.60% from 2026 to 2035. The region has the largest base of multi-site enterprises, banks, and carriers. The Federal Communications Commission released a report and order in March 2026 that modernizes network change rules, ends public notice for many copper retirements, and sets a 31-day automatic grant for discontinuance applications.
Wireline Competition Bureau orders in 2025 had already streamlined copper retirement procedures, and the new rules speed the retirement of legacy access that supports older private circuits. Carriers are selling consumer fiber and focusing on business services, and enterprises are migrating branches to fiber and Ethernet access. Canada adds demand through its financial sector, while Mexico is covered under Latin America in this study. Large banks and healthcare networks in the United States remain among the biggest buyers of managed private connectivity and are renewing multi-year agreements.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe MPLS IP VPN Market
Europe held a 27.60% share of the global market in 2025, with the United Kingdom as the leading country, followed by Germany, France, Italy, and Spain. In January 2026, the European Commission published its proposal for a Digital Networks Act, which would create a single authorisation for operators across the Union, harmonize rules that now vary by country, and set a mandatory copper switch-off after 2035. National regulators currently apply different authorisation rules, which adds cost for multinational carriers serving customers in several markets.
The Telecoms Access Review of Ofcom for 2026 to 2031 took effect in April 2026 and sets regulated access to leased lines and dark fibre in different parts of the United Kingdom, which shapes the price of Ethernet and private network access. Multinational banks, manufacturers, and public bodies in Germany and France keep large private networks, and providers are bundling them with software-defined overlays. Public sector networks in Nordic countries also buy large framework agreements for secure connectivity, and procurement is increasingly national.
Asia Pacific MPLS IP VPN Market
Asia Pacific accounted for 23.40% of the global market in 2025 and is the fastest-growing region, with a projected CAGR of 7.10% from 2026 to 2035. China is the leading country, followed by India, Japan, South Korea, and Australia. China requires cross-border enterprise connectivity to run through licensed carriers, and the Ministry of Industry and Information Technology announced approvals for 166 foreign-invested telecom enterprises in June 2026 under pilot zones in Beijing, Shanghai, Hainan, and Shenzhen. Japan hosts large enterprise networks.
In India, directions issued in 2022 by the national computer emergency response team require VPN providers and data centers to keep logs for five years and report incidents within six hours, and the electronics and information technology ministry ordered VPN providers in April 2026 to block banned gambling platforms. Enterprise networks in India and Southeast Asia are growing quickly as banks, outsourcers, and manufacturers add sites. Australia and Singapore are mature markets where carriers migrate customers from legacy circuits to managed hybrid services.
Latin America MPLS IP VPN Market
Latin America is a smaller regional market, led by Brazil, followed by Mexico, Argentina, and Chile. The national telecommunications agency of Brazil, Anatel, approved a revised regulatory agenda for 2025 and 2026 in February 2026 that covers submarine cable rules, network sharing, and quality regulations. Banks, retailers, and mining and energy companies in the region depend on private carrier networks for branch and plant connectivity. Regional carriers also supply managed circuits to government and utility networks, and demand is stable because many branches lack alternative dependable links in smaller cities.
Large carriers and regional operators sell managed private networks together with internet access and cloud connectivity, and demand is rising as retailers, logistics firms, and public agencies expand digital services. Mexico, Colombia, and Chile are expanding fiber coverage, which lowers access cost for enterprise sites. Multinational companies with regional hubs in Sao Paulo and Mexico City often buy global contracts from international carriers. Mining, oil, and agricultural firms in Chile, Peru, and Brazil operate remote sites where private links and satellite backup remain important.
Middle East & Africa MPLS IP VPN Market
The Middle East & Africa region holds a 5.80% share and is expected to grow steadily from a small base. Saudi Arabia, the United Arab Emirates, Turkey, Israel, and South Africa are the main markets. Saudi Arabia operates a communications regulator that licenses regulated services, and the compliance period under the personal data protection law ended in September 2024, so organizations now keep tighter control over cross-border transfer of personal data. Government digital programs also drive demand. Adoption is still early.
In the United Arab Emirates, regulators have long allowed companies and banks to use virtual private networks for internal access, with licensed carriers providing the services. Large government programs, financial centers, and energy companies in the Gulf buy managed private networks, while South Africa, Nigeria, and Kenya are building enterprise connectivity around data centers and submarine cable landings. Telecommunications operators in the Gulf sell managed networks to banks, airlines, and hospitality groups, and data center growth in Riyadh, Dubai, and Johannesburg adds interconnection demand.
Competitive Landscape
The MPLS IP VPN Market is moderately concentrated. AT&T, Verizon, and Lumen Technologies lead in North America, while BT Group, Orange Business, Vodafone Business, Colt Technology Services, and Deutsche Telekom lead in Europe. NTT, Tata Communications, Telstra, Singtel, and China Telecom lead across Asia Pacific, and GTT serve enterprises with fiber and managed services. HPE supply the routing and software-defined platforms used in carrier networks. Competition depends on global reach, service quality, bundled security, and price.
Carriers are consolidating, divesting consumer assets, and concentrating on managed services. Providers compete by combining private circuits with software-defined overlays and secure access offers, while regional operators partner with global carriers to serve multinational customers.
MPLS IP VPN Market Industry Leaders
1. AT&T: AT&T Dynamic Exchange, VPN services, and managed network offers for large enterprises.
2. Verizon: Verizon Business private IP, managed network, and global enterprise connectivity.
3. Lumen Technologies: IP VPN, Ethernet, and network-as-a-service offers for business customers.
4. BT Group: BT Business global MPLS, SD-WAN, and managed network services.
5. Orange Business: Evolution Platform with global VPN, SD-WAN, and secure access services.
Companies Covered in this Report
- AT&T
- Verizon
- Lumen Technologies
- BT Group
- Orange Business
- NTT
- Tata Communications
- Vodafone Business
- Colt Technology Services
- Telstra
- Singtel
- China Telecom
- Deutsche Telekom
- GTT Communications
Recent Industry Developments
- January 2026: Verizon announced final regulatory approvals for its acquisition of Frontier Communications.
- February 2026: AT&T closed its USD 5.75 Billion purchase of the Lumen Mass Markets fiber business.
- March 2026: Orange Business partnered with Tech Mahindra to expand its indirect channel for enterprise services.
- June 2026: BT Group and Verizon agreed to combine their international enterprise units in a 50:50 joint venture.
- July 2026: Tata Communications reported first-quarter fiscal 2027 gross revenue growth of 10.50%, or about USD 750.00 Million.
Scope and Research Methodology
This study covers the MPLS IP VPN Market, which includes revenue from carrier-operated private network services that connect enterprise sites, data centers, and cloud gateways using multiprotocol label switching, including Layer 3 and Layer 2 VPN services and their managed and co-managed variants. Associated customer premises equipment and service management are included when sold as part of the service. The base year is 2025, the forecast period is 2026 to 2035, and all values are expressed in USD. The market is segmented by service type, service model, organization size, end user, and region. Consumer VPN applications and standalone SD-WAN software are excluded. Revenue is counted at the level of the carrier or provider that bills the enterprise customer, so wholesale capacity resold by partners is recorded once.
The research program combines secondary and primary research. Secondary research draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, network architects, procurement managers, and end-user stakeholders across the value chain, including carriers, system integrators, and enterprise buyers. These conversations validate assumptions, volumes, and pricing. Interview samples span North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, so differences in migration pace, pricing, and regulation are reflected in the estimates for each segment.
Market engineering follows a bottom-up build from carrier enterprise revenue, circuit counts, and contract values, which is cross-checked top-down against enterprise network spending and telecom service revenue. Triangulation across these views confirms segment and regional estimates. Forecasts consider migration to software-defined and internet-based networks, access technology retirement, regulation, and macroeconomic conditions, and every dataset passes an analyst quality review before it is published. Sensitivity checks cover migration speed, price erosion, and currency rates. Where carriers disclose enterprise revenue, those figures anchor the mix, and remaining gaps are filled through expert estimates tested against several independent sources.
MPLS IP VPN Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 69.00 Billion |
| Market Size by 2035 | USD 112.39 Billion |
| CAGR | CAGR of 5.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Service Type (Layer 3 VPN and Layer 2 VPN) • By Service Model (Managed, Co-Managed Hybrid, and Self-Managed) • By Organization Size (Large Enterprises and Small and Medium Enterprises) • By End User (IT and Telecom, BFSI, Manufacturing, Government and Public Sector, Healthcare, Retail and Consumer Goods, Education, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Verizon, Lumen Technologies, BT Group, Orange Business, NTT, Tata Communications, Vodafone Business, Colt Technology Services, Telstra, Singtel, China Telecom, Deutsche Telekom, GTT Communications |

Frequently Asked Questions
The market was valued at USD 69.00 Billion in 2025 and is estimated at USD 72.45 Billion in 2026. It is projected to reach USD 112.39 Billion by 2035.
The market is projected to grow at a CAGR of 5.00% from 2026 to 2035, as hybrid designs keep private circuits for critical traffic.
North America leads, with a 37.00% share in 2025, owing to the largest base of multi-site enterprises and carriers.
Asia Pacific is the fastest-growing region, with a CAGR of 7.10% from 2026 to 2035, driven by expanding enterprise networks in India, Southeast Asia, and China.
Layer 3 VPN, managed services, large enterprises, and IT and telecom lead their axes. Layer 2 VPN, co-managed hybrid, small and medium enterprises, and education grow fastest.
AT&T, Verizon, Lumen Technologies, BT Group, and Orange Business are among the major players.
Migration to SD-WAN and direct internet access, legacy access retirement, price erosion, and SASE convergence restrain faster growth.
