
NGS-based RNA Sequencing Market Report Scope and Overview
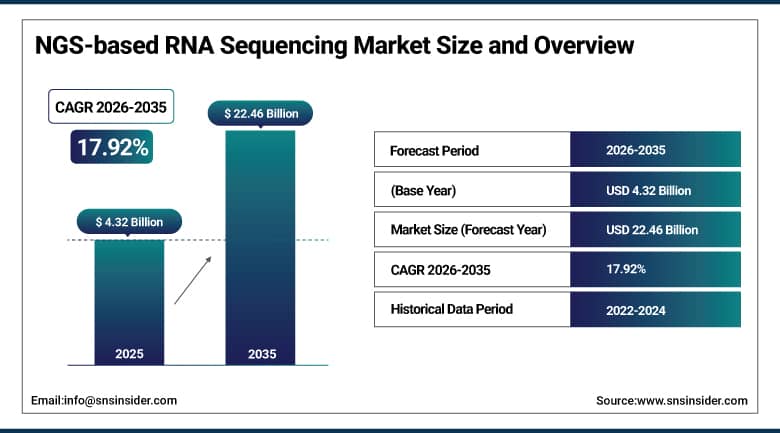
The NGS-based RNA Sequencing Market was valued at USD 4.32 Billion in 2025 and is estimated at USD 5.09 Billion in 2026. The market is forecast to reach USD 22.46 Billion by 2035, registering a CAGR of 17.92% from 2026 to 2035. Growth reflects wider use of transcriptome profiling in drug discovery, rising adoption of single-cell and long-read methods, falling cost per sample, and expanding clinical use in oncology and rare disease. The scope covers sequencing platforms, consumables, sample preparation products, services, and analysis software used for RNA sequencing. Both research and clinical users are included.
To Get More Information On NGS-based RNA Sequencing Market - Request Free Sample Report
Key Market Trends & Insights
- By product and service: RNA-seq platforms and consumables held the largest market share of 53.40% in 2025.
- By technology: Sequencing by synthesis held the largest market share of 57.80% in 2025.
- By application: Drug discovery and development held the largest market share of 52.60% in 2025.
- North America accounted for the largest regional share of 44.60% in 2025.
- Asia Pacific is projected to register the fastest regional CAGR of 19.06% from 2026 to 2035.
- The U.S. is the leading country market, supported by large public research funding, a dense pharmaceutical and biotechnology base, and early adoption of sequencing in clinical care.
Growth Outlook
Regulatory clarity for laboratory-developed tests is supporting clinical adoption. In September 2025, the U.S. Food and Drug Administration issued a final rule rescinding its 2024 rule on laboratory-developed tests, after a federal court vacated the earlier policy. Clinical laboratories can continue to develop and offer RNA-based assays under existing oversight, and this reduces the cost and delay of bringing transcriptome panels to oncology, immunology, and rare disease patients. Test developers are planning new launches on this basis. Hospital laboratories are the main beneficiaries.
Europe is also revisiting device rules that affect in-house testing. In December 2025, the European Commission proposed a simplification of the medical device and in vitro diagnostic regulations, including a broader exception for tests developed and used within health institutions. If adopted, the proposal would lower compliance costs for hospital laboratories that run sequencing-based assays, and it would widen the pool of institutions that can offer RNA sequencing tests to patients. Industry groups have welcomed the proposal, although final adoption depends on the legislative process.
Market Dynamics
Driver: Public Programs and Pharmaceutical Research Expand Transcriptome Sequencing
Public funders are investing in the study of RNA biology. In December 2025, the Office of Strategic Coordination at the National Institutes of Health advanced a concept for an RNomics program that aims to characterize the full set of RNA molecules, including full-length transcripts and chemical modifications. Such programs create demand for long-read and single-cell platforms, high-quality library preparation kits, and analysis software, and they train a new generation of researchers who adopt these methods in academic and clinical laboratories. Funding agencies also support shared sequencing cores and training programs, which spreads access to advanced platforms beyond the largest institutions and builds a steady base of users for kits and services.
Global health bodies are also backing precision medicine. In May 2026, the World Health Assembly endorsed a resolution on precision medicine, which asks the World Health Organization to develop a global strategy on the topic. Governments use such signals to justify funding for genomic and transcriptomic programs, and pharmaceutical firms apply RNA sequencing to target discovery, mechanism studies, and biomarker development. Each additional trial or program creates recurring demand for reagents, sequencing runs, and bioinformatics. Large pharmaceutical sponsors are also building internal single-cell and long-read groups, and partnerships with academic centers give them access to patient cohorts and expertise that speed up the start of new studies.
Restraint: Reimbursement Rules, Data Burden, and Cost of Workflows Limit Clinical Use
The insurance coverage policy plays an important role in determining the pace at which clinical sequencing can be scaled up. In February 2026, the Medicare contractors revised 19 different coverage policies under their molecular diagnostics program, covering among other things, the next-generation sequencing for solid tumors and plasma genomic profiling. There are specific requirements of evidences and documentation required in order to get paid, and RNA tests usually require a different kind of validation process. The small laboratories find it difficult due to the costs involved, and sometimes they wait till the coverage policies are established. Hospitals have to compete for scarce funds, and there is a need to train the clinical teams on expression tests results.
Handling of data is another limiting factor. RNA sequencing projects generate huge volumes of terabytes of data which may have to be stored and transferred securely and analyzed through bioinformatics expertise which might not be available at many organizations. Quality of samples, batch effects, and variations in the library methods will decrease the consistency of data. The price of instruments and reagents will still be too expensive for small labs; in addition, due to the funding cycle in academic settings, purchases of new systems might be postponed for some time. Competition from other platforms will put a downward pressure on the prices of the supplier of the instrument.
Opportunity: Clinical Long-Read Approvals and National Genome Programs Open New Demand
Regulators in large markets are beginning to approve clinical long-read systems. In November 2025, China's National Medical Products Administration granted a Class III registration to a clinical-grade long-read sequencing system, which was described as the first such approval in the country. Long-read methods capture full-length transcripts and isoforms, and approvals open a pathway for diagnostic uses in rare disease, cancer, and infectious disease. Instrument makers and assay developers are preparing local partnerships to serve this demand. Reference materials and quality programs for long-read assays are also being developed, which will help laboratories meet accreditation requirements and prepare for regulated use.
National genome programs are generating large datasets that invite transcriptome work. In January 2025, India's Department of Biotechnology made the GenomeIndia dataset of 9,772 genomes publicly available, and a second phase is reported to be under way. Population programs in the United Kingdom, Singapore, and the European Union increasingly pair genomic data with expression profiling, and these projects create demand for large-scale single-cell and spatial methods and for services providers that can process thousands of samples. Biobanks and consortia are also building shared data platforms, and service providers that can combine sequencing, cloud analysis, and secure data transfer are well placed to win large multi-year contracts.
Market Characteristics & Concentration
The NGS-based RNA Sequencing Market is Moderately Consolidated. A small group of platform makers supplies most sequencing instruments and flow cells, while a large number of kit makers, service providers, and software firms serve library preparation, analysis, and storage. Platform installed base, reagent pull-through, ecosystem partnerships, and data quality shape competition. Several suppliers also operate in more than one segment, selling instruments, kits, and software to the same customers, which strengthens customer retention.
Single-cell, spatial, and long-read methods are reshaping the product mix. Instrument makers add benchtop and high-throughput systems at lower prices, sample preparation specialists release kits that scale to millions of cells, and service providers bundle sequencing with analysis pipelines. Consumables generate most recurring revenue, which gives platform owners a long-term income base. Customers increasingly ask for integrated workflows that link sample collection, library preparation, sequencing, and cloud analysis in one contract.
Quality and compliance expectations are rising as RNA assays move into clinical use. Laboratories need validated workflows, reference materials, and traceable data, and suppliers that provide documentation and support for regulated environments gain preference. Research-use-only products still account for a large share of volumes, but clinical-grade offerings are growing. Accreditation bodies and proficiency testing programs also shape purchase choices for hospital laboratories. Suppliers that offer certified reference materials and audit support are preferred by regulated laboratories.
Analyst Perspective
NGS-based RNA sequencing is moving from a research tool to a routine part of drug discovery and clinical testing, driven by single-cell, long-read, and spatial methods and by lower cost per sample. Consumables and sample preparation products generate recurring revenue, while services and analysis software gain share as data volumes grow. Clinical coverage rules and data burdens remain the main limits on faster adoption, and pricing pressure from new entrants is expected to continue. An SNS Insider Analyst, Santosh Bhul, commented, "Suppliers that combine low-cost platforms, scalable single-cell and long-read kits, and clinical-grade analysis will outgrow the market, and Asia Pacific will add the fastest demand through 2035."
Segment Analysis
Technology Insights
Sequencing by synthesis held the largest share of 57.80% in 2025. Short-read platforms based on this method deliver high accuracy and low cost per base, and they underpin most bulk and single-cell RNA studies, as well as clinical panels. A large installed base, wide library of validated protocols, and strong software ecosystem keep researchers and laboratories loyal to the technology. Producers continue to raise throughput and reduce prices, which supports routine use in large studies. New high-throughput systems from several suppliers have also pushed the cost of a transcriptome down, which broadens use in population-scale and drug screening studies.
Nanopore sequencing is expected to expand at the fastest CAGR of 21.38% from 2026 to 2035. The method reads full-length RNA molecules directly, including base modifications, which short-read systems cannot capture. Researchers use it to study isoforms, fusion transcripts, and viral RNA, and manufacturers of messenger RNA therapeutics adopt it for quality control. Portable devices and real-time analysis support field work, while single-molecule real-time sequencing and ion semiconductor systems serve selected clinical and research uses. Improvements in accuracy and yield have narrowed the gap with short-read systems, and developers are releasing kits and software that simplify data analysis for new users.
Product and Service Insights
RNA-seq platforms and consumables held the largest share of 53.40% in 2025. Sequencers, flow cells, and reagents form the recurring base of the market, because each run consumes reagents and each installed system keeps generating revenue. Instrument makers sell benchtop and production-scale systems, and customers choose them for throughput, read length, accuracy, and cost per sample. Large installed bases in academic centers, pharmaceutical firms, and clinical laboratories support steady consumable demand. Suppliers also bundle reagents, software, and support contracts, which raises switching costs and keeps customers within one ecosystem over the life of an instrument.
RNA-seq services are projected to grow at the fastest CAGR of 19.74% from 2026 to 2035. Contract providers offer library preparation, sequencing, and bioinformatics for firms that lack in-house capacity, including biotechnology start-ups and smaller academic groups. Pharmaceutical sponsors outsource large studies to control costs and shorten timelines, and clinical programs need quality management that services firms can provide. Sample preparation products and data analysis and storage add further recurring demand. Turnaround times, data quality guarantees, and integrated reports are the main selection criteria, and several providers have opened new laboratories in Asia and Europe to serve regional clients.
Application Insights
Drug discovery and development had the highest market share at 52.60% in 2025. The RNA sequencing is employed by pharmaceutical and biotech companies for target identification, mechanistic studies, compound screening and profiling, as well as biomarker discovery to inform trial design. Single-cell sequencing is useful for mapping cell types in diseased tissues, and large initiatives sequence thousands of samples in each study. Users purchase equipment, kits, and service in bulk, and repeat studies with growing number of pipelines. Spatial and single-cell sequencing technologies are increasingly paired with bulk RNA sequencing, and sponsors utilize transcriptome data for patient selection and combination drug development.
Clinical diagnostics will see the fastest growth rate at 21.64% in 2026-2035. Clinical laboratories utilize RNA sequencing panels for cancer fusion detection, rare disease transcriptome profiling, and therapeutic expression signatures. Clear regulatory framework for lab-developed tests and coverage from payers help in adoption, and hospitals develop in-house sequencing capacity. Biomarker and translational research, basic and academic research, and other applications contribute additional demand. Adoption in clinical setting is dependent on turn-around-time and reporting, and laboratories invest in automation, standardized workflows, and employee training.
Regional Insights
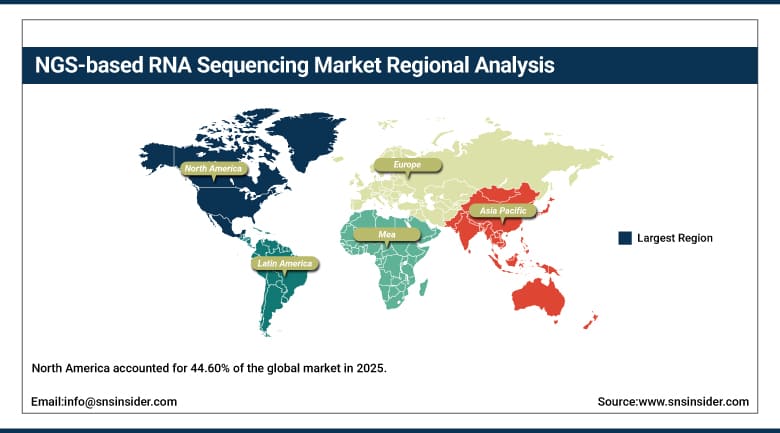
North America accounted for 44.60% of the global market in 2025. The region has large public research funding, a dense pharmaceutical and biotechnology base, major sequencing platform makers, and early adoption of sequencing in clinical care. Academic medical centers and cancer institutes run large transcriptome programs, and contract research organizations offer services at scale. Canada adds demand through genomic research networks and hospital laboratories. Several states and provinces fund core facilities that give smaller institutions access to advanced instruments and analysis support.
Get Customized Report as Per Your Business Requirement - Enquiry Now
U.S. NGS-based RNA Sequencing Market
The U.S. market was valued at USD 1.73 Billion in 2025 and is expected to register a CAGR of 16.48% from 2026 to 2035. Federal research funding, a large base of pharmaceutical and biotechnology firms, and many academic medical centers support steady demand for platforms, kits, and services. In June 2026, the All of Us Research Program released data on more than 747,000 participants, including 535,000 whole genomes, which widens the reference data available to researchers. Spatial and single-cell studies are among the fastest growing project types.
Clinical laboratories are adding RNA-based assays for oncology and immunology, supported by regulatory clarity on laboratory-developed tests and by coverage policies for sequencing in solid tumors. Platform makers, sample preparation specialists, and spatial biology companies are concentrated in California, Massachusetts, and Washington, and many launch new products at the annual genomics conferences. Buyers value throughput, cost per sample, and integrated analysis software. Contract research organizations and core facilities at universities offer capacity to smaller firms, and some laboratories have signed multi-year supply agreements to secure reagents at lower prices as volumes rise.
Europe NGS-based RNA Sequencing Market
Europe accounted for 24.30% of the global market in 2025, with Germany, the United Kingdom, France, Italy, and Spain as the largest country markets. In November 2023, the European 1+ Million Genomes group adopted a roadmap that sets a goal of operational infrastructure in 15 countries by 2026. Academic consortia, national health systems, and pharmaceutical hubs in Switzerland, Germany, and the United Kingdom drive demand, while device rules shape clinical adoption. Cross-border data sharing rules and shared biobanks also support multi-country studies.
Asia Pacific NGS-based RNA Sequencing Market
Asia Pacific accounted for 24.80% of the market in 2025 and is anticipated to register the fastest regional CAGR of 19.06% from 2026 to 2035. China, Japan, India, South Korea, Singapore, and Australia are expanding sequencing capacity through national genome programs, hospital laboratories, and contract research. Local platform makers in China compete on price, and regulatory approvals of clinical systems are opening new diagnostic uses across the region. Rising research budgets and growing pharmaceutical outsourcing add further volume.
Latin America NGS-based RNA Sequencing Market
Latin America accounted for 3.50% of the market in 2025, with Brazil as the leading country market followed by Mexico, Argentina, and Colombia. Public research institutions, cancer centers, and private diagnostic laboratories use RNA sequencing for oncology and infectious disease work, and many buy through distributors or send samples to service providers. Currency swings and import costs affect purchasing, although regional genomic initiatives support future growth. Training programs and regional research networks are expanding the pool of skilled users.
Middle East & Africa NGS-based RNA Sequencing Market
Middle East & Africa accounted for 2.80% of the market in 2025, with Saudi Arabia, the United Arab Emirates, Israel, South Africa, and Egypt as the main country markets. Gulf governments fund national genome programs and precision medicine centers, while South Africa and Egypt host research hubs focused on infectious disease and cancer. Most platforms are imported, and partnerships with global suppliers support training and installation across the region. Investment in hospital laboratories adds further demand.
Key NGS-based RNA Sequencing Market Company Insights
Companies in the NGS-based RNA sequencing market are focusing on single-cell and spatial workflows, long-read and benchtop platforms, scalable sample preparation, and analysis software that shortens time to insight. Platform makers are pairing instruments with reagent portfolios, while kit makers and service providers expand capacity to serve pharmaceutical and clinical customers. Acquisitions and technology partnerships remain central to growth.
Key NGS-based RNA Sequencing Companies:
- Illumina
- Thermo Fisher Scientific
- Pacific Biosciences
- Oxford Nanopore Technologies
- 10x Genomics
- MGI Tech
- QIAGEN
- Agilent Technologies
- Roche
- Bio-Rad Laboratories
- Takara Bio
- Element Biosciences
- Bruker
- Ultima Genomics
Recent Developments
- In September 2026, 10x Genomics began worldwide shipments of its Atera spatial platform, with orders exceeding the 40 units it had planned for 2026.
- In August 2026, Pacific Biosciences appointed Mark Van Oene as chief executive officer and introduced updated chemistry for its Vega system.
- In June 2026, Roche launched AXELIOS 1, a sequencing by expansion system for research use, with RNA sequencing and single-cell RNA applications shown as proof of principle.
- In May 2026, Oxford Nanopore Technologies launched a direct RNA sequencing solution for quality control of messenger RNA manufactured under good manufacturing practice, together with Lonza.
- In March 2026, Ultima Genomics launched its UG200 series and Solaris 2.0 workflows for scalable sequencing.
- In February 2026, Element Biosciences introduced VITARI, a benchtop system that generates up to 10 billion reads per run and ships in the second half of 2026.
- In January 2026, Illumina completed its acquisition of SomaLogic for USD 350.00 Million in cash plus up to USD 75.00 Million in milestone payments.
- In November 2025, QIAGEN announced an agreement to acquire Parse Biosciences for about USD 225.00 Million in cash plus up to USD 55.00 Million in milestone payments.
Scope and Research Methodology
This report defines the NGS-based RNA sequencing market as the revenue generated from sequencing platforms, consumables, sample preparation products, sequencing services, and data analysis and storage solutions used to sequence and profile RNA with next-generation methods. Coverage includes bulk, single-cell, small RNA, and long-read workflows applied in drug discovery, clinical diagnostics, translational research, and academic research. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are stated in USD. Microarray, quantitative PCR, and proteomics-based expression tools are outside the scope. Standalone genotyping arrays, DNA-only sequencing, and sequencing of other nucleic acids are outside the scope.
The research program combines secondary and primary work. Secondary research draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, laboratory directors, procurement managers, and other stakeholders across the value chain. These conversations validate assumptions, adoption rates, and pricing, and they test the direction of demand in each region and application before any figure is finalized for the study. Every interview follows a structured guide so that responses are comparable across respondents and regions, and findings are logged against the assumptions they affect.
Market engineering follows a bottom-up build from instrument installed base, consumable usage per run, and service volumes, cross-checked top-down against research funding, pharmaceutical spending, and clinical testing indicators. Estimates are triangulated across these routes until the results converge within an acceptable range. Forecasts incorporate the drivers that shape demand, including regulation, technology maturity, and macroeconomic conditions. Senior analysts review every estimate, assumption, and narrative section for consistency before release, and figures are checked against the segment and regional totals so that the final model remains internally coherent. Where inputs differ, analysts revisit the underlying assumptions with sector experts and adjust the model only when the evidence supports a change, so that the published figures stay traceable to documented inputs.
NGS-based RNA Sequencing Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.32 Billion |
| Market Size by 2035 | USD 22.46 Billion |
| CAGR | CAGR of 17.92% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product and Service (RNA-Seq Platforms and Consumables, Sample Preparation Products, RNA-Seq Services, and Data Analysis and Storage) • By Technology (Sequencing by Synthesis, Ion Semiconductor Sequencing, Single-Molecule Real-Time Sequencing, and Nanopore Sequencing) • By Application (Drug Discovery and Development, Clinical Diagnostics, Biomarker and Translational Research, Basic and Academic Research, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Illumina, Thermo Fisher Scientific, Pacific Biosciences, Oxford Nanopore Technologies, 10x Genomics, MGI Tech, QIAGEN, Agilent Technologies, Roche, Bio-Rad Laboratories, Takara Bio, Element Biosciences, Bruker, Ultima Genomics |

Frequently Asked Questions
The market was valued at USD 4.32 Billion in 2025 and is projected to reach USD 22.46 Billion by 2035.
The market is expected to register a CAGR of 17.92% from 2026 to 2035.
North America led the market with a 44.60% share in 2025.
Asia Pacific is expected to grow the fastest, at a CAGR of 19.06% from 2026 to 2035.
RNA-seq platforms and consumables led the product and service segment with a 53.40% share in 2025, and drug discovery and development led the application segment.
