
Non-Invasive Fat Reduction Market Report Scope & Overview:
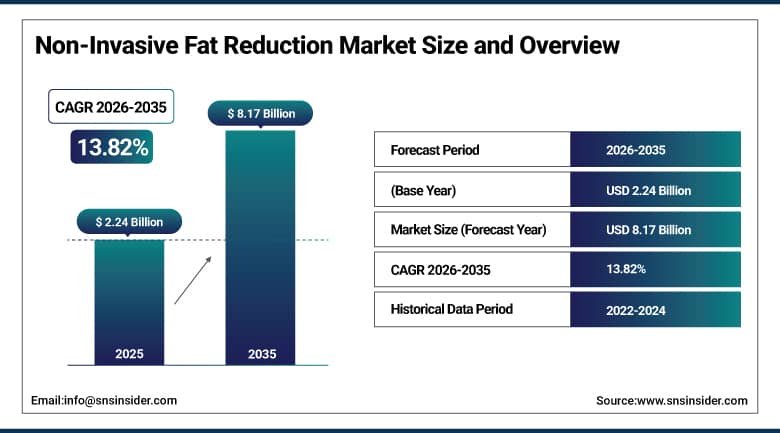
The Non-Invasive Fat Reduction Market was valued at USD 2.24 Billion in 2025 and is expected to reach USD 8.17 Billion by 2035, growing at a CAGR of 13.82% from 2026-2035.
The Non-Invasive Fat Reduction Market is expanding as more people seek body shaping without surgery. Cryolipolysis, radiofrequency, ultrasound and laser devices treat stubborn fat with little downtime. Clinics and medical spas add these systems to attract patients and repeat visits. Social media and rising body image awareness are lifting demand. New devices combine fat reduction with muscle toning and skin tightening. Weight loss drugs and high treatment prices temper growth in some markets. Competition among device makers keeps pricing under pressure. The market is expected to grow as technology improves and treatment is offered to a wider group of patients.
⮞In June 2025, the International Society of Aesthetic Plastic Surgery reported close to 38 million aesthetic procedures worldwide in 2024. The total shows the large base of demand for aesthetic treatments, including non-surgical body contouring.
To Get More Information On Non-Invasive Fat Reduction Market - Request Free Sample Report
Non-Invasive Fat Reduction Market Trends:
-
Growth of combined fat reduction, muscle toning and skin tightening treatments
-
Rising use of radiofrequency and high-intensity electromagnetic technologies
-
Expansion of medical spa chains and subscription-style treatment programs
-
Use of body contouring to address skin laxity and muscle loss in weight loss patients
-
Consolidation and restructuring among aesthetic device makers
U.S. Non-Invasive Fat Reduction Market Outlook:
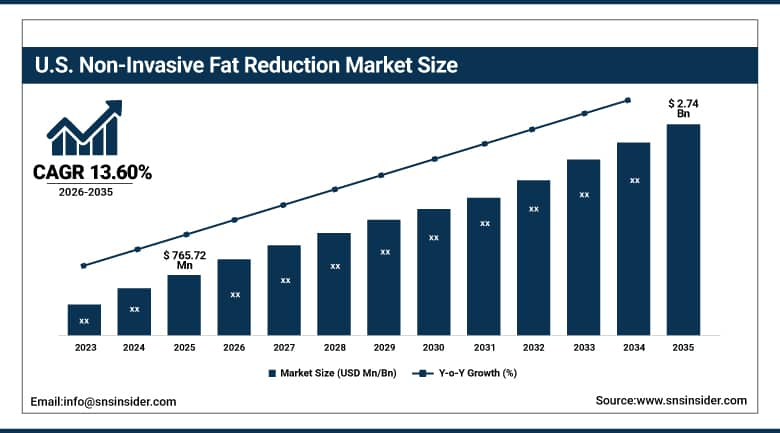
The U.S. Non-Invasive Fat Reduction Market was valued at USD 765.72 Million in 2025 and is expected to reach USD 2.74 Billion by 2035, growing at a CAGR of 13.60% from 2026-2035.
The U.S. Non-Invasive Fat Reduction Market is the largest national market and is driven by high aesthetic spending and a dense network of clinics and medical spas. Providers buy cryolipolysis, radiofrequency and electromagnetic systems to attract cash-paying patients. Treatment is not covered by insurance, so consumer confidence affects demand. The rapid use of weight loss drugs has changed patient interest in some fat reduction treatments. Providers are responding with muscle and skin treatments for those patients. Device makers face price competition and the cost of clinical evidence. FDA clearances shape which claims can be marketed. Demand is expected to recover and grow as new technologies and combined treatments reach more patients.
⮞In July 2025, the American Society of Plastic Surgeons reported 447,581 noninvasive fat reduction procedures in 2024, down from 745,967 in 2023. The change shows how U.S. demand is being reshaped by new weight management options and treatment pricing.
Non-Invasive Fat Reduction Market Segment Analysis:
-
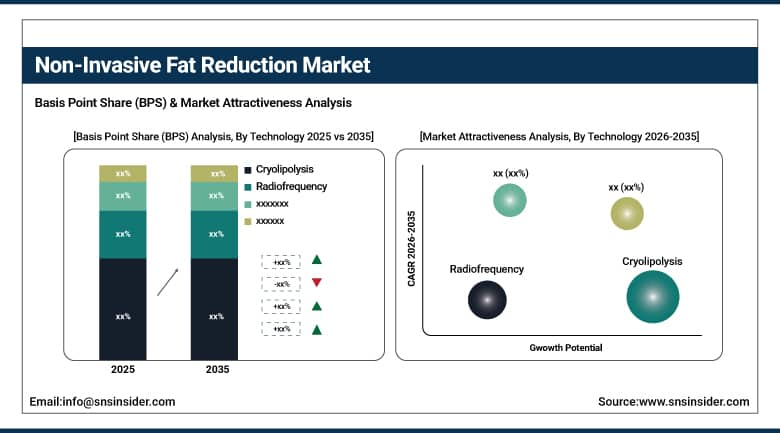
By Technology, the Cryolipolysis segment dominated the Non-Invasive Fat Reduction Market with approximately 38.03% share in 2025, while the Radiofrequency segment is the fastest growing with a CAGR of approximately 15.22%.
-
By Treatment Area, the Abdomen and Flanks segment dominated the Non-Invasive Fat Reduction Market with approximately 48.00% share in 2025, while the Submental segment is the fastest growing with a CAGR of approximately 15.92%.
-
By Product Type, the Capital Equipment segment dominated the Non-Invasive Fat Reduction Market with approximately 66.80% share in 2025, while the Disposables and Applicators segment is the fastest growing with a CAGR of approximately 14.62%.
-
By End User, the Hospitals segment dominated the Non-Invasive Fat Reduction Market with approximately 56.50% share in 2025, while the Medical Spas segment is the fastest growing with a CAGR of approximately 15.68%.
By Technology, Cryolipolysis Dominates the Non-Invasive Fat Reduction Market and Radiofrequency Grows Fastest
Cryolipolysis leads because it was the first widely accepted method for freezing and removing fat cells without surgery. Clinicians have years of experience with the treatment, and patients recognize the brand names and results. Applicators are available for many body areas, and recent models cut session times. Clinical studies support fat layer reduction after repeat treatment. These strengths allow providers to market cryolipolysis confidently and keep it the largest technology despite growing competition from newer heat and energy based platforms. Providers also value its predictable protocols and the availability of training, which lowers the risk of poor outcomes and helps new clinics start treating patients quickly after purchase.
Radiofrequency is growing fastest because it can reduce fat, tighten skin and support muscle toning in one platform. Devices heat tissue in a controlled way, which damages fat cells and stimulates collagen. Patients like the combined benefit and the comfort of treatment. Manufacturers pair radiofrequency with electromagnetic muscle stimulation, vacuum and cooling, which raises the appeal for providers who want multi-purpose equipment. As treatment protocols are refined and costs fall, radiofrequency systems are spreading across clinics, medical spas and hospitals around the world. Hybrid systems that add cooling or vacuum features to radiofrequency are further widening the range of patients who can be treated safely, including those with thicker tissue layers.
⮞In August 2026, InMode reported that non-invasive products accounted for 26% of second quarter revenue, up from 19% a year earlier. The shift shows rising demand for energy-based, non-invasive aesthetic platforms.
By Treatment Area, Abdomen and Flanks Dominates the Non-Invasive Fat Reduction Market and Submental Grows Fastest
The abdomen and flanks lead because they are the most common areas where patients notice stubborn fat that does not respond to diet and exercise. Large applicators treat these zones efficiently, which makes sessions practical for providers. Patients often return for several rounds to improve shape, and many combine abdomen work with other areas. Marketing materials highlight waistline results, and before and after images are widely shared. These factors make abdomen and flank treatments the main revenue source for most clinics. Sessions for this area typically use larger applicators, which allows providers to treat two zones at once and to offer package pricing that raises average revenue per patient.
Submental treatment is growing fastest because fullness under the chin affects appearance in photos and video calls, and patients seek a non-surgical option. Smaller applicators and injectable alternatives have widened choice, and treatment time is short. Younger patients and men are showing interest, which expands the customer base. The area is also well suited to combined protocols with skin tightening. As awareness grows, providers are adding submental packages to their menus, and device makers are launching applicators designed for the neck and jawline. Neck and jawline appearance has gained importance with the use of video calls and selfies, and providers say consultations for this concern now start earlier in a patient's treatment journey.
⮞In September 2026, El.En. reported first half revenue above EUR 246 million, up 9%, with growth driven by its medical sector. The result shows ongoing demand for laser systems used in aesthetic body treatments.
By Product Type, Capital Equipment Dominates the Non-Invasive Fat Reduction Market and Disposables and Applicators Grows Fastest
Capital equipment leads because each provider must first buy or lease a system before treating patients. Devices cost from tens of thousands to hundreds of thousands of dollars, so each sale carries high revenue. New clinics and medical spas keep opening, and existing providers upgrade to newer models with more applicators. Manufacturers offer financing and leasing to ease purchase. Because the installed base is still growing, equipment sales form the largest share of market value, although recurring revenue is gaining importance. Financing partners and leasing companies also support these purchases, which helps independent clinics acquire several devices and expand the range of treatments they offer.
Disposables and applicators represent the fastest-growing segment because companies are moving towards the recurrent revenue model. Disposable tips, cartridges, and treatment cards are purchased for each procedure, thus generating revenue on the installed base utilization. Providers appreciate safety and reliability provided by new disposable components. Subscription and pay-per-use business models additionally tie revenue to the number of treatments provided. With the growth in the number of installed units, the recurring revenue from consumables is projected to grow faster than that of equipment revenue, helping companies provide more stable revenue streams. In addition, software licensing, replacement tips, and warranties contribute to the revenue.
⮞In May 2026, Bausch Health reported that its Solta Medical Thermage system had passed 5 million treatments worldwide and received trademark certification in China. The milestone shows the scale of treatment volumes that support recurring tip sales.
By End User, Hospitals Dominates the Non-Invasive Fat Reduction Market and Medical Spas Grows Fastest
Hospitals lead in published estimates because they provide medically supervised plastic surgery and dermatology services and often hold several high-value systems. Patients trust physician-led care for safety, and hospitals can combine surgical and non-surgical options. Hospital-affiliated aesthetic centers have strong marketing power and access to financing. Reimbursement does not apply, but patient volume is steady. Large institutions can also invest in clinical studies and training, which supports adoption of the newest devices and keeps them at the top of the market. Many hospital-based aesthetic centers also train residents and fellows, which builds familiarity with devices that graduates later choose when they open private practices.
Medical spas are growing fastest because they offer convenient, lower-cost treatment in a retail setting, often with membership plans. Chains are opening new locations and buying multiple devices per site. Younger consumers are comfortable using spas for aesthetics, and extended hours suit working patients. Device makers support spas with training, leasing and marketing tools. Medical director oversight and state rules add some complexity, but the model has strong appeal. As competition grows, spas are expanding menus to include body contouring and muscle toning. Consumer financing, loyalty programs and bundled packages help spas retain patients, and owners increasingly choose devices that deliver quick, low-pain sessions to maximize daily throughput.
⮞In May 2026, a survey at the SCALE Music City meeting found that 327 of 406 aesthetic professionals offered body contouring. The result shows how widely providers have added body shaping services.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
88.36 |
|
Europe |
Germany |
24.18 |
|
Asia Pacific |
China |
33.51 |
|
Latin America |
Brazil |
46.73 |
|
Middle East & Africa |
Saudi Arabia |
29.84 |
North America Non-Invasive Fat Reduction Market Insights
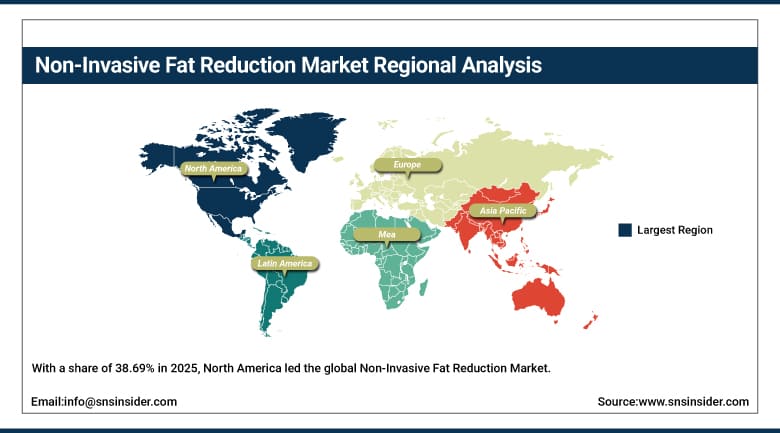
With a share of 38.69% in 2025, North America led the global Non-Invasive Fat Reduction Market. The United States accounts for most regional demand through its high aesthetic spending and wide network of clinics and medical spas. Canada adds demand through private aesthetic practices. AbbVie, InMode, Cutera, BTL, Cynosure Lutronic and Venus Concept compete in the region. Patients pay out of pocket, and providers invest in marketing and financing programs to attract them. Social media strongly influences treatment interest. Large academic centers and private practices also run clinical studies that support new indications, and this research culture helps the region introduce new technologies earlier than most others.
Weight loss medicines have changed how many patients think about fat reduction, and some providers report fewer inquiries for traditional treatments. Companies respond with combination protocols that tone muscle and tighten skin after weight loss. Financial restructuring at some device makers has changed the competitive field. Providers also look for devices that offer faster sessions and less discomfort. Price competition is strong, and manufacturers add service and training to differentiate. Provider groups are consolidating into chains backed by private equity, which increases purchasing scale and gives larger buyers more power to negotiate prices and service terms with device makers.
⮞In August 2026, Sisram Medical reported that its North America revenue in the first half of 2026 was USD 44.40 million, down 21.6%. The decline shows the pressure on equipment sales in the largest regional market.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Non-Invasive Fat Reduction Market Insights
Europe is the second largest region and is led by Germany, the United Kingdom, France, Italy and Spain. Aesthetic clinics and dermatology practices offer a wide range of body contouring treatments, and demand grows steadily among middle-aged consumers. The Medical Device Regulation sets strict requirements for clinical evidence, which supports established brands. Medical tourism in Spain, Turkey and Eastern Europe adds more patients. Consumers weigh safety and clinician credentials closely when they choose a provider. Distribution networks are well developed, and many suppliers offer financing, service and training bundles that help independent practices manage the high up-front cost of equipment.
Competition combines global companies and strong regional manufacturers, including laser and energy device makers in Italy and Germany. Prices are moderate compared with the United States, and clinics often buy devices through distributors. Regulatory restrictions on advertising in some countries affect marketing. Interest in muscle toning and skin tightening is rising, which supports multi-function devices. Providers also invest in training and certification to maintain quality standards, and demand is expected to remain steady across Western and Southern Europe. Interest from men is rising in Germany and the Nordic countries, and clinics are adapting treatment menus and marketing to reach this group, which broadens the potential patient pool.
⮞In August 2026, Sisram Medical reported that its Europe revenue in the first half of 2026 reached USD 26.70 million, up 12.1%. The increase shows healthy demand for aesthetic devices in the region.
Asia Pacific Non-Invasive Fat Reduction Market Insights
Asia Pacific is anticipated to be the leading growing region with a CAGR of 15.84% in 2026-2035. South Korea, China, Japan, India and Australia dominate regional demand. South Korea is an aesthetic hotspot with well-developed domestic device manufacturers and culture that prioritizes beauty. China experiences a fast-growing middle class and numerous new aesthetic clinics. Japan has a mature market concentrated on safe and non-invasive treatments. Income growth and social media drive awareness in the region. Chain clinics in China and South Korea grow fast with a uniform menu of treatments and tend to bargain good prices by purchasing devices in bulk from suppliers.
Competitive devices are offered by local manufacturers at affordable prices and global players enter through partnerships and registration. Approval process differs from country to country, which may result in delays of product launch. Medical tourism in Korea and Thailand drives additional demand for foreign clients. The preference of providers goes to the devices that allow to treat face and body to get the full profit. The issues of counterfeit products and non-qualified operators exist in some markets. Growth is anticipated because of growth of chain clinics and consumer acceptance of non-surgical body contouring.
⮞In August 2026, Classys reported first half 2026 consolidated revenue of KRW 192.7 billion, up 20%. The result shows strong growth among Korean aesthetic device makers.
MEA & Latin America Non-Invasive Fat Reduction Market Insights
In Latin America, the largest market is Brazil followed by Mexico, Argentina and Colombia. One of the countries that have very high rates of procedures done is Brazil and body contouring is a common procedure. Clinics purchase machines from domestic and foreign manufacturers and they use financing to enable their treatments affordable. The cost of devices is affected by economic instability and importation costs. There is a very good culture of beauty and large number of qualified aesthetic practitioners. Manufacturers partner with local distributors to enable them register, train and provide services because of varied regulation requirements.
Saudi Arabia and the United Arab Emirates are the leading consumers of medical devices in the Middle East and Africa region. Very high disposable income, growth in numbers of aesthetic clinics and high number of medical tourists are helping in sales of sophisticated machines. Distributors are very important in entering into the markets and training. The attitudes towards beauty may be different in different cultures but non-surgical treatments are highly acceptable. South Africa has an established aesthetic industry. Since there is very little insurance coverage, demand of devices will depend on the disposable income but young customers are interested in body shaping.
⮞In August 2026, Sisram Medical reported that its Middle East and Africa revenue in the first half of 2026 was USD 16.80 million, up 20.9%. The growth shows rising demand for aesthetic devices in the region.
Market Dynamics:
Growth Drivers: Demand for Non-Surgical Body Shaping and Technology Advances
Demand for non-surgical body shaping is the main driver. Patients want results without anesthesia, incisions or long recovery, and non-invasive treatments allow a return to work on the same day. Obesity and lifestyle factors leave many people with localized fat that is hard to remove through diet. Social media and celebrity endorsement increase awareness, and younger consumers are open to aesthetic care. Clinics benefit from repeat visits and add-on treatments, which makes the service attractive for providers. Longer life expectancy and a focus on appearance also keep people in treatment programs for more years, and providers say many patients return annually for maintenance sessions.
Devices now combine cooling, radiofrequency, electromagnetic stimulation and laser energy to treat fat, muscle and skin in one session. Improved applicators reduce discomfort and treatment time, and software helps tailor protocols. Manufacturers invest in clinical studies to support claims and gain regulatory clearances. Subscription and leasing models lower entry barriers for small clinics. Together these factors widen the provider base and encourage patients to try treatments that were once seen as experimental. Growing investment from aesthetic chains and private equity funds has increased the number of treatment locations, which expands access and keeps demand for new devices strong throughout the forecast period.
⮞In November 2025, an Allergan Aesthetics survey of 400 clinicians presented at the ASDS annual meeting found that GLP-1 patients per provider rose from 95 in 2023 to 225 in 2024. The result shows a growing group of patients seeking aesthetic care after weight loss.
Restraints: Weight Loss Drugs, High Treatment Cost and Variable Results
Weight loss drugs are an emerging restraint. Patients using GLP-1 medicines may lose weight without procedures, which can lower interest in standard fat reduction treatments. Providers report changes in inquiry patterns and shifts toward muscle and skin care. The effect is uneven by region and patient group, but it adds uncertainty for device makers that sold systems on the promise of fat reduction. Companies need to adjust marketing and protocols to the new patient mix. Economic downturns can quickly reduce discretionary spending on aesthetic care, and clinics may postpone equipment purchases when consumer confidence weakens or interest rates rise.
High cost and variable results add further pressure. Non-invasive treatments require several sessions and are rarely covered by insurance, which limits access for lower-income patients. Results vary by patient and technology, and some people expect outcomes similar to surgery. Rare adverse events such as paradoxical adipose hyperplasia have drawn legal and media attention. Equipment prices are high, and competition among manufacturers forces discounts. Regulatory requirements for claims also raise cost, especially for smaller companies. Competition from lower cost imitation devices and unregulated home-use gadgets also threatens established brands, and it can undermine patient trust in the category if safety problems occur.
⮞In July 2025, the American Med Spa Association reported that demand for noninvasive fat reduction dropped 40% in 2024 and cited GLP-1 programs as a factor. The report shows the effect of new weight management options on treatment volumes.
Opportunities: Muscle Toning After Weight Loss and Emerging Markets
Muscle toning and skin tightening after weight loss offer a major opportunity. Patients using weight loss drugs often experience muscle loss and skin laxity, which creates demand for treatments that rebuild tone and firm tissue. Device makers are developing platforms that combine electromagnetic muscle stimulation with radiofrequency. Providers can build programs that support patients through weight loss and body contouring. Clinical studies on these combinations are expanding, and early surveys show strong interest among aesthetic professionals. Subscription programs and combined packages that mix muscle, fat and skin treatments can raise lifetime patient value and give providers a reason to maintain close follow-up care.
Emerging markets are a second opportunity. Rising incomes, growing clinic networks and medical tourism in Asia, Latin America and the Middle East expand the customer base. Men are another underserved group, and interest in body shaping among male patients is increasing. Home-use and lower-cost devices may also reach new users, although efficacy standards remain important. Companies that offer training, financing and clinical evidence in local markets can build durable positions as awareness spreads. Male patients and older adults remain under-penetrated groups, and tailored marketing, simple protocols and comfortable devices could unlock sizeable additional demand over the next decade.
⮞In September 2026, the American Med Spa Association reported that 82% of surgeons in the ASPS 2025 statistics reported GLP-1-related consultations. The result shows a large group of patients entering aesthetic practices for post-weight-loss care.
Recent Developments:
-
In March 2026, Allergan Aesthetics announced the fourth annual CoolMonth for CoolSculpting, running from April 1 to April 30, 2026. The program supports provider marketing and shows continued commercial focus on cryolipolysis.
-
In May 2025, Cutera emerged from Chapter 11 as a private company after cutting debt by nearly USD 400 million. The company secured USD 65 million of new financing, which restores balance sheet strength for an aesthetic device maker.
-
In January 2026, Venus Concept announced its intent to voluntarily delist from Nasdaq and deregister with the U.S. Securities and Exchange Commission. The move reflects financial pressure on smaller aesthetic device makers.
-
In September 2026, BTL Industries established a new laser division and introduced the EXOLASE ONE system. The company, known for EMSCULPT NEO, operates in more than 90 countries and widens its aesthetic energy platform portfolio.
Non-Invasive Fat Reduction Market Key Players:
-
AbbVie Inc. (Allergan Aesthetics)
-
InMode Ltd.
-
Cutera, Inc.
-
Cynosure Lutronic
-
BTL Industries
-
Sisram Medical Ltd. (Alma)
-
Venus Concept Inc.
Non-Invasive Fat Reduction Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.24 Billion |
| Market Size by 2035 | USD 8.17 Billion |
| CAGR | CAGR of 13.82% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Cryolipolysis, Radiofrequency, Ultrasound, Laser and Low-Level Light, and Other Technologies) • By Treatment Area (Abdomen and Flanks, Thighs and Hips, Submental, Arms and Back, and Other Areas) • By Product Type (Capital Equipment and Disposables and Applicators) • By End User (Hospitals, Dermatology and Aesthetic Clinics, Medical Spas, and Other End Users) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | AbbVie Inc. (Allergan Aesthetics), InMode Ltd., Cutera, Inc., Cynosure Lutronic, BTL Industries, Sisram Medical Ltd. (Alma), Venus Concept Inc. |

Frequently Asked Questions
Key players include AbbVie (Allergan Aesthetics), InMode, Cutera, Cynosure Lutronic, BTL Industries, Sisram Medical (Alma) and Venus Concept.
Key opportunities include muscle toning and skin tightening for weight loss patients, combination platforms, demand from male patients and growth in emerging markets.
Rising demand for non-surgical body shaping, supported by technology advances and social media awareness, is the main growth factor.
By Technology, the Cryolipolysis segment dominated the market in 2025 with an estimated 38.03% share, supported by long clinical experience and broad provider adoption.
North America dominated the market with a share of 38.69% in 2025, driven by high aesthetic spending and a dense network of clinics and medical spas.
