
Behavioral Health Software Market Report Scope & Overview:
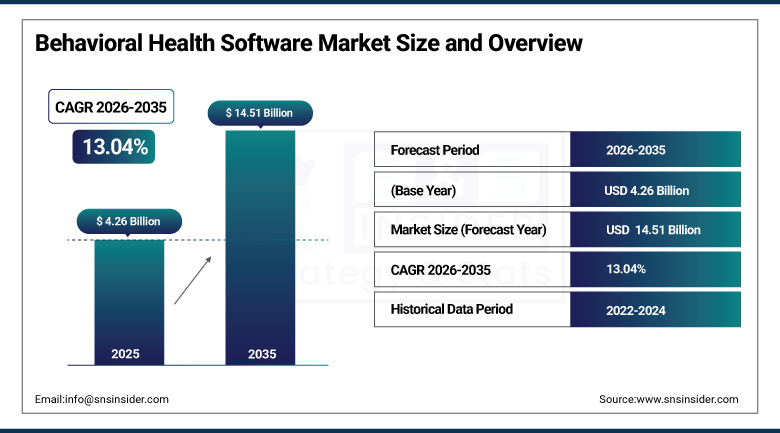
The Behavioral Health Software Market was valued at USD 4.26 Billion in 2025 and is expected to reach USD 14.51 Billion by 2035, growing at a CAGR of 13.04% from 2026-2035.
Behavioral health software encompasses electronic health record, billing, and clinical documentation platforms purpose-built for mental health, substance use disorder, and related human services organisations, addressing workflow and reimbursement requirements. These platforms manage therapy note documentation and treatment planning through medication-assisted treatment dosing records, group therapy scheduling, and the specialised confidentiality protections federal substance use treatment records require. Growth is supported by a surge in mental illness worldwide, expanding telehealth and virtual behavioural care adoption, and continued regulatory support, including federal investment in behavioural health interoperability standards, that continues to push generic-EHR-reliant providers toward purpose-built digital platforms. Artificial intelligence is beginning to reshape the category, as vendors embed generative and agentic AI capability into clinical documentation, scheduling, and workflow automation tools.
In April 2025, Qualifacts unveiled its Qualifacts iQ Agent and Qualifacts iQ Assistant artificial intelligence solutions at the National Council for Mental Wellbeing's NatCon25 conference, with the company continuing to expand its Qualifacts iQ AI suite in 2026, including a purpose-built AI scheduling agent, earning what the company describes as the first ISO 42001:2023 artificial intelligence governance certification in the behavioral health EHR market.
To Get more information On Behavioral Health Software Market - Request Free Sample Report
Behavioral Health Software Market Trends
- Rising deployment of purpose-built AI agents automating clinical documentation and appointment scheduling tasks.
- Growing federal investment in behavioral health interoperability standards supporting data exchange between providers.
- Expanding telehealth and virtual behavioural care adoption reshaping platform functionality requirements.
- Increasing acquisition activity as established vendors add medication-assisted treatment dosing capability.
- Rising demand for AI governance certification as providers scrutinise vendor artificial intelligence practices.
- Growing integration between behavioral health platforms and general medical electronic health record systems.
U.S. Behavioral Health Software Market Overview
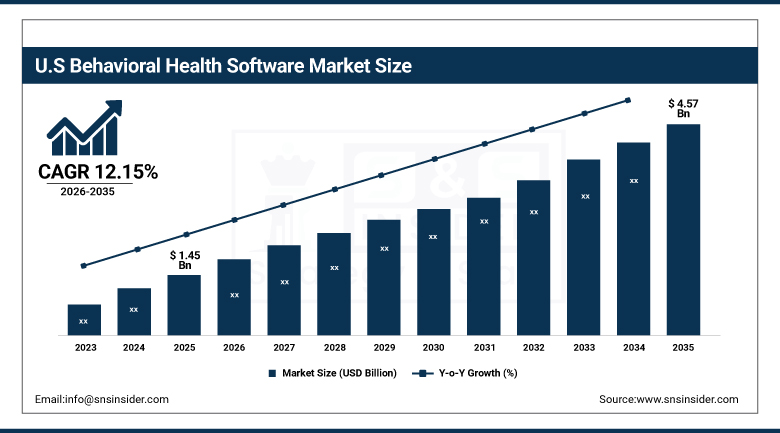
The U.S. Behavioral Health Software Market was valued at USD 1.45 Billion in 2025 and is expected to reach USD 4.57 Billion by 2035, growing at a CAGR of 12.15% from 2026-2035.
The U.S. Behavioral Health Software Market benefits from still-growing population seeking mental health and substance use treatment, sustained workforce shortages that continue to push providers toward automation-enabled platforms, and the presence of leading behavioral health technology vendors headquartered in the country that continue to compete intensely on artificial intelligence capability and interoperability. Federal agencies continue advancing nationwide pilot programs testing behavioral health-specific data exchange standards, reflecting sustained policy attention to the historically fragmented, poorly interoperable state of behavioral health information systems relative to general medical care. Leading vendors continue expanding beyond core electronic health record functionality into adjacent areas including medication-assisted treatment dosing and mobile clinical documentation, broadening the addressable market beyond traditional outpatient and community mental health settings.
In June 2026, U.S.-based SimplePractice launched Care Aide, an AI-powered clinical workflow assistant designed for independent mental-health practitioners. Developed with input from more than 1,000 mental-health professionals, the solution supports session preparation, clinical documentation, treatment planning, intake review, and client summaries. Care Aide builds on SimplePractice’s HIPAA-compliant Note Taker and is designed to reduce administrative workload while supporting clinicians’ existing workflows. The launch strengthens SimplePractice’s behavioral-health software offering for the U.S. independent-practice market and reflects growing adoption of AI-assisted clinical documentation.
Behavioral Health Software Market Segment Analysis
- By Component, the Software segment dominated the market with a 54.20% share in 2025, while the Software segment is the fastest growing with a CAGR of 13.85% during 2026-2035.
- By Functionality, the Clinical Functionality segment dominated the market with a 48.65% share in 2025, while the Financial Functionality segment is the fastest growing with a CAGR of 13.60% during 2026-2035.
- By Delivery Model, the Subscription-Based segment dominated the market with a 55.80% share in 2025, while the Subscription-Based segment is the fastest growing with a CAGR of 14.20% during 2026-2035.
- By Deployment, the On-Premise segment dominated the market with a 52.35% share in 2025, while the Cloud-Based segment is the fastest growing with a CAGR of 15.40% during 2026-2035.
- By End-User, the Outpatient Treatment Centers segment dominated the market with a 38.75% share in 2025, while the Telehealth Providers segment is the fastest growing with a CAGR of 16.25% during 2026-2035.
By Component, Software Dominates the Market and Software Grows Fastest
Software dominated the market in 2025. Core electronic health record, scheduling, and billing platforms continue to represent the foundational purchase for every behavioral health organisation building or upgrading its clinical and administrative technology stack, and this fundamental requirement continues to anchor software as the largest component category across the broader behavioral health software market.
Software is also expected to grow fastest over the forecast period, as continued AI-powered feature expansion within core platforms, including documentation assistants and scheduling agents, continues to reinforce software's already dominant position even further relative to standalone implementation and support services, reflecting how much of the industry's innovation investment is now concentrated within the software layer itself rather than surrounding professional services.
By Functionality, Clinical Functionality Dominates the Market and Financial Functionality Grows Fastest
Clinical functionality dominated the market in 2025. Treatment planning, progress notes, and care coordination tools continue to represent the core, clinically essential capability every behavioral health organisation requires regardless of size or setting, and this fundamental clinical necessity continues to anchor clinical functionality as the largest category across the broader functionality mix.
Financial functionality is projected to be the fastest-growing category over the forecast period, as billing, claims management, and revenue cycle tools continue to gain importance amid tightening reimbursement scrutiny and rising administrative complexity across behavioral health organisations navigating an increasingly complicated payer landscape, positioning financial functionality for sustained above-market growth relative to the broader clinical-dominated functionality mix.
By Delivery Model, Subscription-Based Dominates the Market and Subscription-Based Grows Fastest
Subscription-based delivery dominated the market in 2025. Recurring, cloud-hosted licensing continues to represent the default commercial model across modern behavioral health platforms, reflecting the broader software-as-a-service shift that has reshaped healthcare technology purchasing more generally, and this established model continues to anchor subscription-based delivery as the largest category across the broader delivery model mix.
Subscription-based delivery is also expected to grow fastest over the forecast period, as continued migration away from legacy perpetual license arrangements continues to reinforce this model's already dominant position even further, particularly among smaller behavioral health organisations that increasingly prefer predictable operating expense over large upfront capital software purchases.
By Deployment, On-Premise Dominates the Market and Cloud-Based Grows Fastest
On-premise deployment dominated the market in 2025. A substantial installed base of behavioral health organisations, particularly larger, more established community mental health centres and hospital-affiliated programs, continues to operate locally hosted systems reflecting historical data security preferences and existing capital infrastructure investment made before cloud-based alternatives became widely trusted for clinical use.
Cloud-based deployment is projected to be the fastest-growing deployment category over the forecast period, as rising comfort with cloud-hosted clinical systems, combined with the scalability and faster implementation timelines cloud platforms offer relative to on-premise infrastructure, continues to accelerate adoption, particularly among organisations deploying platforms across multiple facilities without extensive local server investment.
By End-User, Outpatient Treatment Centers Dominates the Market and Telehealth Providers Grows Fastest
Outpatient treatment centers dominated the market in 2025. The sheer volume of behavioral health care delivered through outpatient settings, spanning individual and group therapy, medication management, and intensive outpatient programs, continues to anchor this end-user category as the largest source of behavioral health software demand across the broader market.
Telehealth providers are projected to be the fastest-growing end-user category over the forecast period, as expansion of telehealth and virtual behavioural healthcare continues to create genuinely new demand for platforms purpose-built to support remote clinical documentation, virtual scheduling, and video-integrated therapy delivery, positioning telehealth providers for sustained above-market growth relative to the broader outpatient-dominated end-user mix.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
83.45% |
|
Europe |
Germany |
24.75% |
|
Asia Pacific |
China |
35.60% |
|
Latin America |
Brazil |
21.35% |
|
Middle East & Africa |
United Arab Emirates |
17.85% |
North America Behavioral Health Software Market Insights
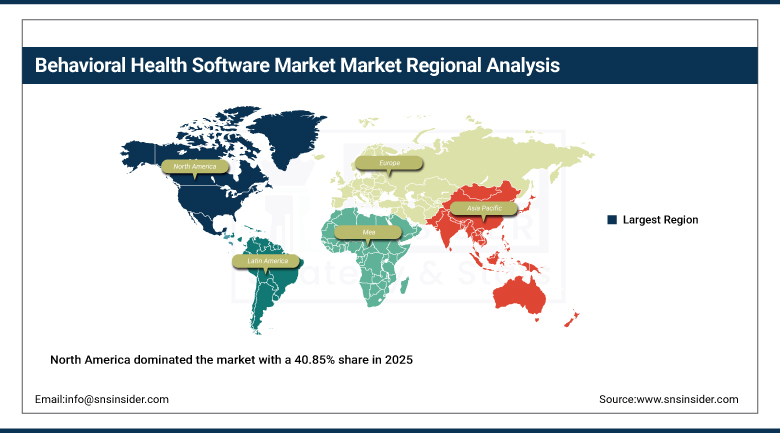
North America dominated the market with a 40.85% share in 2025. Widespread emerging digital health technology adoption, a substantial and still-growing population seeking mental health and substance use treatment, and the concentration of leading behavioral health technology vendors headquartered within the region continue to anchor this leadership position across every major component and deployment category.
Canada contributes meaningful incremental regional demand through its own publicly funded healthcare system, which continues to extend coverage for behavioral health technology adoption. Continued federal policy attention to behavioral health interoperability, combined with sustained vendor AI investment, is expected to keep North America in the lead through the forecast period, even as its growth rate trails the faster-scaling markets developing across Asia Pacific.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Behavioral Health Software Market Insights
Asia Pacific is projected to be the fastest-growing region over the forecast period, registering a CAGR of approximately 15.60%. Rapidly expanding healthcare digitisation investment, growing mental health awareness across major regional economies, and increasing government attention to behavioral health infrastructure continue to accelerate regional adoption of purpose-built behavioral health software.
China anchors regional demand through its expanding healthcare digitisation program and growing private mental health service sector. Japan and South Korea contribute additional regional depth through established healthcare technology adoption, while India's rapidly expanding private healthcare sector and growing mental health awareness continue to add meaningful incremental regional growth.
Europe Behavioral Health Software Market Insights
Europe holds a significant share of the global market, anchored by Germany's substantial healthcare sector and the region's growing public and private investment in mental health service capacity. The region's mature healthcare infrastructure continues to sustain steady demand across every major behavioral health software category.
The United Kingdom, France, and Italy add consistent regional demand as national health systems continue extending behavioral health technology adoption to address rising mental health service demand. Continued regional investment in digital health infrastructure is expected to sustain steady growth across the broader European market through the forecast period.
MEA and Latin America Behavioral Health Software Market Insights
The Middle East and Africa region is supported by growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia, where regional governments continue expanding mental health service capacity as part of broader healthcare modernisation strategies.
Latin America is anchored by Brazil, where a growing domestic healthcare sector and rising mental health awareness continue to sustain steady demand for behavioral health software. Mexico contributes further incremental growth as regional mental health service access continues to widen gradually.
Market Dynamics
Growth Drivers: Rising Mental Illness Prevalence and Telehealth Expansion
A surge in mental illness prevalence worldwide stands as the primary growth driver, as growing recognition of behavioral health needs continues to expand the population seeking treatment across outpatient, inpatient, and community-based settings. This rising demand for care continues to translate directly into rising demand for the technology platforms that support behavioral health service delivery and documentation.
Expansion of telehealth and virtual behavioural healthcare represents a second major driver, as continued growth in remote care delivery continues to require platforms purpose-built to support virtual scheduling, video-integrated documentation, and remote clinical workflow. Continued regulatory support, including federal investment in behavioral health interoperability standards, further reinforces sustained market demand across the broader industry.
Restraints: Workforce Shortages and Fragmented Legacy Systems
Persistent behavioral health workforce shortages remain a genuine restraint, as many organisations struggle to find sufficient clinical and administrative staff to fully implement and optimise new software platforms, even when the underlying technology itself offers genuine efficiency gains, slowing realised return on technology investment.
Fragmented legacy systems present a further restraint, as many behavioral health organisations continue to operate ageing, poorly interoperable systems that complicate data exchange with broader healthcare networks, adding cost and complexity to modernisation efforts and slowing the pace at which organisations can fully adopt newer, more capable platforms.
Opportunities: AI-Powered Automation and Interoperability Development
Continued development of AI-powered clinical documentation and scheduling automation represents a substantial opportunity, as vendors that can deliver genuinely time-saving, clinically reliable AI capability stand to capture demand from organisations facing persistent workforce shortages and administrative burden.
Continued development of behavioral health-specific interoperability standards offers a further avenue for growth, as vendors that can deliver reliable data exchange with broader healthcare networks are positioned to capture demand from organisations increasingly expected to participate in coordinated, whole-person care models that require seamless information sharing across providers.
Recent Developments:
- 2026: Netsmart expanded its collaboration with Pyramid Healthcare to modernize behavioral-health EHR capabilities, AI-enabled clinical workflows, and care coordination across Pyramid’s multistate behavioral-health and addiction-treatment network.
- 2026: athenahealth received five 2026 Best in KLAS awards, including a newly introduced Ambulatory Behavioral Health category, recognizing its healthcare software and behavioral-health capabilities.
- 2026: Oracle Health continued advancing AI-enabled clinical workflows across its healthcare platform; no sufficiently specific 2026 behavioral-health software launch was identified for a standalone development.
Behavioral Health Software Market Key Players are:
- Netsmart Technologies, Inc.
- Qualifacts Systems, Inc.
- Core Solutions, Inc.
- Streamline Healthcare Solutions, LLC
- Epic Systems Corporation
- Oracle Health
- SimplePractice, Inc.
- Valant Medical Solutions, Inc.
- ICANotes, LLC
- Meditab Software, Inc.
- athenahealth, Inc.
- Therapy Brands (TheraNest)
- Alleva
- DrChrono (EverHealth)
- WelbyHealth
- Central Data Storage
- Remarkable Health
- Sunwave Health
- CredibleMind
- Kipu Systems (Netsmart)
Behavioral Health Software Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.26 Billion |
| Market Size by 2035 | USD 14.51 Billion |
| CAGR | CAGR of 13.04% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software, Services) • By Functionality (Clinical Functionality, Financial Functionality, Administrative & Operational Functionality, Reporting & Analytics, Others) • By Delivery Model (Subscription-Based, Perpetual License) • By Deployment (On-Premise, Cloud-Based) • By End-User (Outpatient Treatment Centers, Inpatient and Residential Facilities, Community Mental Health Centers, Hospitals & Health Systems , Telehealth Providers, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Netsmart Technologies, Inc., Qualifacts Systems, Inc., Core Solutions, Inc., Streamline Healthcare Solutions, LLC, Epic Systems Corporation, Oracle Health, SimplePractice, Inc., Valant Medical Solutions, Inc., ICANotes, LLC, Meditab Software, Inc., athenahealth, Inc., Therapy Brands (TheraNest), Alleva, DrChrono (EverHealth), WelbyHealth, Central Data Storage, Remarkable Health, Sunwave Health, CredibleMind, Kipu Systems (Netsmart) |

Frequently Asked Questions
Key players include Netsmart Technologies, Inc., Qualifacts Systems, Inc., Core Solutions, Inc., Streamline Healthcare Solutions, LLC, and Epic Systems Corporation, among other healthcare technology vendors.
Continued development of AI-powered clinical documentation and scheduling automation and continued development of behavioral health-specific interoperability standards represent the primary opportunities.
Growth is primarily driven by a surge in mental illness prevalence worldwide, combined with expansion of telehealth and virtual behavioural healthcare.
By Component, Software dominated the market in 2025, reflecting its role as the foundational purchase for behavioral health clinical and administrative technology.
North America dominated the market with a 40.85% share in 2025, supported by widespread emerging digital health technology adoption.
