
Oil and Gas Accumulators Market Report Scope & Overview:
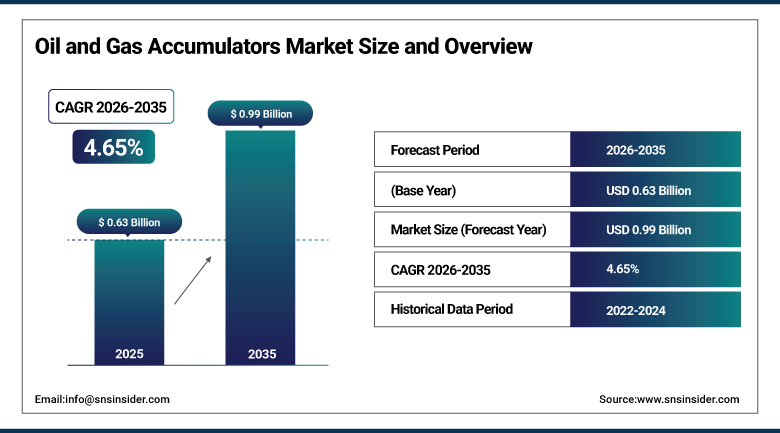
The Oil and Gas Accumulators Market was valued at USD 0.63 Billion in 2025 and is expected to reach USD 0.99 Billion by 2035, growing at a CAGR of 4.65% from 2026-2035.
The Oil and Gas Accumulators Market is growing largely due to the rise in exploration and production activities across the globe, as oil and gas players continue making greenfield and brownfield final investment decisions, which ultimately result in demand for essential hydraulic parts. Accumulators, which serve as hydraulic energy stores in the form of stored pressure fluid, are still a crucial component in blowout preventer systems and well control systems and are an integral part of hydraulic systems in drilling, offshore platforms, and production units where any malfunction can result in catastrophic consequences. This trend is fueled by the implementation of stricter safety regulations on well control systems, along with higher crude oil prices, which continue to encourage exploration and drilling activities.
The growing use of digital monitoring technology and Internet of Things predictive maintenance is contributing to the expansion of functionality of accumulators beyond their primary function of storing pressure, thus ensuring further growth of the market in the future.
In 2024, Olaer Group entered into a partnership with Saudi Aramco to establish local manufacturing of hydraulic accumulators in Saudi Arabia, supporting the kingdom's energy sector localization initiatives under its broader economic diversification program.
To Get more information Oil and Gas Accumulators Market - Request Free Sample Report
Oil and Gas Accumulators Market Trends
- Growing adoption of digital hydraulic accumulators integrating IoT technology for real-time monitoring.
- Rising regional localization of accumulator manufacturing to shorten supply chains and reduce tariff exposure.
- Continued consolidation as operators issue frame agreements bundling accumulators with pumps and valves.
- Increasing deployment of corrosion-resistant accumulator designs supporting carbon capture and storage projects.
- Expanding use of predictive maintenance capabilities to improve operational uptime and safety across rig fleets.
U.S. Oil and Gas Accumulators Market Outlook
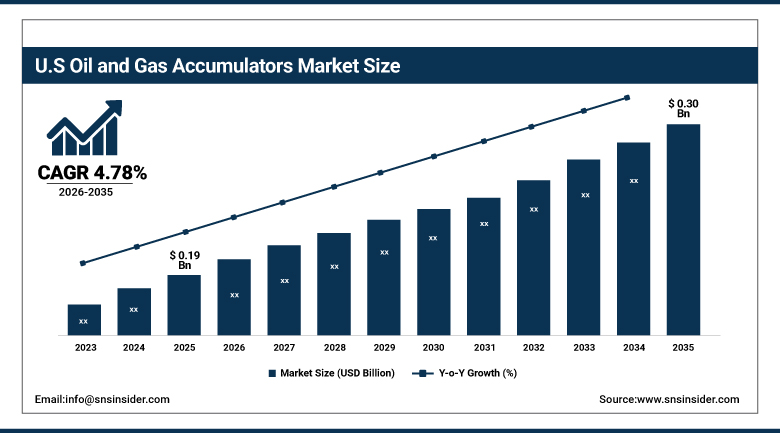
The U.S. Oil and Gas Accumulators Market was valued at USD 0.19 Billion in 2025 and is expected to reach USD 0.30 Billion by 2035, growing at a CAGR of 4.78% from 2026-2035.
The U.S. Oil and Gas Accumulators Market is expected to continue seeing growth due to increased drilling activities, investment in offshore Gulf of Mexico production facilities, and abundance of leading hydraulic component producers in the nation. Furthermore, the demand from domestic buyers is also driven by the localization of accumulators production that will enable better servicing of drilling and extraction facilities in North America without relying on long international logistics chain. Emphasis on the safety of well-control is another aspect that drives the demand for reliable and high-quality accumulators.
In 2024, Bosch Rexroth inaugurated a new manufacturing facility in Houston, Texas, to meet rising demand for oil accumulators in North American drilling and extraction operations.
Oil and Gas Accumulators Market Segment Analysis
- By Type, the Bladder Accumulators segment dominated the Oil and Gas Accumulators Market with approximately 42.50% share in 2025, while the Piston Accumulators segment is the fastest growing with a CAGR of approximately 6.20%.
- By Application, the Blowout Preventer & Well Control segment dominated the Oil and Gas Accumulators Market with approximately 34.50% share in 2025, while the Energy Storage segment is the fastest growing with a CAGR of approximately 6.80%.
- By Deployment, the Onshore segment dominated the Oil and Gas Accumulators Market with approximately 70.3% share in 2025, while the Offshore segment is expected to be the fastest growing, registering a CAGR of approximately 7.20% during the forecast period.
By Type, Bladder Accumulators dominates and Piston Accumulators grows fastest
Bladder Accumulators are the leading type segment in the Oil and Gas Accumulators market, owing to the substantial share of the type segment due to the high degree of reliability, ease of maintenance, and versatility with respect to the pressure range available for well control and hydraulic system applications. The type segment enjoys an existing production capability and extensive field experience that further enables it to maintain the status of being specified as the standard accumulator type across various conventional oil and gas hydraulic applications.
Piston Accumulators are the fastest growing type segment, supported by their higher performance capability in high-pressure and high-volume application scenarios where the limitations of the bladder type become apparent in terms of flow rate and pressure difference management. The type segment comprises of highly engineered designs capable of operating under difficult conditions pertaining to deepwater and high-pressure, high-temperature drilling operations.
By Application, Blowout Preventer & Well Control dominates and Energy Storage grows fastest
The Blowout Preventer & Well Control application segment constitutes the largest application segment of the Oil and Gas Accumulators Market, due to the fact that the accumulators play a mission-critical role in delivering instant hydraulic power for critical well control activities when time is of the essence in ensuring safe operation. This application segment will also benefit from the regulatory requirement for high reliability in the blowout preventer system, which demands an adequate accumulator to actuate critical safety functions even in the event of a power failure.
On the other hand, Energy Storage represents the fastest growing application segment of the Oil and Gas Accumulators Market, driven by rising interests on the part of the operators to reduce energy consumption in hydraulic systems and increase operational efficiencies.
By Deployment, Onshore dominates and Offshore grows fastest
Onshore deployment remains the dominant segment within the Oil and Gas Accumulators Market, supported by the large installed base of onshore drilling, production, well-servicing, and hydraulic control systems worldwide. Accumulators are extensively used in onshore operations for blowout preventer actuation, pressure management, and emergency hydraulic power. The comparatively broader deployment of onshore oil and gas infrastructure and continued development of mature producing fields support the segment’s leading market position.
Offshore deployment is emerging as the fastest-growing segment, driven by continued investment in offshore exploration and production, deepwater and ultra-deepwater developments, and increasingly sophisticated subsea well-control systems. Offshore operations require highly reliable hydraulic pressure-storage solutions because of demanding operating conditions and the need for rapid emergency response. Growing deployment of advanced offshore drilling and subsea equipment is therefore supporting increasing demand for high-performance accumulators.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.50% |
|
Asia Pacific |
China |
42.60% |
|
Europe |
Norway |
28.90% |
|
Latin America |
Brazil |
46.80% |
|
Middle East & Africa |
Saudi Arabia |
52.60% |
North America Oil and Gas Accumulators Market Insights
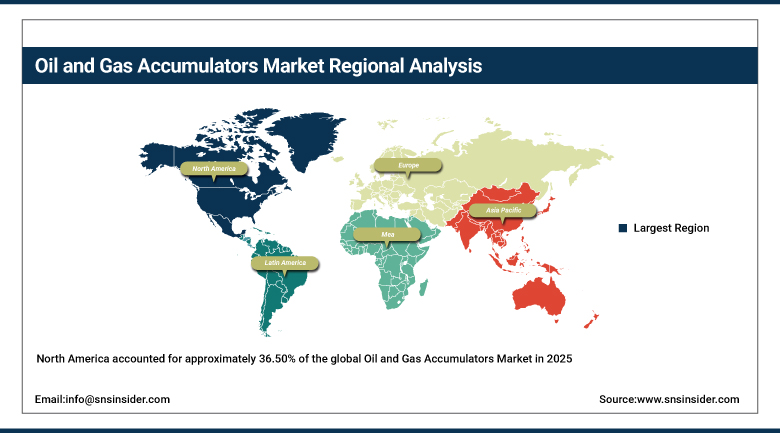
North America accounted for approximately 36.50% of the global Oil and Gas Accumulators Market in 2025, reflecting the region's position as a powerhouse of drilling and completion activity across both conventional and unconventional resource plays. The United States accounts for the substantial majority of regional demand, supported by sustained onshore shale drilling activity and continued offshore Gulf of Mexico production investment.
Canada contributes additional regional demand through its established oil sands and conventional drilling operations. Continued localization of accumulator manufacturing capacity within the region, combined with sustained final investment decisions on new drilling projects, further reinforces North America's position as the largest regional market for oil and gas accumulators.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Oil and Gas Accumulators Market Insights
Asia Pacific will show an expected CAGR of around 6.40% over the forecasted period from 2026 to 2035 owing to high upstream investments in China and Indonesia which have been acting as key factors driving new orders for accumulator equipment.
China is the largest contributor to the regional segment, fueled by increasing domestic exploration activities in oil & gas sector. Other contributors to the growth of the regional segment include India and Southeast Asia which owe to rising energy requirements and investments in upstream activities domestically. Increasing number of brownfield life extension projects requiring medium pressure accumulator units in the wider Asia Pacific region is driving the fastest growth globally for the Oil and Gas Accumulator Market.
Europe Oil and Gas Accumulators Market Insights
Europe represents a meaningful regional market for oil and gas accumulators, anchored by Norway's substantial North Sea offshore production infrastructure and its concentration of established offshore drilling and production operators. Norway's share within the European market reflects both its offshore production scale and its role as a hub for advanced hydraulic system technology serving demanding offshore operating conditions.
The United Kingdom and the Netherlands contribute additional regional demand, supported by established North Sea production infrastructure. The growing number of carbon capture and storage pilot projects across the North Sea further introduces novel accumulator applications in CO2 injection systems, supporting demand for corrosion-resistant accumulator designs across the region.
MEA & Latin America Oil and Gas Accumulators Market Insights
The Middle East & Africa region continues to grow in strategic importance, with demand concentrated in Saudi Arabia, where mega-projects under the kingdom's Vision 2030 economic diversification program, along with ongoing exploration and enhanced oil recovery initiatives, ensure a steady pipeline of accumulator procurement opportunities. Gulf Cooperation Council markets more broadly continue reinforcing the region's position as a global hub for energy infrastructure investment.
Latin America's Oil and Gas Accumulators Market is led by Brazil, which accounts for the majority of regional demand on the strength of its substantial offshore pre-salt production infrastructure and continued deepwater drilling investment. Rising domestic exploration and production activity continues to support steady regional demand growth for high-pressure accumulator equipment suited to deepwater operating conditions.
Market Dynamics
Growth Drivers: Rising Exploration Activity and Safety Regulation
The increase in exploration and production activities throughout the world forms the key growth driver for the Oil and Gas Accumulators Market, since oil and gas producers continuously approve greenfield and brownfield investments which directly lead to the need of using critical hydraulic equipment such as accumulators. This trend is strengthened by the continuous implementation of stricter safety and regulatory requirements for well control systems that require reliable capacity of accumulators for the purpose of well blowout preventer and well control emergencies.
Higher crude oil prices and the rise in the demand for more efficient hydraulic systems forms another key source of demand as operators are looking to enhance their safety performance and efficiency. The increasing use of new technologies such as artificial intelligence and data analytics also contributes to the growth of the market.
Restraints: Commodity Price Volatility and Capital Spending Cyclicality
The intrinsic nature of commodity price volatility in the oil and gas business presents a considerable constraint for the market of Oil and Gas Accumulators since investments into drilling and producing facilities become significantly reduced when low prices persist for crude oil and natural gas. This phenomenon results in considerable cyclicality of accumulators demand, which is linked to wider upstream cycles, which are not within the control of manufactures.
Increasingly sophisticated engineering and material solutions, needed for accumulators operation in the conditions of high pressure and high temperature typical for deepwater and unconventional drilling operations, makes accumulator design increasingly complicated and expensive compared to traditional onshore applications. The volatility of prices of materials is another factor of concern for long-term planning of production costs and pricing.
Opportunities: Digital Monitoring Integration and Carbon Capture Applications
Continued integration of Internet of Things-enabled digital monitoring technology presents a substantial growth opportunity for the Oil and Gas Accumulators Market, as operators increasingly seek predictive maintenance capabilities that improve operational uptime and reduce unplanned downtime across drilling and production operations. Manufacturers that can demonstrate validated, cost-competitive digital accumulator solutions are well positioned to capture share as operators continue prioritizing operational efficiency alongside traditional safety considerations.
Growing development of carbon capture and storage projects presents a longer-term opportunity for accumulator manufacturers to extend their product portfolios into corrosion-resistant designs suited to CO2 injection system applications. As carbon capture pilot projects continue to mature across regions such as the North Sea, manufacturers with established specialized material engineering capabilities are positioned to capture a disproportionate share of this emerging demand.
Recent Developments:
- 2024: Parker Hannifin secured a contract to supply hydraulic accumulators for a major oilfield expansion project in Saudi Arabia, supporting increased production capacity as part of the kingdom's ongoing energy infrastructure investment program.
- 2025: Eaton completed the acquisition of AccuTech Ltd., a United Kingdom-based accumulator manufacturer, strengthening its footprint in the European oil and gas equipment market.
- 2025: HYDAC International opened a new research and development center in Germany dedicated to innovating accumulator technologies for oil and gas applications.
Oil and Gas Accumulators Market Key Players
- Parker Hannifin Corporation
- Eaton Corporation plc
- Bosch Rexroth AG
- HAWE Hydraulik SE
- Hydac Verwaltung GmbH
- Nippon Accumulator Co., Ltd.
- NOK Corporation
- Airmo Inc.
- Hydroll
- Accumulators, Inc.
- Rotec Hydraulics Ltd.
- Roth Industries GmbH & Co. KG
- Freudenberg Sealing Technologies
- Olaer Group
- Hystat Systems Ltd.
- Servi Fluid Power, Inc.
- Schlumberger Limited (SLB)
- Baker Hughes Company
- Halliburton Company
- National Oilwell Varco, Inc.
Oil and Gas Accumulators Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.63 Billion |
| Market Size by 2035 | USD 0.99 Billion |
| CAGR | CAGR of 4.65% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Bladder Accumulators, Piston Accumulators, Diaphragm Accumulators, Others) • By Application (Blowout Preventer & Well Control, Pressure Maintenance, Energy Storage, Shock Absorption & Dampening, Flow Pulsation Control, Others) • By Deployment (Onshore, Offshore) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Parker Hannifin Corporation; Eaton Corporation plc; Bosch Rexroth AG; HAWE Hydraulik SE; Hydac Verwaltung GmbH; Nippon Accumulator Co., Ltd.; NOK Corporation; Airmo Inc.; Hydroll; Accumulators, Inc.; Rotec Hydraulics Ltd.; Roth Industries GmbH & Co. KG; Freudenberg Sealing Technologies; Olaer Group; Hystat Systems Ltd.; Servi Fluid Power, Inc.; Schlumberger Limited (SLB); Baker Hughes Company; Halliburton Company; National Oilwell Varco, Inc. |
Frequently Asked Questions
Leading companies in the Oil and Gas Accumulators Market include Parker Hannifin, Eaton, Bosch Rexroth, HAWE Hydraulik, and Hydac, among others.
Key opportunities include continued integration of IoT-enabled digital monitoring technology for predictive maintenance, and growing development of carbon capture and storage projects requiring corrosion-resistant accumulator designs.
Increasing exploration and production activities worldwide, combined with implementation of increasingly stringent safety and regulatory measures governing well-control systems, is the major factor driving market growth.
The Blowout Preventer & Well Control segment dominated the Oil and Gas Accumulators Market with approximately 34.50% share in 2025.
North America dominated the Oil and Gas Accumulators Market in 2025 with approximately 36.50% share, reflecting the region's position as a powerhouse of drilling and completion activity, led by the United States.
