
Oleochemicals Market Report Scope & Overview:
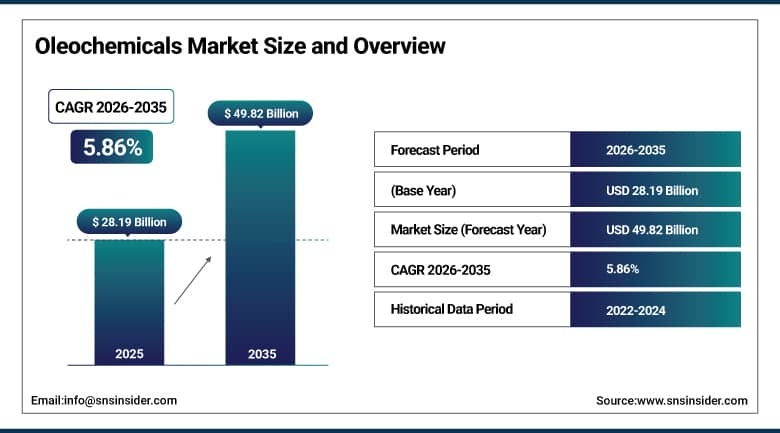
The Oleochemicals Market size was valued at USD 28.19 Billion in 2025 and is expected to reach USD 29.84 Billion in 2026, rising to USD 49.82 Billion by 2035. The market is forecast to grow at a CAGR of 5.86% during 2026–2035. Oleochemicals are chemicals made from plant oils and animal fats, with fatty acids, fatty alcohols, glycerin and methyl esters as the main families. They serve as raw materials for soaps, detergents, cosmetics, lubricants, plastics additives, food ingredients and coatings, and buyers choose them for biodegradability and renewable origin compared with petroleum routes.
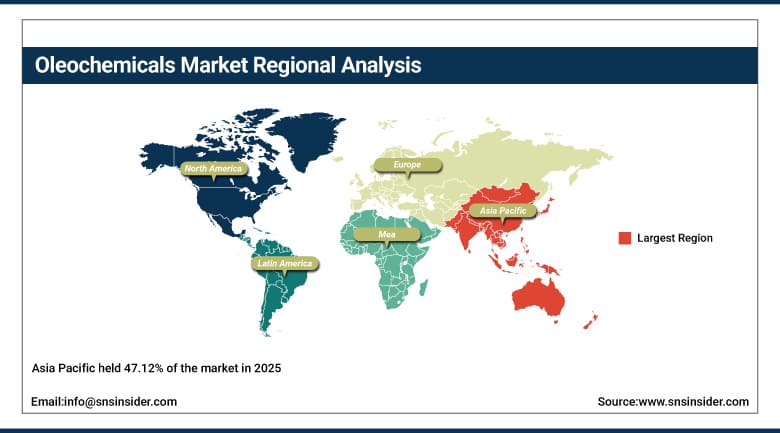
Asia Pacific accounted for the largest share of the market, at 47.12% in 2025, because palm and coconut oil are grown and refined in Indonesia and Malaysia, where integrated producers run large plants near the plantations. Europe follows, supported by specialty ester makers and strong rules on bio-based content, while North America benefits from home care, lubricant and personal care demand. Asia Pacific is also the fastest growing region, as China and India add detergent, cosmetics and surfactant capacity, and as producers in Southeast Asia move further into higher value derivatives.
To Get More Information On Oleochemicals Market - Request Free Sample Report
Key Report Takeaways
-
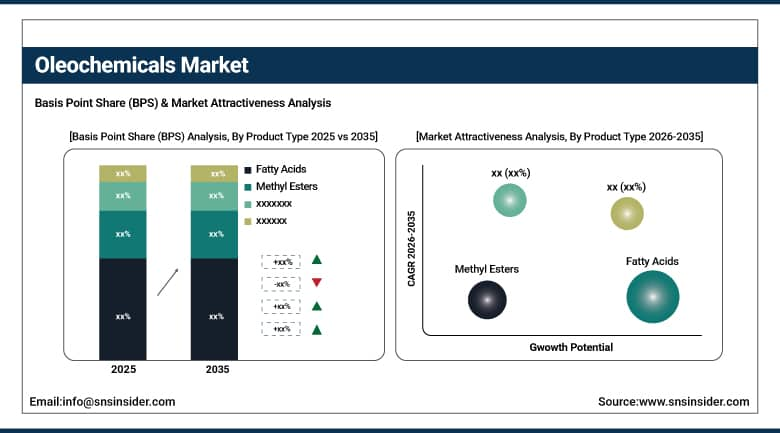
By product type, fatty acids held 40.58% in 2025, while methyl esters are the fastest growing.
-
By application, soaps and detergents held 33.14% in 2025, while personal care and cosmetics is the fastest growing.
-
By feedstock, vegetable oils held 62.87% in 2025 and are also the fastest growing.
-
By form, liquid held 63.45% in 2025, while solid is the fastest growing.
-
By region, Asia Pacific held 47.12% in 2025 and is also the fastest growing.
Market Trends and Insights
Buyers of home care and personal care products are asking for ingredients that are certified, traceable and free of deforestation links, which pushes producers toward segregated palm supply and non-palm options such as coconut, rapeseed and waste oils. New fermentation and recycled feedstock routes for fatty alcohols are moving from pilot stages toward commercial plans.
Producers are shifting output from basic fatty acids and glycerin toward esters, amines, amides and surfactants that earn higher margins, and are building plants close to customers in India, China and North America. Competition for palm oil from biodiesel mandates is raising feedstock costs and making cost pass-through clauses more common in supply contracts.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Shift from petrochemical to bio-based surfactants and ingredients |
+2.14% |
Global |
Long term (4 years or more) |
|
Growth of personal care, home care and cosmetics demand |
+1.62% |
Asia Pacific and Latin America |
Medium term (2 to 4 years) |
|
Regulation and retailer targets on biodegradability and renewable content |
+1.18% |
Europe and North America |
Medium term (2 to 4 years) |
|
Expansion of integrated palm-based capacity in Southeast Asia and India |
+0.94% |
Asia Pacific |
Short term (2 years or less) |
|
Wider use in lubricants, polymers and food ingredients |
+0.76% |
Global |
Medium term (2 to 4 years) |
Shift from Petrochemical to Bio-Based Surfactants and Ingredients
Detergent, cosmetic and industrial formulators are replacing petroleum-derived ingredients with those made from plant oils and animal fats, because they biodegrade faster and carry a lower fossil carbon footprint. Brand owners publish targets for renewable content in their products, and procurement teams place long-term orders with oleochemical suppliers to meet them. This steady switching widens the customer base for fatty acids, alcohols and esters in nearly every end use. The result is a durable, multi-year pull that supports both volume growth and better pricing for certified products.
Growth of Personal Care, Home Care and Cosmetics Demand
Rising incomes, urbanization and hygiene awareness in Asia Pacific, Latin America and Africa are increasing sales of soap, shampoo, skin care, laundry products and cosmetics. These products rely on glycerin, fatty alcohols, esters and fatty acid salts as emulsifiers, moisturizers and cleaning agents. Fast-moving consumer goods companies are adding capacity in India, Indonesia and Brazil, and local oleochemical supply near these factories lowers freight costs and strengthens demand. Rising online sales of beauty and household goods add further volume, as new brands launch products across regional markets.
Regulation and Retailer Targets on Biodegradability and Renewable Content
Environmental rules in Europe and North America limit the use of persistent or poorly degradable ingredients in cleaning and personal care products, and ecolabels favor plant-based surfactants. Retailers set their own requirements for the origin and sustainability of the oils behind these ingredients, which supports certified suppliers. Compliance with these rules becomes a selling point for oleochemical makers that can show traceable supply and low environmental impact. Producers with early certification gain preferred supplier status, and long contracts give them better visibility on future volumes.
Expansion of Integrated Palm-Based Capacity in Southeast Asia and India
Producers in Malaysia and Indonesia operate plants next to plantations and refineries, which gives them cost and supply security advantages, and they continue to add fractionation, hydrogenation and fatty alcohol units. Indian groups are also widening fatty alcohol and glycerin output to serve local detergent and personal care makers. New capacity lowers import dependence, shortens delivery times and encourages downstream firms to locate near these supply hubs. Sustained investment by large groups signals confidence in long-term demand and is lifting export volumes to Europe and North America.
Wider Use in Lubricants, Polymers and Food Ingredients
Esters from plant oils are gaining use in biodegradable lubricants and hydraulic fluids for forestry, marine and agricultural machinery, where spills are a concern. Fatty acid derivatives act as plasticizers, stabilizers and release agents in polymers, and emulsifiers made from glycerin and fatty acids are common in bakery, confectionery and dairy products. Each of these outlets adds volume beyond the large soap and detergent base. Together, these uses give producers a wider set of customers and help them offset slower growth in basic soap bases.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Volatile palm oil and other feedstock prices |
-0.34% |
Global |
Short term (2 years or less) |
|
Sustainability concerns and deforestation rules on palm supply |
-0.22% |
Europe and Asia Pacific |
Medium term (2 to 4 years) |
|
Competition for feedstock from biodiesel and renewable diesel |
-0.14% |
Asia Pacific and Latin America |
Medium term (2 to 4 years) |
|
Cost gap versus petrochemical alternatives |
-0.08% |
Global |
Long term (4 years or more) |
Volatile Palm Oil and Other Feedstock Prices
Vegetable oils account for most of the cost of oleochemicals, and the prices of palm kernel, palm and coconut oil swing with weather, export taxes, currency moves and policy decisions in Indonesia and Malaysia. Producers cannot always pass these changes on to customers quickly, which squeezes margins and makes long-term contracts hard to price. Smaller processors with limited storage and hedging tools are most exposed when prices rise sharply. Many producers now buy forward and use palm kernel futures, but these tools carry a cost and cannot cover every contract.
Sustainability Concerns and Deforestation Rules on Palm Supply
Palm cultivation is linked to forest loss, peatland conversion and labor concerns, and customers in Europe and North America demand proof of responsible sourcing. New European deforestation rules add documentation and traceability requirements that raise compliance costs for suppliers and importers. Segregated certified oil trades at a premium, and any supply chain lapse can lead to lost contracts and reputational damage for producers and brand owners. Smallholder farmers face the greatest difficulty in meeting such rules, which can narrow the supply base over time.
Competition for Feedstock from Biodiesel and Renewable Diesel
Biodiesel mandates in Indonesia and renewable diesel plants in the United States and Europe draw large volumes of palm and other oils, tightening the supply left for oleochemical processing. When mandates rise, fuel use claims first access to oil and pushes up purchase costs for chemical producers, which have less pricing power than fuel buyers backed by government support. Producers respond by signing multi-year oil supply deals and by investing in refining of alternative oils, yet these steps take time and capital.
Cost Gap Versus Petrochemical Alternatives
Petroleum-based surfactants and alcohols remain cheaper in many price-sensitive uses, especially when crude oil is low, and large detergent makers keep both routes open. Smaller brands and buyers in emerging markets often choose the lower-cost option unless regulation or retailer rules require a renewable alternative. This limits the pace at which oleochemicals can take share in bulk applications. Rising carbon costs on fossil inputs may narrow the gap over time, but cost parity in bulk grades is still some years away.
Oleochemicals Market Segment Analysis
By Product Type, Fatty Acids Dominate Oleochemicals Market; Methyl Esters to Register Fastest Growth.
Fatty acids account for 40.58% of the market in 2025 because they are the starting point for soaps, esters, metallic salts, amides and many other derivatives, and they are produced in large volumes by splitting palm, palm kernel and coconut oil. Stearic, oleic and lauric grades feed soap noodles, rubber, plastics, candles and lubricants. Producers with integrated fractionation plants can adjust grade mix quickly as demand shifts, which supports steady sales. Steady downstream demand keeps plants well used.
Methyl esters are expected to grow at a CAGR of 7.31% during 2026–2035. They are the direct feedstock for fatty alcohols, surfactants and sulfonates, and the shift of detergent and personal care makers toward bio-based surfactants is raising demand. New plants in Southeast Asia and India are being built with methyl ester units to supply downstream units, and some output also serves lubricant and solvent uses. Companies also supply them to industrial customers in lubricants, solvents and agricultural formulations.
By Application, Soaps and Detergents Dominate Oleochemicals Market; Personal Care and Cosmetics to Register Fastest Growth.
Soaps and detergents hold a 33.14% share in 2025 because laundry powders, liquids, bar soaps and dishwashing products use large volumes of fatty acid salts, fatty alcohol sulfates and glycerin each year. Demand is broad and steady in populous markets in Asia, Africa and Latin America, and formulators prefer plant-based inputs for biodegradability. Supply contracts between detergent makers and oleochemical producers are often long, which adds to stable volume. Growing urban populations add many more branded household buyers.
Personal care and cosmetics are projected to grow at a CAGR of 7.42% during 2026–2035. Skin care, hair care and color cosmetics use esters, fatty alcohols, glycerin and fatty acids as emollients, thickeners and emulsifiers, and consumers increasingly look for natural-origin claims. Premium and clean beauty brands pay more for certified and traceable ingredients, and rapid growth of the middle class in Asia lifts sales of these formulations. Online retail has shortened the path from launch to wide sales.
By Feedstock, Vegetable Oils Dominate Oleochemicals Market and Are Also Set to Register Fastest Growth.
Vegetable oils account for 62.87% of the market in 2025 and are expected to expand at a CAGR of 6.63% during 2026–2035. Palm, palm kernel, coconut, soybean and rapeseed oils supply most oleochemical output because they are available in volume at stable quality, and plantation-based producers control supply from field to refinery. Growth is also aided by certified oil programs, new coconut processing in the Philippines and Indonesia, and rising use of rapeseed and sunflower oils in Europe.
Animal fats such as tallow and grease remain important for soaps, lubricants and some fatty acids, particularly in North America and Europe, where rendering industries supply low-cost material. They are subject to supply limits tied to meat production and to strong competition from biofuel producers, and some consumer segments avoid animal-derived ingredients, which keeps their growth below that of vegetable oils. Interest in alternatives is growing, as processors look for ways to diversify supply and reduce exposure to palm prices.
By Form, Liquid Dominates Oleochemicals Market; Solid to Register Fastest Growth.
Liquid products hold a 63.45% share in 2025 because glycerin, methyl esters, fatty alcohol solutions, oleic acid and many ester grades are handled and shipped as liquids, which suits pumping and dosing in detergent, cosmetics and lubricant plants. Bulk tank storage and tanker delivery lower handling costs for large buyers, and liquid grades mix readily into formulations, so they remain the usual choice for continuous manufacturing lines. Liquid glycerin and esters also move easily by pipeline within large industrial sites.
Solid products are projected to grow at a CAGR of 6.27% during 2026–2035. Flakes, pastilles, beads and noodles of stearic acid, fatty alcohols and soap bases are easy to store, transport and weigh, and they are favored by buyers in regions with long supply routes and limited tank infrastructure. Rising demand from plastics, candles and cosmetic bases supports the segment. Producers also gain from lower transport volume per unit of active content, which suits exports to distant markets.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
76.38% |
|
Europe |
Germany |
24.62% |
|
Asia Pacific |
Indonesia |
31.47% |
|
Middle East & Africa |
South Africa |
29.16% |
|
Latin America |
Brazil |
46.38% |
Asia Pacific Oleochemicals Market
Asia Pacific held 47.12% of the market in 2025 and is the fastest growing region, with a projected CAGR of 7.94% during 2026–2035. Indonesia leads the region, followed closely by Malaysia, where integrated producers run fatty acid, fatty alcohol and glycerin plants near the plantations. Export-oriented capacity, low feedstock costs and strong links to detergent and personal care makers keep the region at the center of global supply. Large investments in refining and export terminals continue to improve logistics for buyers across the world.
China and India are the main demand growth markets, with large detergent, cosmetics and surfactant sectors and rising local production of fatty alcohols. Japan has a mature base of specialty esters and personal care ingredients, and the Philippines supplies coconut-based products. Governments in the region also encourage downstream processing of palm oil to capture more value inside producing countries. Government support for industrial parks in Gujarat, Jiangsu and Guangdong lowers set-up costs for new units, and joint ventures with global consumer goods brands bring stable offtake for new output.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Oleochemicals Market
North America held 17.06% of the market in 2025, led by the United States. The U.S. market was valued at USD 3.67 Billion in 2025 and is expected to register a CAGR of 5.12% during 2026–2035. Demand comes from home care, personal care, lubricants and food ingredients, and the region depends on imports of palm-based intermediates alongside local tallow and soybean oil. Brand owners headquartered in the country set sourcing rules that shape the global supply chain. Local capacity is expanding steadily.
Canada adds demand through cleaning products, forestry lubricants and industrial uses. Mexico is counted in Latin America, although its detergent and personal care factories tie it closely to North American supply chains. New plants and partnerships focus on bio-based surfactants, renewable lubricants and fatty alcohols to reduce reliance on imports from Asia. Trade associations and research programs support bio-based lubricants, and federal procurement preferences for biobased products give added demand from public agencies and contractors across the country. This support keeps volumes steady.
Europe Oleochemicals Market
Europe accounted for 22.34% of the market in 2025, with Germany as the leading country. The region hosts specialist producers of esters, amides and high-purity fatty acids, and it is a large buyer of imported palm-based intermediates for local processing. Strict rules on biodegradability and chemical safety favor plant-based surfactants and give the region a strong position in premium and specialty products. Large buyers in the region also run supplier audits and set strict supplier codes that favor producers with full certification and clear records.
France, the Netherlands, Belgium, Italy and Spain are important markets, with large detergent, cosmetics and lubricant sectors. Rapeseed and sunflower oils supply local needs, while new deforestation rules push buyers to demand certified supply. Producers in the region invest in bio-based esters, biosurfactants and recycled feedstock to defend margins against imports from Asia. Governments back research into bio-based chemistry through innovation funds, and universities work with industry on enzymatic routes and new surfactant structures that could reduce reliance on imports.
Latin America Oleochemicals Market
Latin America accounted for 7.82% of the market in 2025, with Brazil as the leading country. Brazil has a large home care and personal care industry, access to soybean and castor oils, and growing interest in bio-based inputs. Mexico is the second major market, supported by detergent and cosmetics production for local and export sales, and demand grows with population and income. Large consumer goods companies operate plants in the country and prefer to source ingredients close to their factories.
Argentina, Colombia and Chile add demand from cleaning products, food ingredients and industrial uses. Regional producers use soybean, sunflower and castor oil, while palm oil from Colombia and Ecuador supplies a growing local chain. Imports of fatty alcohols and specialty esters from Asia and Europe still meet much of the need for higher value grades. Trade agreements within the region ease the movement of ingredients, and governments are encouraging local processing of vegetable oils to add value and create jobs in agricultural areas.
Middle East & Africa Oleochemicals Market
Middle East & Africa held 5.66% of the market in 2025. South Africa leads the region, with established detergent, cosmetics and food industries, and it relies on imported palm-based intermediates and local processing of sunflower and soybean oils. Population growth and rising hygiene spending across the region lift demand for soap and cleaning products. Large retail chains and multinational brands source from regional distributors, and investment in port facilities at Durban and Cape Town helps improve access to imported raw materials.
Egypt, Nigeria, Turkey and Saudi Arabia add demand from soaps, detergents and personal care, and Gulf producers are exploring bio-based chemicals as part of industrial diversification. Limited local capacity means much of the region depends on imports, which creates openings for suppliers from Southeast Asia and Europe. Local firms are starting to invest in mixing and packing plants for nearby markets, and trade fairs and distributor networks help new suppliers reach buyers across the region. Free trade zones in the Gulf offer tax benefits that support such projects.
Competitive Landscape
The Oleochemicals Market is fragmented. Integrated palm-based producers in Malaysia and Indonesia, specialist European ester makers and diversified chemical groups compete on feedstock access, plant scale, product range and certified supply. The five largest producers account for a minority of global output, and many regional firms serve local detergent and cosmetics makers.
Companies pursue capacity additions in downstream derivatives, partnerships with consumer goods brands and investments in non-palm and recycled feedstock. Price changes in palm oil and biodiesel policy strongly influence margins across the group.
Oleochemicals Market Industry Leaders
1. IOI Oleochemical: Malaysian producer of fatty acids, fatty alcohols and glycerin within an integrated palm-based chain.
2. KLK OLEO: Malaysian oleochemical arm of Kuala Lumpur Kepong with plants in Asia and Europe.
3. Wilmar International: Singapore-based agribusiness group with large oleochemical operations.
4. Musim Mas Group: Singapore-based integrated palm oil and oleochemical producer.
5. BASF: German chemical group producing fatty alcohols and ester-based ingredients.
Companies Covered in this Report
-
IOI Oleochemical
-
KLK OLEO
-
Wilmar International
-
Musim Mas Group
-
BASF
-
Emery Oleochemicals
-
Oleon
-
Kao Corporation
-
PT Ecogreen Oleochemicals
-
Godrej Industries
-
VVF
Recent Industry Developments
-
January 2024: Godrej Industries Group announced a plan to invest INR 600 Crore over four years to expand its Valia facility in Gujarat, India.
-
February 2025: KLK OLEO opened a representative office in Mumbai, India.
-
March 2025: Indonesia implemented its B40 biodiesel mandate, increasing local demand for palm oil.
-
May 2025: Louis Dreyfus Company inaugurated a glycerin refining plant and edible oil packaging line in Lampung, Indonesia.
-
December 2025: The Roundtable on Sustainable Palm Oil reported certification of 5.10 Million hectares of oil palm plantations across 24 countries.
Scope and Research Methodology
This study estimates the Oleochemicals Market for 2025 as the base year and forecasts it through 2035. The scope covers fatty acids, fatty alcohols, glycerin, methyl esters and related derivatives made from vegetable oils and animal fats, including their use in soaps, detergents, personal care, lubricants, plastics additives and food ingredients. Values are reported in USD at the producer selling price and are segmented by product type, application, feedstock, form and region. Petrochemical equivalents and biodiesel as a fuel are excluded from the scope. Reported values exclude taxes, freight and distributor margins, and all figures are converted to USD at fixed annual rates. The study period for historical data runs from 2021 to 2025.
Secondary research included company annual reports, investor presentations, regulatory filings, customs and trade statistics, plantation and refining data, association publications and peer-reviewed literature. Primary research consisted of structured interviews and surveys with plant managers, procurement heads, formulators and distributors in major producing and consuming regions. Expert opinions were weighed against published data to correct for bias, and responses were screened for relevance and consistency across regions. Interviews were held with participants from large integrated producers and smaller regional firms to capture the full range of pricing and demand patterns.
Market size was built from the bottom up using plant capacity, utilization and selling prices, and was cross-checked from the top down against feedstock availability and downstream consumption of detergents and personal care products. Triangulation across these views fixed the base year value. Forecasts consider feedstock prices, biofuel policy, regulation and demand growth, and segment and regional shares were assigned from production and consumption patterns. Key assumptions were reviewed with industry experts before the final model was locked. Currency effects were removed by holding exchange rates constant throughout the forecast period, and growth rates were tested under conservative and optimistic cases.
Oleochemicals Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 28.19 Billion |
| Market Size by 2035 | USD 49.82 Billion |
| CAGR | CAGR of 5.86% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Fatty Acids, Fatty Alcohols, Glycerin, Methyl Esters, and Others) • By Application (Soaps and Detergents, Personal Care and Cosmetics, Food and Beverages, Plastics and Lubricants, and Others) • By Feedstock (Vegetable Oils and Animal Fats) • By Form (Liquid and Solid) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | IOI Oleochemical, KLK OLEO, Wilmar International, Musim Mas Group, BASF, Emery Oleochemicals, Oleon, Kao Corporation, Evonik Industries, PT Ecogreen Oleochemicals, Godrej Industries, VVF |

Frequently Asked Questions
The market was valued at USD 28.19 Billion in 2025 and is projected to reach USD 49.82 Billion by 2035, growing at a CAGR of 5.86% during 2026–2035.
Asia Pacific leads, with a 47.12% share in 2025, and it is also expected to grow fastest, at a CAGR of 7.94% during 2026–2035.
Fatty acids, soaps and detergents, vegetable oils and liquid products lead, while methyl esters, personal care and cosmetics, vegetable oils and solid products grow fastest.
The shift to bio-based ingredients, growth of personal care and home care, regulation on biodegradability, palm capacity expansion and wider industrial use drive demand.
IOI Oleochemical, KLK OLEO, Wilmar International, Musim Mas Group and BASF lead, along with Emery Oleochemicals, Oleon, Kao Corporation.
