
PARP Inhibitor Biomarkers Market Report Scope & Overview:
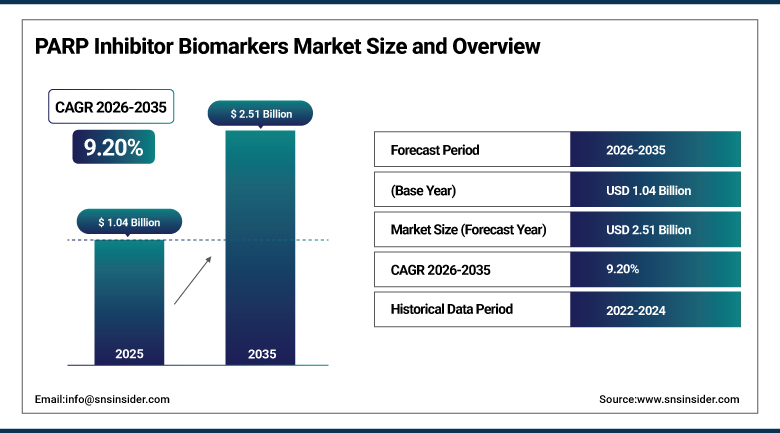
The PARP Inhibitor Biomarkers Market was valued at USD 1.04 Billion in 2025 and is expected to reach USD 2.51 Billion by 2035, growing at a CAGR of 9.20% from 2026-2035.
The PARP Inhibitor Biomarkers Market covers tests, kits, assays and services that identify patients whose tumors are likely to respond to PARP inhibitors such as olaparib, niraparib, rucaparib and talazoparib. Tests detect BRCA1 and BRCA2 mutations, homologous recombination deficiency (HRD) and wider homologous recombination repair gene changes, using next-generation sequencing, PCR and related methods. Growth is supported by expanding drug indications in ovarian, breast, prostate and pancreatic cancer, while test cost, reimbursement gaps and lab capacity shape adoption.
⮞In March, 2026, Myriad Genetics announced FDA approval of its MyChoice CDx test as a companion diagnostic for Zejula (niraparib) in advanced ovarian cancer. The test identifies homologous recombination deficiency-positive patients through BRCA1/2 mutations, genomic instability, or both, and Myriad describes it as the only companion diagnostic in the United States for this use.
To Get more information PARP Inhibitor Biomarkers Market - Request Free Sample Report
PARP Inhibitor Biomarkers Market Trends
- Shift from BRCA-only testing to broader HRD and homologous recombination repair panels
- Use of next-generation sequencing to combine mutation and genomic instability readouts
- Development of distributable kits that let local laboratories run companion tests
- Expansion of PARP inhibitor use into prostate, pancreatic and early-stage breast cancer
- Growth of liquid biopsy options for patients without tumor tissue
- Partnerships between drug makers and diagnostics firms for companion test development
U.S. PARP Inhibitor Biomarkers Market Outlook
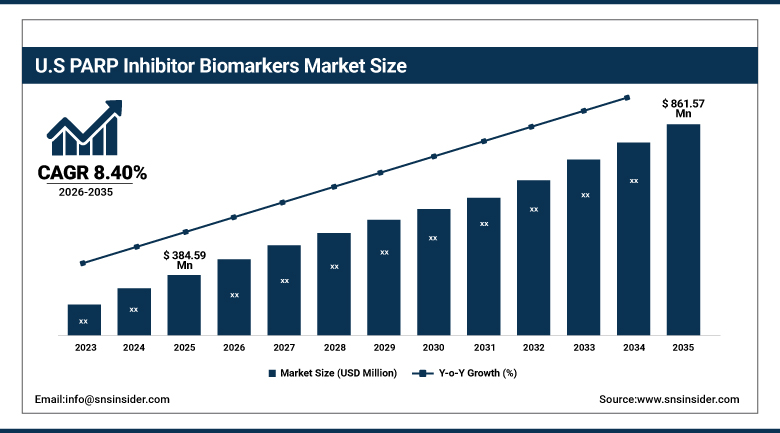
The U.S. PARP Inhibitor Biomarkers Market was valued at USD 384.59 Million in 2025 and is expected to reach USD 861.57 Million by 2035, growing at a CAGR of 8.40% from 2026-2035.
The U.S. PARP Inhibitor Biomarkers Market is the largest national market, supported by early FDA approvals of PARP inhibitors and their companion diagnostics, broad access to next-generation sequencing, and strong oncology networks. Guidelines recommend BRCA and HRD testing for ovarian cancer, and testing is expanding in breast, prostate and pancreatic cancer. Growth is moderated by reimbursement variation, prior authorization requirements and the shift of some drug indications as new trial data change use.
⮞In September, 2024, Foundation Medicine announced FDA approval of FoundationOne CDx and FoundationOne Liquid CDx as companion diagnostics for Lynparza (olaparib) plus abiraterone in BRCA-mutated metastatic castration-resistant prostate cancer. The approval added a liquid biopsy route for patients whose tissue is not available.
PARP Inhibitor Biomarkers Market Segment Analysis
- By Product, kits segment dominated the PARP Inhibitor Biomarkers Market in 2025 with an estimated 61.00% share; assays segment is the fastest-growing segment, with an estimated CAGR of 10.40% during 2026–2035.
- By Service, BRCA1/2 testing segment dominated the PARP Inhibitor Biomarkers Market in 2025 with an estimated 40.00% share; HRD testing segment is the fastest-growing segment, with an estimated CAGR of 11.20% during 2026–2035.
- By Application, breast cancer segment dominated the PARP Inhibitor Biomarkers Market in 2025 with an estimated 44.00% share; ovarian cancer segment is the fastest-growing segment, with an estimated CAGR of 10.60% during 2026–2035.
- By End Use, hospitals and clinics segment dominated the PARP Inhibitor Biomarkers Market in 2025 with an estimated 41.00% share; diagnostic laboratories segment is the fastest-growing segment, with an estimated CAGR of 10.10% during 2026–2035.
By Product, Kits Dominates PARP Inhibitor Biomarkers Market; Assays to Register Fastest Growth.
Kits dominate the PARP Inhibitor Biomarkers Market because laboratories prefer packaged workflows with reagents, controls and validated protocols that deliver consistent results for BRCA and HRD testing. Regulatory-cleared and CE-marked kits give hospitals confidence in test accuracy and support reimbursement, and kit sales repeat with each batch of samples. Large diagnostics firms bundle kits with sequencers, software and support, which locks in long-term consumable purchases and favors established suppliers in the market. Training and technical support from suppliers also reduce errors in smaller laboratories.
Assays are projected to register the fastest growth as laboratories develop and validate in-house and distributable tests for HRD and wider repair gene panels. Demand is rising for flexible assays that can be run on common sequencing platforms and adapted as new drug indications appear. Contract laboratories and academic centers also use assays for clinical trial enrollment, and partnerships between drug makers and diagnostics companies are generating new assay formats. Cloud-based reporting tools offered with these assays also help laboratories deliver clear results to oncologists quickly.
⮞In October, 2024, Pillar Biosciences announced an expanded partnership with Illumina for a broader OncoReveal portfolio, including a BRCA1/2 and copy number variant panel for the MiSeq i100 Series.
By Service, BRCA1/2 Testing Dominates PARP Inhibitor Biomarkers Market; HRD Testing to Register Fastest Growth.
BRCA1/2 testing dominates the PARP Inhibitor Biomarkers Market because it was the first approved biomarker for PARP inhibitor use and remains required in guidelines for ovarian, breast, prostate and pancreatic cancer. Germline and tumor testing are both widely available, and hereditary cancer programs generate a steady flow of samples. Laboratories offering BRCA tests also support family risk assessment, which adds volume beyond patients being considered for drug treatment. Established reimbursement codes for BRCA tests in many countries also keep volumes steady and predictable for providers.
HRD testing is projected to register the fastest growth because it identifies a larger group of patients who benefit from PARP inhibitors, including many without BRCA mutations. Approximately half of advanced ovarian tumors are HRD-positive, which widens the eligible population. Genomic instability scores combined with BRCA status are being built into companion diagnostics, and distributable HRD tests will let more hospitals in more countries run the test locally. Clear reporting of score thresholds also helps oncologists interpret results, which supports wider ordering of the test.
⮞On May 30, 2024, QIAGEN and Myriad Genetics announced development of a distributable NGS-based HRD test combining QIAGEN's QIAseq xHYB technology with Myriad's MyChoice CDx technology, for research use and companion diagnostics worldwide.
By Application, Breast Cancer Dominates PARP Inhibitor Biomarkers Market; Ovarian Cancer to Register Fastest Growth.
Breast cancer dominates the PARP Inhibitor Biomarkers Market because of its large patient base and the wide use of germline BRCA testing in hereditary risk assessment and treatment planning. PARP inhibitors are approved for BRCA-mutated HER2-negative breast cancer, and testing guidelines recommend BRCA analysis for a growing share of newly diagnosed patients. Large screening programs and genetic counseling services generate many tests each year. Patient advocacy groups also raise awareness of genetic testing, which brings more women into BRCA analysis.
Ovarian cancer is projected to register the fastest growth because it is the cancer where HRD testing is most established and where PARP inhibitor maintenance therapy has the largest effect on survival. Guidelines call for BRCA and HRD testing at diagnosis, and new approvals extend companion diagnostics to first-line use. Rising treatment rates in Asia Pacific and Europe are adding testing volume, and prostate and pancreatic cancer add further growth beyond the main segments. Clinical trials in ovarian cancer also require biomarker screening, which adds samples through research programs.
By End Use, Hospitals and Clinics Dominates PARP Inhibitor Biomarkers Market; Diagnostic Laboratories to Register Fastest Growth.
Hospitals and clinics dominate the PARP Inhibitor Biomarkers Market because oncologists order tests at diagnosis and during treatment planning, and many large cancer centers run in-house molecular pathology units. These institutions sit at the center of tumor boards, where biomarker results shape drug choices. Direct access to patients, pathology samples and electronic health records supports fast turnaround, and integrated care networks encourage consistent testing across their hospitals. Tumor boards that review sequencing results also make hospitals a natural home for companion diagnostic testing and follow-up.
Diagnostic laboratories are projected to register the fastest growth as hospitals send complex sequencing tests to reference laboratories with scale, automation and expert interpretation. National and regional laboratory networks are adding HRD and homologous recombination repair panels, and they compete on turnaround time and test breadth. Outsourcing helps smaller hospitals offer advanced testing without capital investment, and contracts with drug makers for trial screening add further volume. Pharmaceutical companies also contract with laboratories to screen patients for studies of new drug combinations.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
86.00 |
|
Europe |
Germany |
25.00 |
|
Asia Pacific |
China |
36.00 |
|
Latin America |
Brazil |
52.00 |
|
Middle East & Africa |
Saudi Arabia |
27.00 |
North America PARP Inhibitor Biomarkers Market Insights
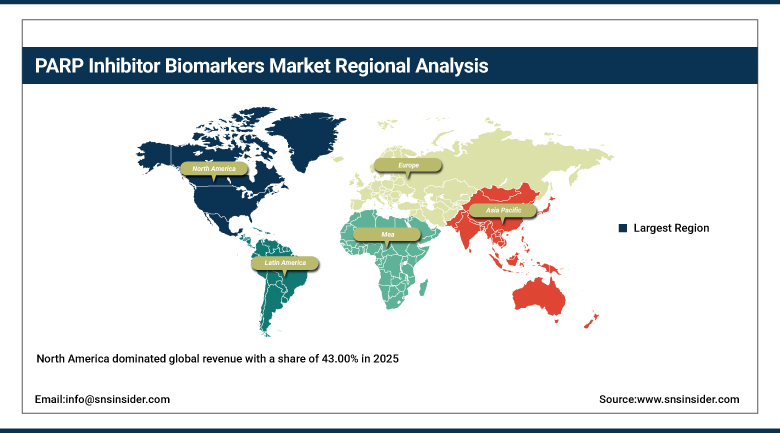
North America dominated global revenue with a share of 43.00% in 2025. The United States accounts for major share of regional demand, with Canada adding volume through provincial cancer programs. Myriad Genetics, Foundation Medicine, Illumina, Thermo Fisher Scientific, Guardant Health, NeoGenomics and Ambry Genetics serve laboratories and oncology networks across the region. Large academic cancer centers in the region also run their own sequencing programs and take part in many PARP inhibitor trials, which further supports testing rates.
Early FDA approvals of PARP inhibitors and companion diagnostics, strong precision oncology infrastructure and wide use of next-generation sequencing support leadership. Commercial insurers and Medicare cover BRCA and many HRD tests, which keeps testing rates high. Restraints include prior authorization steps, uneven coverage for broader panels and the high price of tumor sequencing, though liquid biopsy options and falling sequencing costs are widening access. Direct-to-clinician genetic counseling services and hereditary cancer clinics also feed a steady stream of patients into BRCA analysis.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe PARP Inhibitor Biomarkers Market Insights
In Europe Germany leads regional demand, followed by the United Kingdom, France, Italy and Spain, supported by national genomic testing programs and strong cancer networks. QIAGEN, Roche, CENTOGENE, Agilent Technologies, Illumina and Thermo Fisher Scientific are among the suppliers active in the region. Italy and Spain also expand regional testing networks. The Nordic countries add demand through national cancer registries and centralized molecular testing hubs, while Southern European nations are expanding access in major university hospitals.
European laboratories must meet the In Vitro Diagnostic Regulation, which raises validation cost but also rewards CE-marked kits and distributable tests. Reimbursement for HRD testing differs by country, and slow approval of new indications can delay uptake. Growing national cancer plans and rising use of PARP inhibitors in ovarian and breast cancer support steady demand for kits and reference laboratory services. Health technology assessment bodies also review companion diagnostics alongside drug approvals, which helps align test funding with new treatment indications.
⮞In May, 2024, Guardant Health announced EU IVDR certification for Guardant360 CDx, a liquid biopsy for tumor mutation profiling across solid cancers with companion diagnostic indications, opening a European route for blood-based testing.
Asia Pacific PARP Inhibitor Biomarkers Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 11.40% during 2026-2035. China leads regional demand, followed by Japan, India, South Korea and Australia, supported by expanding cancer treatment access, local PARP inhibitor approvals and growth of molecular diagnostics firms. Amoy Diagnostics, Thermo Fisher Scientific, Illumina and Roche supply tests used in the region. Local regulators have been approving locally made kits more quickly, and hospital chains in South Korea, Australia and Singapore are also adding HRD capacity as treatment guidelines expand.
China has a large pool of ovarian and breast cancer patients and a growing set of local diagnostic makers that offer BRCA and HRD panels at lower cost. Japan has long used BRCA companion tests, while India is expanding testing in private hospital chains and reference laboratories. Limited reimbursement, a shortage of molecular pathology capacity and low testing rates outside major cities restrain growth, though demand is rising quickly. Cooperation between multinational firms and regional laboratories on distributable kits is also helping smaller hospitals offer advanced testing at lower cost.
MEA & Latin America PARP Inhibitor Biomarkers Market Insights
In Latin America, Brazil leads, followed by Mexico, Argentina and Colombia, with regional demand growing. Private hospitals and reference laboratories offer BRCA testing, while public health systems are building access slowly. Samples are often sent to laboratories abroad, and cost, limited reimbursement and uneven oncology coverage affect testing rates. Argentina and Chile add steady volumes through private oncology groups and cancer institutes, while patient groups and drug makers support access programs for ovarian and breast cancer patients.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Qatar and South Africa lead demand. National genomics programs and large cancer centers in the Gulf are adding hereditary cancer and tumor testing, and CENTOGENE and other providers support local access. Limited oncology infrastructure and high test prices restrain adoption across much of Africa. South Africa, Turkey and Egypt add demand through university hospitals and private laboratories, and partnerships with global diagnostics firms are improving access to sequencing and genetic counseling services.
Market Dynamics
Growth Drivers: Expanding Drug Indications, Guideline Support and Companion Diagnostic Approvals
The widening use of PARP inhibitors across ovarian, breast, prostate and pancreatic cancer is the main driver of the PARP Inhibitor Biomarkers Market. Each new indication creates demand for a validated test, and guidelines from major oncology groups call for BRCA and HRD testing at diagnosis, which lifts testing rates. Greater awareness among oncologists also helps. Rising cancer incidence and longer survival on maintenance therapy also increase the number of patients who need testing.
Companion diagnostic approvals and partnerships between drug makers and test makers also support growth. Distributable kits let local laboratories run tests rather than send samples abroad, while falling sequencing costs and liquid biopsy options make testing available to more patients, including those without tissue samples. Public programs for hereditary cancer screening also add many BRCA tests each year.
Restraints: Cost, Reimbursement Gaps and Limited Laboratory Capacity
Next-generation sequencing for HRD and repair gene panels is expensive, and reimbursement varies widely across countries and payers. Where coverage is limited, patients may skip testing or be treated without biomarker guidance, which reduces volume. Small hospitals often cannot justify sequencing platforms, so samples are sent to outside laboratories.
Molecular pathology capacity is limited in many regions, and long turnaround times can delay treatment decisions. Changing drug labels and trial results can also narrow patient groups for some indications, which adds uncertainty for test makers. Complex reports also require trained genetic counselors who are in short supply.
Opportunities: Distributable Tests, Liquid Biopsy and Emerging Markets
Distributable HRD kits and in-house assays give hospitals in Europe, Asia Pacific and the Middle East local control over testing. Partnerships between large diagnostics firms and regional laboratories can speed approvals and widen access to PARP inhibitor candidates. Automation and faster sequencing workflows can lower per-sample cost and raise capacity for laboratories of all sizes.
Liquid biopsy and combined mutation and genomic instability tests offer new routes for patients without tumor tissue and for monitoring. Emerging markets with growing cancer treatment programs, including China, India and Brazil, offer large untapped volumes for providers that can build local capacity. Artificial intelligence tools for genomic instability scoring may also improve accuracy and shorten reporting times.
Recent Developments:
- In March 2026, Myriad Genetics received FDA approval of its MyChoice CDx test as a companion diagnostic for Zejula (niraparib) in advanced ovarian cancer. The test identifies HRD-positive patients through BRCA1/2 mutations, genomic instability, or both.
- In October 2024, Pillar Biosciences expanded its partnership with Illumina for the OncoReveal portfolio. The expansion includes a BRCA1/2 and copy number variant panel for the MiSeq i100 Series.
- In September 2024, Foundation Medicine announced FDA approval of FoundationOne CDx and FoundationOne Liquid CDx as companion diagnostics for Lynparza plus abiraterone. The approval covers BRCA-mutated metastatic castration-resistant prostate cancer.
PARP Inhibitor Biomarkers Market Key Players are:
- Myriad Genetics, Inc.
- Illumina, Inc.
- Thermo Fisher Scientific, Inc.
- Foundation Medicine, Inc.
- QIAGEN N.V.
- Guardant Health, Inc.
- Agilent Technologies, Inc.
- F. Hoffmann-La Roche AG
- Pillar Biosciences, Inc.
- NeoGenomics Laboratories, Inc.
- Ambry Genetics
- CENTOGENE N.V.
- Amoy Diagnostics Co., Ltd.
- Invitae Corporation
- Bio-Rad Laboratories, Inc.
- Siemens Healthineers AG
- AstraZeneca PLC
- GSK plc
- Pfizer Inc.
- Merck & Co., Inc.
PARP Inhibitor Biomarkers Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.04 Billion |
| Market Size by 2035 | USD 2.51 Billion |
| CAGR | CAGR of 9.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Kits and Assays) • By Service (BRCA1/2 Testing, HRD Testing, HRR Testing, and Others) • By Application (Breast Cancer, Ovarian Cancer, Prostate Cancer, and Others) • By End Use (Hospitals and Clinics, Diagnostic Laboratories, Academic and Research Institutes, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Myriad Genetics, Inc.; Illumina, Inc.; Thermo Fisher Scientific, Inc.; Foundation Medicine, Inc.; QIAGEN N.V.; Guardant Health, Inc.; Agilent Technologies, Inc.; F. Hoffmann-La Roche AG; Pillar Biosciences, Inc.; NeoGenomics Laboratories, Inc.; Ambry Genetics; CENTOGENE N.V.; Amoy Diagnostics Co., Ltd.; Invitae Corporation; Bio-Rad Laboratories, Inc.; Siemens Healthineers AG; AstraZeneca PLC; GSK plc; Pfizer Inc.; Merck & Co., Inc. |

Frequently Asked Questions
Key players include Myriad Genetics, Inc., Illumina, Inc., Thermo Fisher Scientific, Inc., Foundation Medicine, Inc., QIAGEN N.V., Guardant Health, Inc., Agilent Technologies, Inc. and F. Hoffmann-La Roche AG.
Key opportunities include distributable HRD kits, liquid biopsy companion diagnostics and growing cancer testing programs in China, India and Brazil.
The major growth factor is the expansion of PARP inhibitor indications across ovarian, breast, prostate and pancreatic cancer, together with guideline-backed BRCA and HRD testing.
By Product, the Kits segment dominated the market in 2025 with an estimated 61.00% share, supported by validated, packaged workflows for BRCA and HRD testing.
North America dominated the market with a share of 43.00% in 2025, driven by early companion diagnostic approvals, sequencing access and oncology networks.
