
Patient Experience Technology Market Report Scope & Overview:
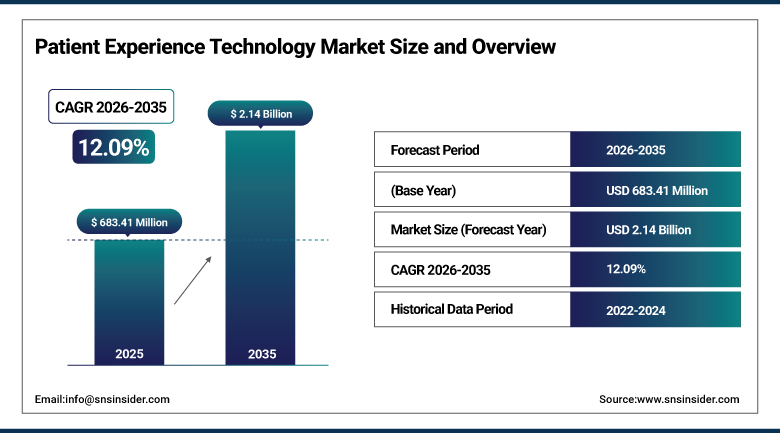
The Patient Experience Technology Market was valued at USD 683.41 Million in 2025 and is expected to reach USD 2.14 Billion by 2035, growing at a CAGR of 12.09% from 2026-2035.
The Patient Experience Technology Market is expanding as hospitals, clinics and payers invest in digital tools that make care easier to find, book, understand and rate. Patients now expect the same convenience from health services that they find in retail and banking, and providers see better access and satisfaction as a way to retain patients. Vendors are adding artificial intelligence assistants, text-based reminders and bedside engagement screens to portals and survey platforms. Quality programs that link payment to patient feedback further raise spending. Software and platforms form the largest component, and cloud delivery is spreading quickly. North America holds the largest share, while Asia Pacific is projected to grow fastest.
⮞In October 2025, Qualtrics agreed to acquire Press Ganey Forsta, a patient experience measurement business used by 41,000 providers in 30 countries. The agreement shows how experience management software is consolidating around providers of large healthcare customer bases.
To Get more information Patient Experience Technology Market - Request Free Sample Report
Patient Experience Technology Market Trends
-
Introduction of AI assistants inside patient portals for scheduling, billing questions and care navigation
-
Shift from paper and phone processes to digital intake, text reminders and self-service check-in
-
Use of real-time feedback and service recovery tools that act on patient comments during a stay
-
Spread of smart bedside screens and connected patient rooms that link entertainment, education and care teams
-
Consolidation among survey, access and payment vendors to offer complete patient journey platforms
U.S. Patient Experience Technology Market Outlook
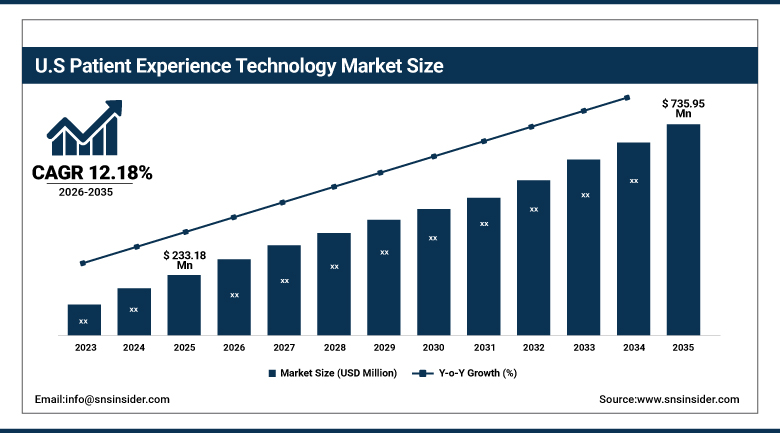
The U.S. Patient Experience Technology Market was valued at USD 233.18 Million in 2025 and is expected to reach USD 735.95 Million by 2035, growing at a CAGR of 12.18% from 2026-2035.
The U.S. Patient Experience Technology Market is the largest national market, shaped by federal patient survey programs, value-based payment models and widespread portal use. Hospitals are measured on patient ratings, and these scores affect reimbursement and public reputation. Health systems therefore spend on survey platforms, digital front doors and automated outreach that reduce missed appointments and phone wait times. Large electronic health record vendors bundle portals and AI assistants with their core systems, while specialist companies focus on access, intake and payments. Federal interoperability rules also push providers to give patients easier access to their own data. Demand is highest among large integrated delivery networks.
⮞The updated Hospital Consumer Assessment of Healthcare Providers and Systems survey applies to patients discharged on January 1, 2025 and after, according to the Centers for Medicare and Medicaid Services. The revised questionnaire changes what hospitals measure and drives updates to survey and analytics tools.
Patient Experience Technology Market Segment Analysis
-
By Component, the Software and Platforms segment dominated the Patient Experience Technology Market with approximately 57.20% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 12.89%.
-
By Application, the Patient Communication and Engagement segment dominated the Patient Experience Technology Market with approximately 27.78% share in 2025, while the Care Coordination and Navigation segment is the fastest growing with a CAGR of approximately 13.27%.
-
By Deployment, the Cloud segment dominated the Patient Experience Technology Market with approximately 57.29% share in 2025, and is also the fastest growing with a CAGR of approximately 14.84%.
-
By End User, the Hospitals and Health Systems segment dominated the Patient Experience Technology Market with approximately 44.44% share in 2025, while the Home Healthcare Providers segment is the fastest growing with a CAGR of approximately 13.03%.
By Component, Software and Platforms Dominates the Patient Experience Technology Market and Services Grows Fastest
Software and platforms remain the dominant component because portals, survey systems, scheduling engines and communication tools form the base of every patient experience program. Providers prefer subscription platforms that connect to their electronic health records and update frequently, replacing older point products that required separate logins. Vendors compete on the depth of integration, analytics and the quality of artificial intelligence assistants that answer routine questions. Because software is bought at the enterprise level and renewed over several years, it also produces the recurring revenue base that supports continued product investment across the industry. Product roadmaps now center on unified platforms that combine access, feedback and payments.
Services are growing fastest as health systems seek help with implementation, workflow redesign, survey administration and patient outreach. Many hospitals lack the staff to configure portals, train front-desk teams and act on feedback, so they hire vendors to manage these tasks. Post-discharge calls, service recovery rounding and managed communication campaigns are common examples of outsourced work. Providers that see mixed results from technology alone are adding coaching and analytics support, which raises the share of contract spending tied to adoption and measurable gains in patient ratings. Vendors report that managed services often lead to larger software renewals.
⮞In August 2026, Community Health Network adopted Emmie, an AI assistant built into Epic's MyChart patient portal. The adoption shows how assistants are becoming a standard feature of core portal software.
By Application, Patient Communication and Engagement Dominates the Patient Experience Technology Market and Care Coordination and Navigation Grows Fastest
Patient communication and engagement lead because messaging, reminders, education content and outreach campaigns touch every patient before and after a visit. Text and app-based tools reduce phone traffic and no-shows, which gives providers a clear financial return. Health systems also use two-way messaging for intake forms, test results and billing questions, replacing mailed letters and busy call centers. Strong demand comes from large networks that need to reach thousands of patients across many sites with consistent messages and from practices that want to fill open appointment slots quickly. Providers also use these campaigns to promote screenings and vaccinations.
Care coordination and navigation is the fastest-growing application as patients struggle to move between primary care, specialists, imaging and pharmacy services. Navigation tools guide patients to the right site, show wait times and handle referrals and follow-up, which improves the continuity of care. Health systems that serve patients with chronic conditions value these tools because missed handoffs lead to readmissions and poor ratings. Artificial intelligence adds the ability to match patients with suitable clinicians and to flag people who need extra support after discharge. These features are increasingly packaged with scheduling and intake products.
⮞In November 2025, Luma Health acquired Tonic Health from R1, extending its reach to more than 1,000 health systems. The acquisition adds digital intake and forms to a patient access platform.
By Deployment, Cloud Dominates the Patient Experience Technology Market and Is Also the Fastest Growing
Cloud deployment leads and is also growing fastest because providers want faster launches, automatic updates and the ability to scale during seasonal demand. Software-as-a-service platforms for portals, surveys and messaging need little local hardware, and vendors can add new features, such as AI assistants, across all customers at once. Smaller clinics and community hospitals with limited information technology staff find the lower upfront cost attractive. Security certifications and healthcare-specific hosting agreements have reduced earlier concerns about storing patient information outside the hospital, supporting migration from local servers. Vendors are also adding regional hosting options to meet national data rules.
On-premise and hybrid deployments remain in use where hospitals operate older systems or face strict data residency rules. Large academic medical centers often keep sensitive components on local servers while moving patient-facing apps to the cloud, which creates demand for hybrid designs. Integration with bedside devices, nurse call systems and room screens can also require local connections. Vendors that offer flexible deployment and clear migration paths are better placed to serve customers moving gradually to cloud services over the coming decade. Contracts often include a phased plan so that sensitive modules can move to the cloud at a later date.
⮞The final rule from the Office of the Assistant Secretary for Technology Policy on certification criteria took effect on October 1, 2025. The rule sets standards for electronic prior authorization and prescription benefit tools used by patient-facing applications.
By End User, Hospitals and Health Systems Dominates the Patient Experience Technology Market and Home Healthcare Providers Grows Fastest
Hospitals and health systems account for the largest share because they face formal patient experience measurement, large patient volumes and complex journeys across many departments. Public rating programs and payment adjustments tied to patient feedback give boards a strong reason to invest in survey platforms, digital front doors and bedside engagement. Inpatient units use room screens and tablets to show care plans, teach patients about discharge and collect feedback before they leave, making hospitals the main buyers of the broadest platforms. Many systems also run patient advisory councils that shape which tools they buy.
Home healthcare providers are growing fastest as care shifts out of hospitals and agencies need ways to stay in contact with patients and families. Remote check-ins, visit tracking, secure messaging and satisfaction surveys help agencies keep patients engaged without staff travel. Aging populations in North America, Europe and Japan increase demand for care at home, and payers support it as a lower-cost alternative to facility stays. Smaller agencies prefer simple, mobile-first tools that are quick to launch and easy for older patients and caregivers to use. Reimbursement rules for remote monitoring and home visits further encourage this adoption.
⮞In May 2026, Oneview Healthcare announced a bedside hub channel to power Epic MyChart Bedside TV. The offering links in-room screens with the hospital portal that patients already use.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
83.18 |
|
Europe |
United Kingdom |
27.91 |
|
Asia Pacific |
China |
30.27 |
|
Latin America |
Brazil |
48.72 |
|
Middle East & Africa |
Saudi Arabia |
33.41 |
North America Patient Experience Technology Market Insights
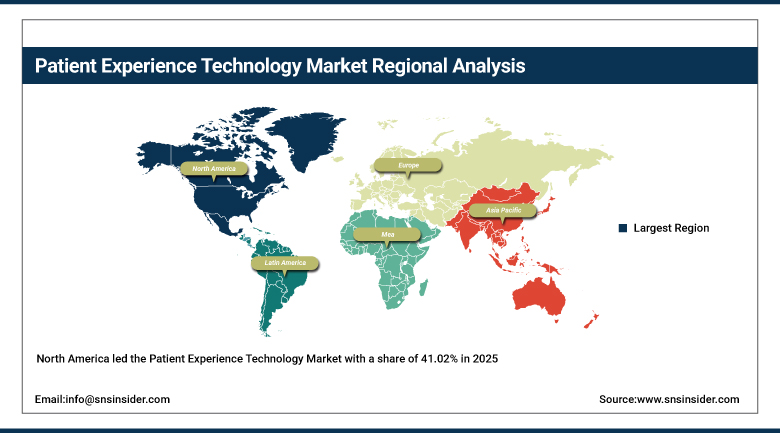
North America led the Patient Experience Technology Market with a share of 41.02% in 2025,, supported by early portal adoption, federal patient survey programs and a large base of technology vendors. Health systems in the United States are measured on patient ratings that affect payment, and large electronic health record vendors bundle portals, messaging and AI assistants for their customers. Specialist companies for patient access, intake, payments and surveys compete for the remaining budget, and venture funding and acquisitions continue to reshape the supplier base.
Canada contributes through provincial portals and a growing public appetite for digital access to records. Provincial health authorities are connecting laboratory, imaging and pharmacy data to patient-facing apps, while hospital networks add online booking and virtual visit tools. Differences between provinces in funding and systems slow the pace of national consistency, yet patient demand is clear, and vendors serving both countries find opportunities to reuse products with local adjustments to language and privacy rules. Cross-border vendors also benefit from similar patient expectations.
⮞For example, the 2024 Canadian Digital Health Survey, released in May 2025 by Canada Health Infoway, found that 47% of Canadians accessed their health information online, up from 39% in 2023. The rise confirms growing patient readiness for digital tools.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Patient Experience Technology Market Insights
Europe is a large and policy-driven region in which the United Kingdom, Germany and France lead spending. National health services are building shared apps and records, and funding is directed to tools that cut waiting times and give patients one place to manage appointments, prescriptions and results. Privacy rules under the General Data Protection Regulation shape product design, and vendors invest in local hosting and consent features. Large public and private hospital groups in Spain and Italy are adding online booking and digital payment options as well.
Germany now offers an electronic patient record to all people with statutory insurance, and the European Health Data Space is setting common rules for how records are shared. The Nordic countries have long used national portals, and southern European regions are adding digital front doors to reduce crowding in clinics. Procurement is often tender-based and slow, which favors established suppliers, although smaller specialists succeed in niches such as bedside engagement and patient feedback. Spain and Italy are expanding regional portals, and Poland has built a national patient account that is widening digital service use across the country.
⮞In December 2025, NHS England reported that its NHS App had more than 39 million registered users. The scale of the app makes it a central channel for patient access across England.
Asia Pacific Patient Experience Technology Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 14.35% during 2026-2035, as governments build national digital health platforms and private hospital groups compete on patient service. Smartphone use is high, and super-app style services let patients book, pay and message providers in a single place. Medical tourism hubs in Singapore, Thailand and India invest in service quality, and international accreditation standards encourage formal patient feedback programs. Private hospital groups in Southeast Asia are also investing in digital front doors as their middle classes grow.
China has large internet hospital platforms, Japan and South Korea are modernizing records for aging populations, and India is expanding digital health accounts under a national mission. Australia has a mature national record that supports patient access through apps. The region is diverse in language and regulation, so vendors work with local partners, and mobile messaging channels differ by country, which requires adaptation of communication tools. Government programs in India and Indonesia are widening the base of connected patients in smaller cities as well.
⮞In November 2025, the Australian Digital Health Agency reported more than 24.6 million active My Health Records. The volume of records shows the base on which patient-facing applications can be built.
MEA & Latin America Patient Experience Technology Market Insights
In the Middle East and Africa, Gulf states are the main source of demand. Saudi Arabia and the United Arab Emirates invest in national health apps, virtual hospitals and hospital experience programs under modernization plans, and international hospital brands set high service expectations. South Africa and Egypt are building private hospital networks that adopt portals and messaging, though funding limits and uneven connectivity slow adoption elsewhere in Africa. Private hospital groups in the Gulf also run patient experience programs tied to international accreditation.
⮞In June 2026, the Saudi Ministry of Health reported that its Sehhaty app had more than 31 million beneficiaries. The figure shows how national apps are becoming the front door to public care in the Gulf.
In Latin America, Brazil is the largest market, where the public system has built a national app and private hospital groups focus on patient satisfaction to attract insured members. Mexico, Colombia, Chile and Argentina add demand through private hospital chains and digital booking services. Currency swings and limited public funding restrain large projects, but mobile-first design suits a region where smartphones are the main way to access the internet. Private insurers and hospital groups in the region also support apps that help members book care and rate providers, which broadens the customer base for local vendors.
⮞For instance, Brazil's Ministry of Health said in September 2025 that Meu SUS Digital had 29 million monthly active users. The user base shows demand for public digital front doors in Latin America.
Market Dynamics
Growth Drivers: Digital Access Demand, Value-Based Payment and AI Assistants Drive Growth in the Patient Experience Technology Market
Patients expect to book, pay and communicate with providers through apps and text messages, and health systems that fail to offer these options risk losing them to competitors. Digital access also lowers costs, as automated reminders and self-service intake reduce missed appointments and call-center volumes. Federal and state programs that link payment to patient experience scores give executives a direct financial reason to invest in survey, feedback and service recovery tools. Younger patients are particularly likely to switch providers over poor digital access, and this is shifting how executives think about retention and the long-term value of each patient relationship.
Artificial intelligence adds a further driver. Virtual assistants answer common questions, summarize messages for staff and guide patients to appropriate services around the clock, which eases workforce shortages. Interoperability rules that require easier access to health information expand the data available to patient apps. Together these changes move patient experience spending from a quality department project to a core part of health system technology strategy and long-term capital plans. Vendor roadmaps are therefore increasingly aligned with these priorities. Health systems also report that better digital access reduces front-desk workload and improves staff satisfaction.
⮞For instance, Germany made its electronic patient record available to all statutory insured people, about 73 million, from April 2025. The nationwide rollout creates a common base for patient-facing services.
Restraints: Integration Costs, Data Privacy Rules and Limited Budgets Restrain Growth in the Patient Experience Technology Market
Integration with fragmented clinical systems is expensive and slow. Hospitals often run several electronic health record instances, scheduling tools and legacy survey systems, and connecting them to new patient applications requires interface work and testing. Smaller and community hospitals have limited information technology staff and capital budgets, so projects are delayed or scaled down, and some providers struggle to show a clear return on spending on experience tools. Vendors reduce this burden with prebuilt connectors, but customization needs still extend project timelines.
Data privacy, consent and cybersecurity add further cost. Patient messaging platforms handle sensitive information, and breaches or misuse can damage trust and bring penalties, so providers perform detailed security reviews that lengthen sales cycles. Staff resistance is another factor, since clinicians and front-desk teams may view new tools as extra work. Without strong training and workflow redesign, adoption stays low and the benefits promised by vendors are not achieved. These steps add time and cost to every deployment, especially in smaller organizations.
⮞The European Health Data Space Regulation entered into force in March 2025, with primary-use rules applying from March 2029. The phased timetable sets compliance work for vendors and providers over several years.
Opportunities: Home-Based Care, Emerging Markets and Experience Analytics Create Opportunities in the Patient Experience Technology Market
The move of care to the home and to outpatient settings opens a large opportunity for tools that keep patients engaged outside hospitals. Remote check-ins, virtual waiting rooms, education content and satisfaction surveys can be delivered by mobile devices, and agencies and clinics that previously used paper and phone calls are now buying their first digital platforms. Vendors that offer simple, mobile-first designs with strong language support can reach these customers at scale. Providers in rural areas could gain access to specialist services through such platforms.
Emerging markets in Asia Pacific, the Middle East and Latin America provide additional growth as governments and private hospital groups invest in service quality. Analytics that link patient comments to operational data, such as staffing and wait times, let leaders see why scores change and act quickly. Providers that can demonstrate improvements in loyalty, referrals and ratings will find it easier to justify further investment in patient experience technology. The combination of growing demand and low current penetration makes these regions a priority for vendors.
⮞In May 2026, Healthgrades reported that 373 of the 3,020 hospitals it evaluated earned its 2026 Outstanding Patient Experience Award. Public recognition programs of this kind encourage hospitals to invest in the tools that raise patient ratings.
Recent Developments:
-
In September 2025, Phreesia agreed to acquire AccessOne, a provider of consumer payment products, for USD 160 million in cash. The acquisition adds payment financing options to the intake, check-in and scheduling tools that Phreesia already offers to health systems and practices.
-
In September 2025, RevSpring entered into a definitive agreement to acquire Kyruus Health, a provider of provider search and scheduling technology. The combination links patient engagement and payments with search and scheduling, giving health systems a more complete patient journey platform.
-
In October 2026, Experian Health acquired eInsights, a company whose tools support reimbursement recovery for healthcare clients. The acquisition expands the patient access and financial clearance offering that Experian Health provides to hospitals and physician groups.
-
In August 2026, Uniguest introduced Hub IPS 26.3 for patient-room engagement, adding integrations with Baxter real-time location systems and CBORD NetMenu. The update connects room screens with location and meal ordering data to make the patient stay easier to manage.
Patient Experience Technology Market Key Players
-
Press Ganey Forsta
-
Qualtrics International Inc.
-
Medallia, Inc.
-
NRC Health
-
Epic Systems Corporation
-
Oracle Corporation (Oracle Health)
-
Phreesia, Inc.
-
Experian Health
-
RevSpring, Inc. (including Kyruus Health)
-
Luma Health, Inc.
-
Artera
-
Get Well Network, Inc.
-
CipherHealth
-
Relatient, Inc.
-
Solutionreach, Inc.
-
Oneview Healthcare
-
Sogolytics
-
Uniguest
Patient Experience Technology Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 683.41 Million |
| Market Size by 2035 | USD 2.14 Billion |
| CAGR | CAGR of 12.09% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software and Platforms and Services) • By Application (Patient Communication and Engagement, Appointment Scheduling and Access Management, Patient Satisfaction Measurement, Care Coordination and Navigation, and Other Applications) • By Deployment (Cloud, On-Premise, and Hybrid) • By End User (Hospitals and Health Systems, Clinics and Physician Practices, Home Healthcare Providers, Payers, and Other End Users) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Press Ganey Forsta, Qualtrics International Inc., Medallia, Inc., NRC Health, Epic Systems Corporation, Oracle Corporation (Oracle Health), Phreesia, Inc., Experian Health, RevSpring, Inc. (including Kyruus Health), Luma Health, Inc., Artera, Get Well Network, Inc., CipherHealth, Relatient, Inc., Solutionreach, Inc., Oneview Healthcare, Sogolytics, Uniguest |

Frequently Asked Questions
Some of the major companies operating in the Patient Experience Technology Market include Press Ganey Forsta, Qualtrics, Medallia, NRC Health, Epic Systems, Oracle Health, Phreesia, Experian Health, RevSpring, Luma Health, Artera, Get Well Network, CipherHealth, Relatient, Solutionreach, Oneview Healthcare, Sogolytics and Uniguest.
Key opportunities include tools for home-based and outpatient care, mobile-first platforms for emerging markets in Asia Pacific, the Middle East and Latin America, and analytics that connect patient feedback with operational data.
Patient demand for digital access, together with payment models that link reimbursement to patient experience scores, is the key growth factor for the market.
By Component, the Software and Platforms segment dominated the Patient Experience Technology Market with approximately 57.20% share in 2025, because portals, survey systems and communication tools form the base of every patient experience program.
North America dominated the Patient Experience Technology Market with a share of 41.02% in 2025, supported by early portal adoption, federal patient survey programs and a large base of technology vendors.
