
Women's Health Diagnostics Market Report Scope & Overview:
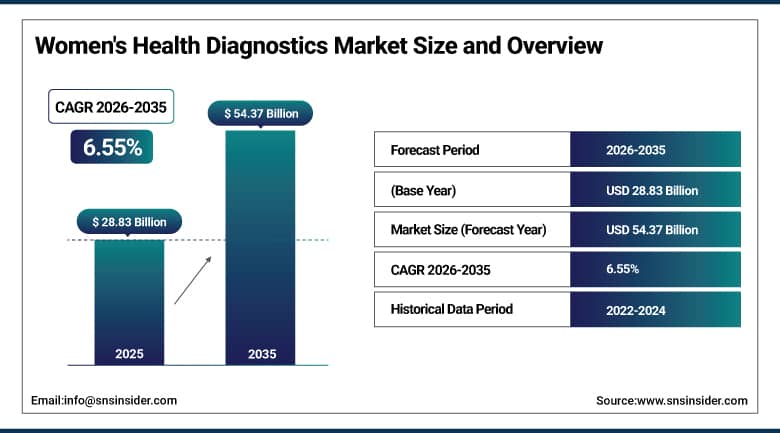
The Women's Health Diagnostics Market was valued at USD 28.83 Billion in 2025 and is expected to reach USD 54.37 Billion by 2035, growing at a CAGR of 6.55% from 2026-2035.
The Women's Health Diagnostics Market covers tests, devices, and genetic panels used to screen, diagnose, and monitor conditions that affect women, including breast and cervical cancer, pregnancy and fertility, and infections. Screening programs, rising awareness, and aging populations support volumes. Molecular tests for human papillomavirus, noninvasive prenatal tests, and digital mammography with artificial intelligence are expanding clinical options. Self-collection kits are bringing screening to women who skip clinic visits. Public programs in many countries now set national screening targets, and laboratories invest in high throughput platforms. Competition among global diagnostics firms and specialist startups keeps innovation active.
⮞In July 2026, the World Health Organization reported around 604,000 new cervical cancer cases and around 280,000 deaths in 2024. A burden of this size keeps cervical screening and vaccination high on health agendas.
To Get More Information On Women's Health Diagnostics Market - Request Free Sample Report
Women's Health Diagnostics Market Trends:
-
Self-collection HPV tests that bring cervical screening to the home
-
Noninvasive prenatal testing with lower no-call rates
-
Artificial intelligence support for mammography reading
-
Multi-cancer early detection blood tests under regulatory review
-
National screening targets driving organized programs
U.S. Women's Health Diagnostics Market Outlook:
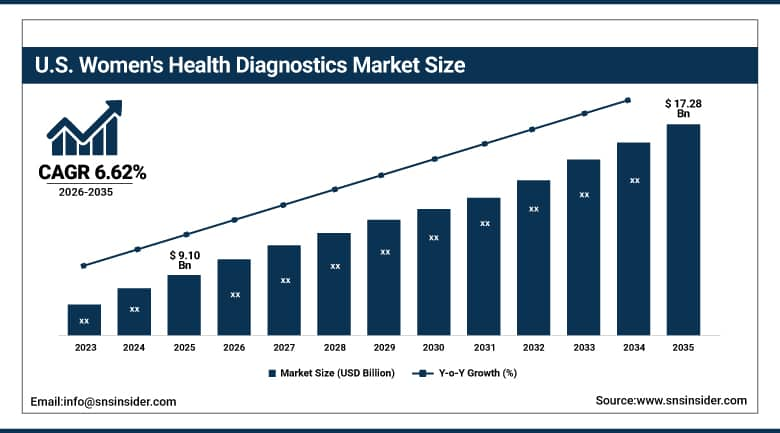
The U.S. Women's Health Diagnostics Market was valued at USD 9.10 Billion in 2025 and is expected to reach USD 17.28 Billion by 2035, growing at a CAGR of 6.62% from 2026-2035.
The U.S. Women's Health Diagnostics Market is supported by organized screening guidelines, broad insurance coverage for preventive tests, and a large installed base of mammography and molecular platforms. Large laboratory networks and hospital systems process millions of Pap, HPV, and prenatal tests each year. The Food and Drug Administration has approved self-collection devices and new genotyping assays in recent years. Breast density notification rules have increased supplemental imaging. Consumer brands and telehealth firms add direct to consumer options. Competition among manufacturers and laboratories keeps adoption of new technology brisk. Employers also fund preventive screening benefits that raise participation.
⮞In June 2026, the American Cancer Society estimated about 321,910 new invasive breast cancer cases and about 42,140 breast cancer deaths among U.S. women in 2026. Incidence on this scale underpins steady screening and diagnostic demand.
Women's Health Diagnostics Market Segment Analysis:
-
By Product, the Diagnostic Tests segment dominated the Women's Health Diagnostics Market with approximately 54.21% share in 2025, while the Genetic and Genomic Panels segment is the fastest growing with a CAGR of approximately 9.32%.
-
By Technology, the Immunoassays segment dominated the Women's Health Diagnostics Market with approximately 32.08% share in 2025, while the AI-Enabled Analytics segment is the fastest growing with a CAGR of approximately 8.44%.
-
By Application, the Breast Cancer Testing segment dominated the Women's Health Diagnostics Market with approximately 41.30% share in 2025, while the Prenatal and Fertility Testing segment is the fastest growing with a CAGR of approximately 8.96%.
-
By End User, the Hospitals and Diagnostic Centers segment dominated the Women's Health Diagnostics Market with approximately 69.05% share in 2025, while the Home Care segment is the fastest growing with a CAGR of approximately 11.17%.
By Product, Diagnostic Tests Dominates the Women's Health Diagnostics Market and Genetic and Genomic Panels Grows Fastest
Diagnostic testing is dominant due to the high frequency and large volume of requests in screening and monitoring programs. Regular tests include Pap smear and HPV, pregnancy and hormonal tests, infectious disease panels, and tumor markers. There is a high turnover of reagents and consumables for diagnostic companies and high-volume automation in laboratories. Insurance reimbursement is available in many countries for preventive testing. New test menu items are possible on the same equipment, and therefore the price of implementation is lower. Automation in reference laboratories makes per-test costs relatively low.
Tests in the genetic and genomic panels are becoming increasingly popular because of the decreasing cost of sequencing and evidence from the clinic. Non-invasive prenatal screening tests can diagnose chromosomal abnormalities from the blood sample of the mother, and hereditary cancer panels identify women predisposed to breast and ovarian cancer. Screening for carriers and multi-cancer early detection panels are also developed. Diagnostic devices like imaging systems and ovulation monitoring are still important but develop more slowly. Payer decisions and genetic counseling affect the rate of introduction of new panels into practice. Networks of genetic counselors are developing together with increasing numbers of tests.
⮞In October 2024, Quest Diagnostics introduced specimen self-collection with the Aptima Multi-test swab at about 2,000 patient service centers, noting that vaginitis affects 1 in 3 women in their lifetime. Convenient collection widens access to tests for common infections.
By Technology, Immunoassays Dominates the Women's Health Diagnostics Market and AI-Enabled Analytics Grows Fastest
Immunoassays lead because they power pregnancy, fertility hormone, thyroid, and tumor marker testing on automated analyzers. Laboratories value their speed, wide menu, and proven performance. Instrument makers offer integrated systems that run hundreds of samples per hour, and reagent rental contracts lock in long term supply. Point of care formats such as home pregnancy and ovulation strips extend the technology to consumers. Molecular diagnostics, imaging, and sequencing hold the other large shares and grow in parallel. Standardized calibrators allow results to be compared across laboratories and over time.
Artificial intelligence enabled analytics are growing fastest as software begins to support image reading, risk scoring, and pathology review. Algorithms help radiologists flag suspicious findings on mammograms, and they help cytologists review cervical slides. Risk models combine age, density, family history, and genetics to guide screening intervals. Molecular diagnostics also grow steadily because HPV genotyping and infection panels replace older methods. Vendors that combine instruments with software and cloud reporting build sticky relationships with laboratories and imaging centers. Regulatory clearance of such software is growing, which builds clinician trust.
By Application, Breast Cancer Testing Dominates the Women's Health Diagnostics Market and Prenatal and Fertility Testing Grows Fastest
Breast cancer testing leads because it is the most common cancer among women in many countries and is covered by organized screening programs. Mammography, ultrasound, magnetic resonance imaging, biopsy, and genetic risk testing together generate large procedure volumes. Breast density notification has increased supplemental imaging, and hereditary cancer panels are widely used. Tumor marker and companion diagnostic tests guide treatment after diagnosis. Pharmaceutical advances in targeted therapy increase the number of molecular tests per patient. Supplemental ultrasound and magnetic resonance imaging add procedure volume for women with dense tissue.
Prenatal and fertility testing is growing faster as couples delay childbearing and seek more information about pregnancy risks. Noninvasive prenatal tests have become routine in many markets, and manufacturers continue to improve accuracy at low fetal fraction. Fertility clinics use hormone assays, genetic screening, and ovulation monitoring. Cervical cancer testing and infectious disease testing complete the major applications, supported by HPV self-collection and sexually transmitted infection panels. Osteoporosis and menopause related assays add smaller demand. Reimbursement and consumer awareness shape the pace of growth in each application. Employer benefits for fertility care are also widening the patient pool.
⮞In September 2026, the FDA released materials for an advisory panel on the Galleri multi-cancer blood test, showing 12-month sensitivity of 35.0% in one study and 31.6% in another. The review shows the evidence bar facing blood based early detection tests.
By End User, Hospitals and Diagnostic Centers Dominates the Women's Health Diagnostics Market and Home Care Grows Fastest
Hospitals and diagnostic centers lead because they hold imaging suites, laboratories, and specialist staff needed to run most women's health tests. Breast imaging, biopsy, prenatal ultrasound, and cervical cytology are performed in these settings. Large health systems negotiate supplier contracts that cover instruments and consumables across many sites. Referral networks route women from primary care to specialist centers. Accreditation and quality programs add confidence in results and support steady demand for established suppliers. Bundled service contracts add stability to demand from these institutions.
Home care is growing fastest as self-testing and self-collection make screening easier. Pregnancy, ovulation, and menopause tests are already common, and cervical screening kits that women collect themselves are now approved in the United States. Telehealth platforms mail kits, collect results, and arrange follow up. Women who face travel barriers, privacy concerns, or discomfort with pelvic exams are early adopters. Laboratories partner with consumer brands to process mailed samples. Clinics benefit because outreach through home kits can bring under screened women back into care. Mailed kits also lower the cost of reaching women in rural communities.
⮞In May 2024, Roche announced FDA approval of a self-collection solution for its cobas HPV test, which detects 14 high-risk genotypes including HPV 16 and 18. The approval moved cervical screening toward settings outside the clinic.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.57% |
|
Europe |
Germany |
26.78% |
|
Asia Pacific |
China |
40.60% |
|
Latin America |
Brazil |
48.12% |
|
Middle East & Africa |
Saudi Arabia |
33.45% |
North America Women's Health Diagnostics Market Insights
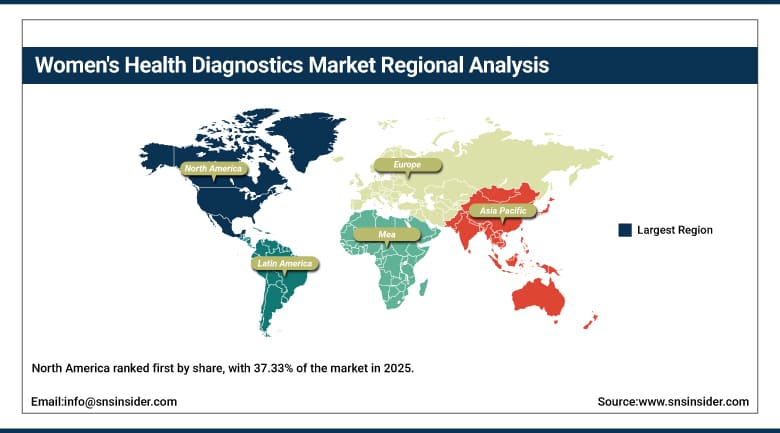
North America ranked first by share, with 37.33% of the market in 2025, supported by organized screening, broad insurance coverage for preventive tests, and fast adoption of new technology. The United States generates most regional demand, and Canada adds activity through provincial programs that are moving to HPV primary screening. Large laboratory networks and hospital systems operate high throughput molecular and imaging platforms. Direct to consumer brands and telehealth companies add new channels for sample collection and result delivery. Community health centers play an important role in reaching low-income women.
Regulatory activity keeps the pipeline full. Recent approvals include self-collection devices for cervical screening, extended HPV genotyping assays, and enhanced prenatal tests. Ownership changes among diagnostics companies are reshaping competition, and private equity interest is rising. Gaps remain among uninsured and rural women, which public programs and community clinics try to close. Payers are reviewing coverage for new multi-cancer tests and genomic panels. Providers also invest in artificial intelligence for mammography to manage workforce shortages in breast imaging. Professional societies update guidelines regularly, which prompts laboratories to change test menus.
⮞In January 2026, the Canadian Partnership Against Cancer reported that cervical cancer caused nearly 430 deaths in Canada in 2025, and set a goal of elimination by 2040. The target requires HPV primary screening in every province and territory.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Women's Health Diagnostics Market Insights
Europe holds the second largest position, led by Germany, the United Kingdom, France, Italy, and Spain. National health systems run organized breast and cervical screening programs, and a shift toward HPV primary testing is under way. Public procurement favors suppliers with strong evidence and reliable service. Strict in vitro diagnostic regulation raises the documentation burden for manufacturers. Aging populations and rising awareness of hereditary cancer risk support demand for genetic testing. Regional screening registries help programs track participation and quality.
Funding of prenatal screening is common practice in the north and west of Europe. The fertility treatment market in Spain, Italy, and the Nordic countries has hormone and genetic tests. Cross-border coordination for cancer plans contributes to developing common standards. The budgetary constraints of southern and eastern European countries hinder the implementation of premium platforms; however, regional funding initiatives help develop the lab infrastructure. Local producers fight with international providers of immunoassays and ultrasound. AI pilot programs are in operation in some national breast screening programs. Societies for specialists develop guidelines which influence the choice of tests.
⮞In December 2022, the Council of the European Union recommended that 90% of eligible people be offered breast, cervical, and colorectal screening by 2025. The recommendation set a common ambition for organized programs across member states.
Asia Pacific Women's Health Diagnostics Market Insights
The fastest growing geographical area is Asia Pacific with its projected CAGR of 9.82% in 2026-2035 owing to China, India, Japan, Australia, and South Korea. The governments are encouraging cervical and breast screening programs along with HPV vaccinations and laboratory facilities. Rising incomes, urbanization, and increased awareness about women's healthcare issues are contributing to rising tests. Immunoassay and HPV kits are available locally at reduced prices. Multinationals are collaborating with regional distributors. Hospital groups in India and Southeast Asia offer molecular and imaging test services. Several countries employ mobile screening vans in distant areas.
There has been rapid growth in prenatal testing in China, South Korea, and Singapore and in fertility clinics throughout the region. Japan and Australia are focused on advanced imaging and artificial intelligence for breast screening. Insurance coverage by governments is increasing, which helps in increasing screening among women. Primary care provider training and campaigns for increased awareness are necessary for screening. There is the provision of at-home kits on e-commerce websites. Harmonization of regulations helps manufacturers in registering products in several countries. Genetic counselors are needed with the rise in testing volume.
⮞In March 2026, India's health ministry told Parliament that 8.73 crore women had been screened for cervical cancer. A screening base of this size shows the scale of public programs now under way.
MEA & Latin America Women's Health Diagnostics Market Insights
Latin America is growing in strength with Brazil and Mexico implementing more government and private testing facilities. Mexico falls under this region from the perspective of markets, and social security bodies carry out cancer screening and vaccination drives there. In some instances, molecular HPV testing is being used to replace cytology tests, which is encouraged by the local health authorities. Fluctuations in currency and budget restrictions hamper the purchase of expensive devices, hence the need for low cost test kits and distributors. Demand is being boosted by Argentina, Chile and Colombia through hospital upgrades.
⮞In August 2025, the Pan American Health Organization reported that Brazil began rolling out a DNA-HPV test detecting 14 genotypes in 12 states. The rollout shows public programs shifting toward molecular screening.
In Middle East and African countries, there have been developments related to governmental investment in the health care sector, particularly in countries like Saudi Arabia, the United Arab Emirates, and South Africa. Breast cancer screening programs in these countries include mammograms and screenings at clinics. In Africa, cervical cancer screening includes expansion by using public clinics and donations, with shortages of laboratory equipment being a problem. Genetic and prenatal screenings are conducted in private hospitals in the Gulf area using advanced techniques. Distribution companies and international collaborations provide most of the supplies, while training improves the quality.
⮞In August 2026, the Gauteng health department reported that cervical screenings rose 29%, from 153,703 women in 2024/25 to 198,611 in 2025/26. Growth of this kind shows how public campaigns can lift testing volumes.
Market Dynamics:
Growth Drivers: National Screening Programs and Technology Advances Drive Growth in the Women's Health Diagnostics Market
National screening programs are a central driver. Governments set targets for cervical, breast, and prenatal screening and fund organized invitation systems. HPV vaccination and primary HPV testing form part of elimination strategies in several countries. Higher participation brings more samples to laboratories and more women to imaging centers. Public awareness campaigns encourage earlier consultation, and employers and insurers promote preventive checks. These programs create predictable demand that lasts through the forecast period. Invitation and reminder systems have proven effective in raising attendance.
Technology advances add momentum. Self-collection devices, extended genotyping, noninvasive prenatal tests, and artificial intelligence for imaging improve accuracy and convenience. Automation lets laboratories process more samples with fewer staff. Digital platforms link test ordering, result delivery, and follow up. Falling sequencing costs make genomic panels more affordable. Each new capability expands the group of women who can be tested and widens the menu available to clinicians. Together these forces support growth through 2035. Smaller, cheaper instruments are reaching community hospitals that lacked them.
⮞In March 2025, China's disease control center reported that 51.5% of women aged 35 to 64 had been screened for cervical cancer in 2023-24, against a 2030 target of 70%. Gaps to targets of this kind point to years of program expansion.
Restraints: Access Gaps and Regulatory and Reimbursement Hurdles Restrain Growth in the Women's Health Diagnostics Market
Access issues prevent engagement. Rural women, uninsured women, and women who have cost or cultural barriers to access are under-screened. Lack of radiologists, pathologists, and lab technicians causes delays in reporting results. The follow-up after an abnormal test result is not always thorough, making the effectiveness of the screening process questionable. In low-income countries, lack of laboratory facilities prevents molecular testing. Such barriers limit test volumes even in the presence of these tests. Transportation costs and taking time off work are typical challenges that women have to overcome.
Legal and payer issues also hinder the development of the market. Tests like multi-cancer blood panel tests or genetic screening require good evidence prior to their approval and payer acceptance. Insurance companies limit reimbursement to certain categories of patients, decreasing uptake. Compliance with privacy requirements related to the handling of genetic data is costly, and these requirements vary depending on a country. Some screening technologies lead to unnecessary stress and false positive results. Competitive pricing for public tenders limits profit margins for suppliers. Reimbursement of self-sampling and telemedicine is inconsistent.
⮞In June 2026, a study reported by Contemporary OB/GYN estimated that 17.9 million U.S. women aged 45 to 64 were overdue for at least one cancer screening. Large overdue groups show how access and cost still hold back testing.
Opportunities: Home Self-Collection and Early Detection Technologies Create Opportunities in the Women's Health Diagnostics Market
Home self-collection offers a large opportunity. Many women skip screening because of time, discomfort, or access, and a mailed kit removes those barriers. Cervical screening kits are now cleared in the United States, and the model can extend to sexually transmitted infections, fertility, and menopause hormones. Telehealth and laboratory partnerships can manage ordering, shipping, and results. Companies that integrate follow up care can build loyal customer bases. Health plans and employers have reasons to support kits that bring under screened women into care. Clear instructions and customer support are key to reliable sample quality.
The development of early detection technology is the next opportunity area. Blood-based multi-cancer screenings, polygenic risk scores, and the application of artificial intelligence for imaging might alter the pathway of screening if proven through data. There is a need for cheap solutions for HPV screening and breast screening for emerging markets. The addition of companion diagnostics that complement targeted therapy would be valuable. The partnership between device companies and software companies and health systems might create packaged solutions. The early adopters who will be able to obtain regulatory clearance and reimbursement might have a sustainable competitive advantage as physicians become accustomed to the use of new technology.
Recent Developments:
-
In April 2026, Hologic completed its acquisition by Blackstone and TPG at up to USD 79 per share, which includes USD 76 in cash and a contingent value right of up to USD 3.
-
In April 2026, BD announced clearance of its Onclarity HPV Self-Collection Kit with extended genotyping for at-home use.
-
In May 2026, Natera launched an enhanced Panorama noninvasive prenatal test with a no-call rate reduced to 0.5%.
-
In May 2025, Teal Health received FDA approval for the Teal Wand, the first at-home device for cervical cancer screening.
Women's Health Diagnostics Market Key Players are:
-
Hologic
-
Roche
-
Abbott
-
Becton Dickinson
-
Siemens Healthineers
-
bioMérieux
-
Quest Diagnostics
-
Thermo Fisher Scientific
-
GE HealthCare
-
Philips
-
Cepheid (Danaher)
-
PerkinElmer
-
Aspira Women's Health
-
Everlywell
-
Natera
-
Teal Health
Women's Health Diagnostics Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 28.83 Billion |
| Market Size by 2035 | USD 54.37 Billion |
| CAGR | CAGR of 6.55% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Diagnostic Tests, Diagnostic Devices, and Genetic and Genomic Panels) • By Technology (Immunoassays, Molecular Diagnostics, Imaging, and AI-Enabled Analytics) • By Application (Breast Cancer Testing, Cervical Cancer Testing, Prenatal and Fertility Testing, and Infectious Disease Testing) • By End User (Hospitals and Diagnostic Centers, Home Care, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Hologic, Roche, Abbott, Becton Dickinson, Siemens Healthineers, bioMérieux, Quest Diagnostics, Thermo Fisher Scientific, GE HealthCare, Philips, Cepheid (Danaher), PerkinElmer, Aspira Women's Health, Everlywell, Natera, Teal Health |

Frequently Asked Questions
Key players in the market include Hologic, Roche, Abbott, Becton Dickinson, Siemens Healthineers, and Quest Diagnostics, among others.
Key opportunities include home self-collection kits and early detection technologies such as artificial intelligence imaging and multi-cancer blood tests.
National screening programs and technology advances such as self-collection and noninvasive prenatal testing are the major growth factors.
The Diagnostic Tests segment dominated the market in 2025 with approximately 54.21% share, as screening and monitoring programs generate recurring, high volume demand.
North America dominated the market in 2025 with approximately 37.33% share, supported by organized screening, broad insurance coverage for preventive tests, and fast adoption of new technology.
