
Surgical Drill Market Report Scope & Overview:
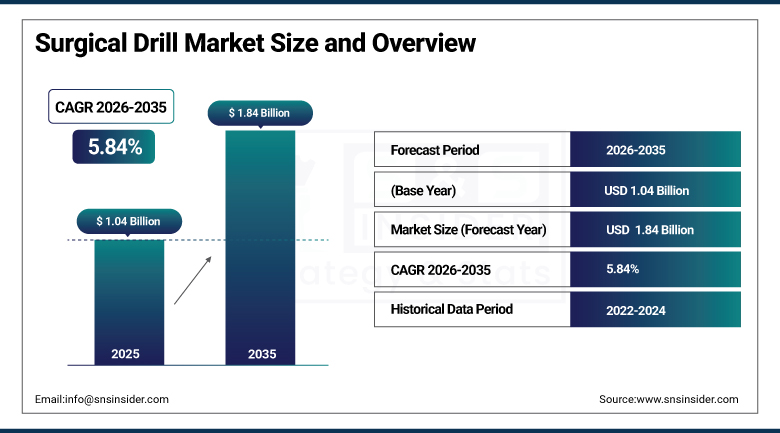
The Surgical Drill Market was valued at USD 1.04 Billion in 2025 and is expected to reach USD 1.84 Billion by 2035, growing at a CAGR of 5.84% from 2026-2035.
Surgical drills represent essential precision instruments across modern operating rooms, enabling controlled bone cutting, shaping, and hole preparation for implant fixation across orthopedic, neurosurgical, dental, and ENT procedures. The Surgical Drills Market is poised for substantial growth driven by technological advancements and increasing demand for minimally invasive procedures, with technological advancements enhancing the precision and efficiency of surgical drills particularly evident across major healthcare markets. Demand is powered by climbing surgical volumes, rapid improvements in battery chemistry, and the migration of procedures toward minimally invasive techniques that call for ever-tighter drilling tolerances, with hospitals increasingly shifting capital budgets from pneumatic lines to cordless systems because smart batteries cut turnover time between procedures while software-guided drilling continues improving surgical precision and patient outcomes. Rising demand for orthopedic surgeries, increasing investment in healthcare infrastructure, and the growing aging population continue serving as key structural drivers of sustained market growth, particularly as the number of joint replacement and spinal operations continues climbing across major global healthcare systems.
Stryker reported that over two-thirds of its U.S. knee surgeries and over one-third of its U.S. hip surgeries were performed using its MAKO robotic surgical system, which integrates precision-guided drilling and bone preparation technology, at year-end 2025. More than 50% of global knee implant procedures and over 20% of global hip implant procedures were performed using MAKO robotic systems by the same milestone, reflecting the accelerating integration of robotic guidance with surgical drilling technology as orthopedic surgeons increasingly favor robotically assisted bone preparation over traditional freehand drilling techniques for improved implant placement accuracy.
To Get more information On Surgical Drill Market - Request Free Sample Report
Surgical Drill Market Trends
-
Rising adoption of cordless, battery-powered surgical drills replacing traditional pneumatic drilling systems.
-
Growing integration of robotic guidance systems with surgical drilling for improved implant placement accuracy.
-
Expanding use of high-speed surgical drills supporting increasingly precise minimally invasive surgical techniques.
-
Increasing shift of orthopedic and dental procedures toward ambulatory surgery center settings.
-
Rising development of semi-autonomous and AI-navigated robotic drilling technology for orthopedic applications.
-
Growing manufacturer investment in smart battery chemistry reducing procedure turnover time in operating rooms.
U.S. Surgical Drill Market Outlook
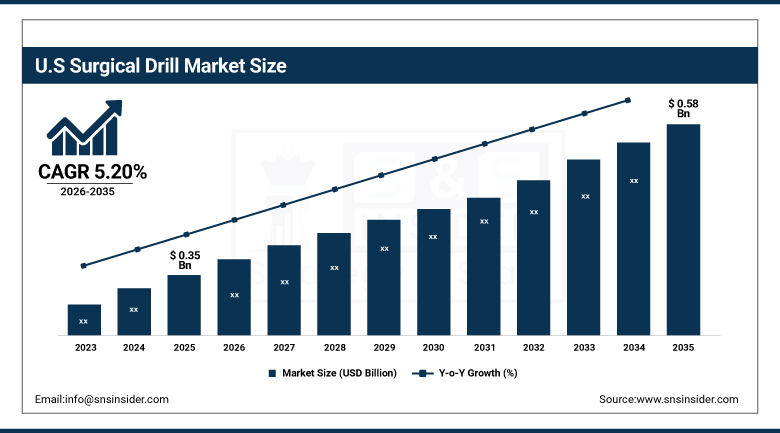
The U.S. Surgical Drill Market was valued at USD 0.35 Billion in 2025 and is expected to reach USD 0.58 Billion by 2035, growing at a CAGR of 5.20% from 2026-2035.
The U.S. Surgical Drill Market continues to benefit from sustained growth across the knee and hip implant markets, with worldwide knee procedures growing slightly faster as an increasing number of these procedures are performed using robotic systems that integrate precision drilling technology. Healthy patient volumes, growing ambulatory surgery center capacity, and hospitals continuing to manage capacity effectively are all expected to support continued strong performance across the domestic orthopedic procedure volume that anchors sustained surgical drill demand. The top four orthopedic companies continue to dominate the domestic knee and hip market with approximately 80% combined share, reflecting a highly concentrated competitive landscape where surgical drilling technology increasingly integrates with proprietary robotic and navigation platforms rather than functioning as standalone instrumentation.
Zimmer Biomet completed its acquisition of Monogram Technologies on October 7, 2025, an AI-driven, next-generation orthopedic robotics company whose surgeon-guided semi- and fully autonomous robotic drilling technologies are expected to add new and differentiated capabilities to Zimmer Biomet's broader suite of customer-centric technology solutions. The transaction sets Zimmer Biomet on a course to become the first orthopedic company to offer a fully autonomous robotic drilling solution, with the semi-autonomous version of Monogram's CT-based, AI-navigated total knee arthroplasty technology already having received FDA 510(k) clearance and expected to be commercialized with Zimmer Biomet implants by early 2027.
Surgical Drill Market Segment Analysis
-
By Product Type, the Electric Drills segment dominated the Surgical Drill Market with approximately 46.60% share in 2025, while the Battery-Powered Drills segment is the fastest growing with a CAGR of approximately 7.20%.
-
By Speed, the High-Speed segment dominated the Surgical Drill Market with approximately 59.60% share in 2025, and is also the fastest growing with a CAGR of approximately 6.20%.
-
By Application, the Orthopedic Surgeries segment dominated the Surgical Drill Market with approximately 64.60% share in 2025, while the Neurosurgery segment is the fastest growing with a CAGR of approximately 6.80%.
-
By End User, the Hospitals & Clinics segment dominated the Surgical Drill Market with approximately 67.60% share in 2025, while the Ambulatory Surgery Centers segment is the fastest growing with a CAGR of approximately 7.00%.
By Product Type, Electric Drills Dominates the Surgical Drill Market and Battery-Powered Drills Grows Fastest
Electric drills hold the largest share of the market, benefiting from established manufacturing infrastructure, reliable power delivery, and broad compatibility across the wide range of surgical procedures that continue to rely on this proven drilling technology. Electric drill systems continue to offer surgeons consistent, predictable torque and speed control across extended procedures, a reliability that continues to make this technology the default choice across the majority of hospital operating room inventories despite growing interest in newer cordless alternatives.
Battery-powered drills represent the fastest-growing product type, as hospitals increasingly shift capital budgets from pneumatic lines to cordless systems because smart batteries cut turnover time between procedures, a genuine operational efficiency gain that continues to resonate strongly with hospital administrators managing increasingly tight operating room scheduling. Rapid improvements in battery chemistry continue to extend both the runtime and power delivery consistency of cordless surgical drilling systems, closing the performance gap that once favored corded electric and pneumatic alternatives, positioning battery-powered drills for sustained above-market growth as this technology continues maturing across an expanding range of surgical applications.
By Speed, High-Speed Dominates the Surgical Drill Market and Also Grows Fastest
High-speed surgical drills, operating above 60,000 revolutions per minute, command the largest share among speed categories, reflecting their essential role in precise bone cutting and shaping applications where slower rotation speeds would compromise both surgical precision and procedure efficiency. This category's dominance continues to be reinforced by the migration of procedures toward minimally invasive techniques that call for ever-tighter drilling tolerances, tolerances that high-speed drilling systems are specifically engineered to deliver reliably across demanding surgical applications.
High-speed drills are also the fastest-growing speed category, as continued technological advancement in motor design and thermal management continues to expand the range of procedures where high-speed drilling delivers genuine clinical advantage over standard-speed alternatives. As minimally invasive surgical technique adoption continues accelerating across orthopedic, neurosurgical, and dental applications alike, sustained demand for the precision that high-speed drilling delivers continues to reinforce this category's position as both the largest and fastest-growing segment within the broader surgical drill market.
By Application, Orthopedic Surgeries Dominates the Surgical Drill Market and Neurosurgery Grows Fastest
The orthopedic surgery segment has continued to be the largest end-use segment based on growing demand for orthopedic surgeries due to the increasing aging population across the globe and increased cases of sport related injuries and degenerative joint disease that necessitate orthopedic surgery. It is also expected to retain its dominance due to the large volume of joint replacements and spinal fusion surgeries carried out each year globally which involve significant bone preparation work which can be achieved through surgical drilling.
Neurosurgery represents the fastest-growing application segment, driven by rising cases of brain tumors and nervous system cancer that continue to give rise to an increasing number of neurovascular surgeries worldwide. With thousands of brain tumor cases reported annually across major global markets, and a substantial share of these cases requiring surgical intervention involving precise cranial bone access, sustained growth in neurosurgical procedure volume continues to drive above-market demand for the specialized, high-precision drilling technology these procedures require relative to the broader, orthopedic-dominated application market.
By End User, Hospitals & Clinics Dominates the Surgical Drill Market and Ambulatory Surgery Centers Grows Fastest
Hospitals and clinics command the largest end-user share, reflecting the complexity and resource requirements of most surgical drilling procedures, which typically demand comprehensive operating room infrastructure, anesthesia support, and post-operative recovery capability that hospital settings are best equipped to provide. The scale of hospital-based surgical volume across orthopedic, neurosurgical, and other major application areas continues to sustain hospitals and clinics' position as the largest source of surgical drill demand worldwide.
Ambulatory surgery centers represent the fastest-growing end-user segment, as growing ambulatory surgery center capacity continues to expand the range of procedures that can be safely and efficiently performed outside traditional hospital settings. Continued advancement in minimally invasive surgical technique, combined with improved anesthesia protocols and recovery management, continues to expand the range of orthopedic and other drilling-intensive procedures suitable for ambulatory surgery center delivery, positioning this end-user category for sustained above-market growth as healthcare systems worldwide continue prioritizing cost-effective, efficient surgical care delivery models.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Surgical Drill Market Insights
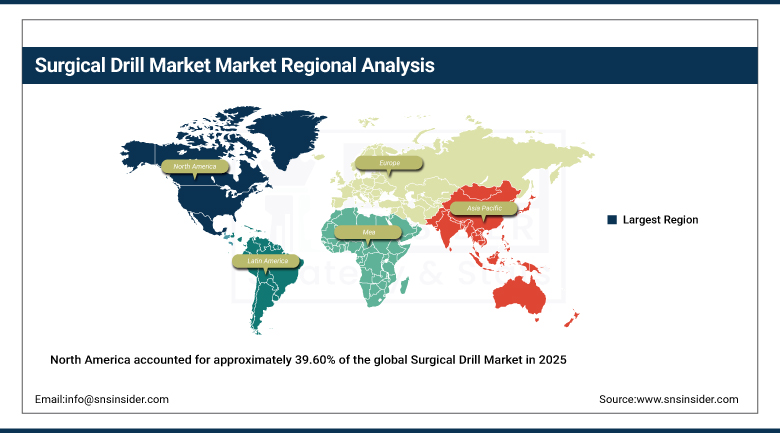
North America accounted for approximately 39.60% of the global Surgical Drill Market in 2025, making it the largest regional market, supported by advanced healthcare infrastructure, high adoption rates of robotic and minimally invasive surgical techniques, and a substantial concentration of leading surgical instrument manufacturers headquartered within the region. The region's sustained investment in technological advancement, particularly the integration of robotic guidance systems with surgical drilling technology, continues to reinforce North America's position as the largest and most technologically advanced surgical drill market globally.
Canada is contributing incremental regional demand as its own healthcare system continues investing in surgical technology modernization. Continued domestic investment in cordless drilling technology and robotic-assisted surgical platforms is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding Asia Pacific markets.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Surgical Drill Market Insights
Europe accounts for a considerable portion of the total Global Surgical Drill Market driven by the extensive production of medical devices in Germany and the established health care system of the region that enables a high number of surgeries. More than half of the 11,000 brain tumor cases reported in Europe per year are of the malignant nature and thus create constant demand for neurosurgical drill technology.
United Kingdom, France, and Italy are among the major contributors to regional demand as the health care systems of these countries continue to expand the use of the technology in orthopedic and neurosurgical procedures. Regional producers of medical devices keep developing robotic guidance technology and cordless drills to be on par with the global innovators.
Asia Pacific Surgical Drill Market Insights
Asia Pacific is the fastest-growing regional market, with the demand for minimally invasive procedures particularly propelling the adoption of surgical drills across the region's rapidly expanding healthcare infrastructure. China's substantial healthcare infrastructure investment and rapidly growing surgical volume continue to drive significant regional demand for both standard and advanced surgical drilling technology.
India's expanding healthcare infrastructure and rising surgical procedure volume continue to contribute meaningful incremental regional growth, supported by government investment in healthcare access expansion. Japan and South Korea contribute additional regional scale through established medical device manufacturing sectors increasingly integrating advanced surgical drilling technology into domestic healthcare delivery, reinforcing Asia Pacific's position as the fastest-growing market for surgical drills through the forecast period.
MEA & Latin America Surgical Drill Market Insights
The Middle East & Africa market is supported by growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia, where regional governments continue prioritizing advanced medical technology procurement as part of broader healthcare capability development strategies. Regional surgical volume continues to grow alongside expanding hospital infrastructure investment.
Latin America's market is led by Brazil, where a substantial domestic healthcare sector sustains steady demand for surgical drilling technology across orthopedic and general surgical applications. Mexico is contributing growth as regional healthcare infrastructure continues to expand, with adoption across the broader region concentrated among larger hospital systems with established surgical program capability.
Market Dynamics
Growth Drivers: Rising Surgical Volume and Minimally Invasive Technique Adoption
Increasing demand for minimally invasive procedures represents the primary driver of Surgical Drill Market growth, as advancements in orthopedic surgeries and the growing global aging population continue expanding the pool of patients requiring joint replacement, spinal fusion, and other drilling-intensive surgical interventions. As the number of surgeries rises, especially joint replacements and spinal operations, the surgical drill market continues to expand alongside sustained technological integration and improved patient outcomes that continue reinforcing clinician confidence in modern drilling technology.
Rising cases of brain tumors and nervous system cancer represent a second major growth driver, giving rise to an increasing number of neurovascular surgeries worldwide that require specialized, high-precision drilling technology. Escalating prevalence of chronic diseases and sports-related injuries continues to fuel demand across orthopedic, dental, and neurosurgery applications alike, reinforcing sustained baseline surgical drill demand growth even independent of the technological advancement trends reshaping the broader competitive landscape.
Restraints: High Equipment Costs and Sterilization Complexity
The issue of high costs of equipment can be regarded as an important restraint, as more sophisticated surgical drilling devices, especially the ones used with robotic navigation systems, keep demanding considerable capital expenses which smaller hospitals and ambulatory surgery centers are not always able to justify as opposed to less sophisticated instruments for surgical drilling.
Sterilization and reprocessing is another significant restraint, as more reusable surgical drilling instruments keep demanding a certain level of thorough cleaning, sterilizing, and maintenance between procedures, which makes operations more expensive and difficult to arrange in some healthcare institutions, especially in the context of ambulatory surgery centers.
Opportunities: Robotic Drilling Integration and Battery Technology Advancement
Continued integration of robotic guidance systems with surgical drilling technology represents a substantial opportunity, as manufacturers that can successfully deliver genuinely improved implant placement accuracy through robotically assisted drilling are positioned to capture demand from surgeons and hospital systems increasingly prioritizing precision and reproducibility over traditional freehand surgical technique.
The continued advancement of battery chemistry and cordless drilling technology offers a further substantial avenue for growth, as manufacturers that can deliver genuinely reliable, high-performance cordless alternatives to pneumatic and corded electric systems are well positioned to capture demand from hospitals seeking to reduce operating room turnover time and simplify surgical instrumentation logistics across their broader surgical program.
Recent Developments:
-
2025: Monogram Technologies received FDA 510(k) clearance for its CT-based, semi-autonomous, AI-navigated total knee arthroplasty robotic drilling technology. The clearance represented a key regulatory milestone ahead of the technology's planned commercialization with Zimmer Biomet implants beginning in early 2027.
-
2026: Stryker expects to launch its MAKO RPS system, a handheld version of its robotic surgical platform geared specifically toward ambulatory surgery center settings. The launch reflects the broader industry shift toward extending robotic-assisted drilling and bone preparation capability into lower-acuity care settings.
-
2024: Stryker and Zimmer Biomet both rolled out shoulder applications on their respective robotic systems for the first time, aiming to make shoulder reconstructive surgery bone preparation easier through robotically guided drilling. Both companies planned limited 2025 launches focused on training protocols ahead of broader market launches in 2026.
Surgical Drill Market Key Players
-
Stryker Corporation
-
Medtronic plc
-
Zimmer Biomet Holdings, Inc.
-
Johnson & Johnson (DePuy Synthes)
-
Smith & Nephew plc
-
B. Braun Melsungen AG
-
Arthrex, Inc.
-
Conmed Corporation
-
Brasseler USA
-
NSK Ltd.
-
KLS Martin Group
-
Integra LifeSciences Holdings Corporation
-
Colson Medical
-
Bien-Air Surgery SA
-
W&H Dentalwerk Bürmoos GmbH
-
Exactech, Inc.
-
Globus Medical, Inc.
-
Monogram Technologies Inc.
-
Anspach Effort, Inc.
-
Aygun Surgical Instruments
Surgical Drill Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.04 Billion |
| Market Size by 2035 | USD 1.84 Billion |
| CAGR | CAGR of 5.84% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Electric Drills, Pneumatic Drills, Battery-Powered Drills) • By Speed (High-Speed, Standard Speed) • By Application (Orthopedic Surgeries, Neurosurgery, Dental Surgeries, ENT Surgeries) • By End User (Hospitals & Clinics, Ambulatory Surgery Centers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Stryker Corporation, Medtronic plc, Zimmer Biomet Holdings, Inc., Johnson & Johnson (DePuy Synthes), Smith & Nephew plc, B. Braun Melsungen AG, Arthrex, Inc., Conmed Corporation, Brasseler USA, NSK Ltd., KLS Martin Group, Integra LifeSciences Holdings Corporation, Colson Medical, Bien-Air Surgery SA, W&H Dentalwerk Bürmoos GmbH, Exactech, Inc., Globus Medical, Inc., Monogram Technologies Inc., Anspach Effort, Inc., Aygun Surgical Instruments |
Frequently Asked Questions
Key players include Stryker Corporation, Medtronic plc, Zimmer Biomet Holdings, Inc., Johnson & Johnson, Smith & Nephew plc, and B. Braun Melsungen AG, among other medical device manufacturers.
Continued integration of robotic guidance systems with surgical drilling technology and continued advancement of battery chemistry and cordless drilling technology represent the primary opportunities.
Growth is primarily driven by increasing demand for minimally invasive procedures combined with rising cases of brain tumors and nervous system cancer driving neurosurgical volume.
By Application, Orthopedic Surgeries dominated the market with approximately 64.60% share in 2025, anchored by rising demand for joint replacement and spinal fusion procedures.
North America dominated the market with approximately 39.60% share in 2025, supported by advanced healthcare infrastructure and high adoption of robotic surgical techniques.
