
Radiation Oncology Treatment Planning Software Market Report Scope and Overview
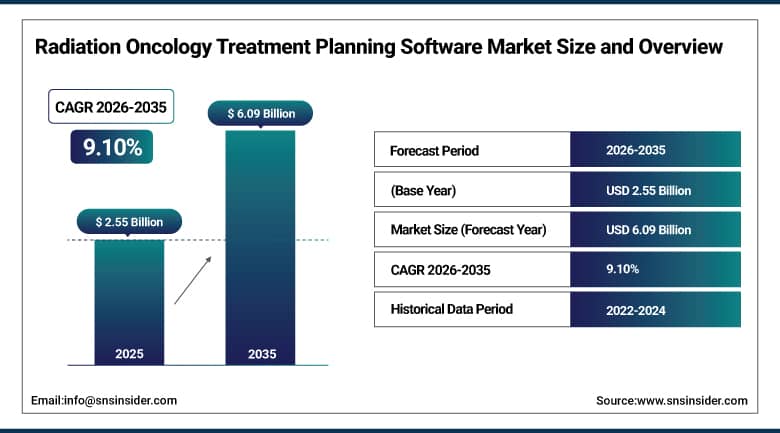
The Radiation Oncology Treatment Planning Software Market was valued at USD 2.55 Billion in 2025 and is estimated at USD 2.78 Billion in 2026. The market is forecast to reach USD 6.09 Billion by 2035, registering a CAGR of 9.10% from 2026 to 2035. Treatment planning software lets radiation oncology teams contour tumors and nearby organs, calculate dose distributions, and prepare plans for delivery. North America accounted for the largest regional share at 40.20% in 2025, while Asia Pacific is expected to grow fastest. Growth is driven by AI contouring, adaptive workflows, and wider access to radiotherapy.
To Get More Information On Radiation Oncology Treatment Planning
Software Market - Request Free Sample Report
Key Market Trends & Insights
- By product: Treatment planning systems held the largest market share of 48.60% in 2025.
- By therapy type: External beam radiation therapy held the largest market share of 76.80% in 2025.
- By deployment: On-premise solutions held the largest market share of 62.40% in 2025.
- By end user: Hospitals held the largest market share of 68.30% in 2025.
- North America accounted for the largest regional share of 40.20% in 2025.
- Asia Pacific is projected to register the fastest regional CAGR of 11.60% from 2026 to 2035.
- The U.S. is the leading country market, supported by a large base of treatment centers and early adoption of AI-assisted planning.
Growth Outlook
Radiation therapy is part of the care pathway for roughly half of all cancer patients, and the number of people who need treatment keeps rising with population ageing and better screening. Every course of treatment starts with a plan, so software that contours targets, optimizes dose, and checks plan quality sits at the center of the clinical workflow. Centers that expand their linear accelerator fleets or add proton and brachytherapy services also need matching planning capacity, which keeps license and upgrade spending on a steady upward path across the forecast period.
Technology change adds a second layer of growth. Deep learning models now draw organ outlines in minutes instead of hours, and online adaptive workflows let teams re-plan while the patient is on the table. Both approaches raise the value of each software seat and push buyers toward subscription and cloud models. Vendors are bundling contouring, adaptive planning, and plan checking into suites, which supports higher revenue per site and longer customer relationships over the coming decade. Cloud access also helps smaller clinics adopt advanced tools.
Market Dynamics
Driver: AI Auto-Contouring, Adaptive Planning, and Rising Cancer Caseloads Increase Software Demand
Manual contouring is one of the most time-consuming steps in radiotherapy, and clinics facing staff shortages are turning to automated tools that outline organs at risk and tumor volumes. Faster planning shortens the wait between diagnosis and treatment, lets physicists handle more patients, and improves consistency between clinicians. As the evidence for these tools grows, hospitals are moving them from pilot projects into routine use across every treatment site. Rising cancer caseloads add pressure, because departments must plan more courses of treatment without a matching increase in physicists and dosimetrists, which makes automation an attractive way to protect quality while keeping waiting times short for patients who need prompt care.
Regulators have also shown that they are ready to clear this category. The Food and Drug Administration cleared several AI contouring products between March and July 2026, which gives buyers confidence about validation and safety. Adaptive planning, which re-optimizes dose to match daily anatomy, builds on the same technology and is expected to create fresh demand for dedicated modules, computing capacity, and training services in the years ahead. Vendors are also training models on larger and more diverse datasets, and they are adding review tools that allow clinicians to accept or edit each automated outline before a plan is finalized, which supports trust and speeds adoption.
Restraint: Payment Pressure, Integration Complexity, and Cybersecurity Concerns Slow Purchasing Decisions
Treatment planning software is expensive to buy, validate, and maintain, and each change to a planning system requires physics commissioning and staff training. Many centers run equipment from several vendors, so connecting planning software to linear accelerators, imaging systems, and oncology information systems takes careful testing. These costs and the effort involved lead some smaller departments to postpone upgrades or keep older versions running for longer. Software updates may also require retraining of physicists and dosimetrists, and any change to a dose engine must be tested against measured data before it is used on patients, which makes decision makers cautious about the timing of upgrades.
Reimbursement is also under pressure. The Centers for Medicare and Medicaid Services issued its final physician fee schedule for 2026 on 31 October 2025, with an efficiency adjustment that lowered payment for many radiation oncology codes. Practices facing tighter margins review capital and software budgets closely, while concerns about patient data security make cloud adoption slower in some health systems. Vendors also face growing expectations on software security, including patching, access control, and clear documentation, and these requirements add cost and lengthen sales cycles for both suppliers and hospitals that handle sensitive records. Public hospitals also face long budget approval cycles.
Opportunity: Cloud Delivery, Proton Planning, and Theranostic Dosimetry Open New Revenue Streams
Cloud-based planning allows smaller and rural centers to use advanced tools without maintaining their own servers. On 9 July 2026, the American Society for Radiation Oncology reported that about 50.8 million Americans live in counties without a radiation oncology site, which highlights the need for remote planning, shared contouring services, and tele-physics support. Vendors that offer secure, subscription-based platforms can reach these underserved providers. Subscription pricing and managed services can also lower the barrier for new buyers, since centers can spread costs over time and rely on vendors for upgrades, monitoring, and expert support in place of building large in-house teams.
Particle therapy and molecular radiotherapy add further openings. Proton centers need specialized optimization for range uncertainty and upright positioning, and radiopharmaceutical therapy requires dosimetry software that estimates dose to tumors and organs from imaging. Few vendors cover these areas well today, so those that build credible products can win placements and form lasting partnerships with equipment makers. Integration with imaging, scheduling, and quality assurance tools can also create bundled offers, and suppliers that provide clear data exchange standards will be well placed to expand within large health systems and international hospital groups. These areas also attract research funding and clinical trial partnerships.
Market Characteristics & Concentration
The Radiation Oncology Treatment Planning Software Market is Moderately Consolidated. Varian, part of Siemens Healthineers, Elekta, RaySearch, Brainlab, and GE HealthCare through MIM Software are the best-known suppliers, while Accuray, IBA, Mirion, Radformation, and several AI specialists compete in specific parts of the workflow. Most large suppliers sell treatment machines as well as software, which helps them bundle planning licenses with equipment contracts. Regional distributors support smaller markets. Bundled equipment offers are common.
Competition centers on plan quality, calculation speed, breadth of auto-contouring models, adaptive capability, vendor-neutral integration, and service. Buyers value open interfaces that work with linear accelerators from different makers, and vendors that support mixed fleets gain an advantage in large multi-site health systems. Independent software vendors position themselves as machine-neutral, and this approach appeals to centers that operate equipment from different manufacturers and want one planning environment. Service response times matter greatly.
Barriers to entry are high because planning algorithms need clinical validation, regulatory clearance, and commissioning data, and physicists tend to stay with systems they know. New entrants therefore focus on narrow AI tools or cloud workflows and often partner with larger suppliers to reach hospitals. Partnerships between AI developers and established platforms are common, and they allow smaller companies to reach clinics while larger vendors add new capabilities quickly. Regulatory timelines also deter newcomers.
Analyst Perspective
Treatment planning is moving from a standalone calculation tool to a connected platform that spans contouring, adaptive re-planning, quality assurance, and data analytics. Growth will favor vendors that offer open integration, validated AI models, and flexible licensing, while buyers will weigh software value against tight reimbursement. Asia Pacific and other emerging regions are expected to add capacity quickly, and cloud delivery should help smaller centers reach advanced capabilities. An SNS Insider Analyst, commented, "The next stage of planning software competition will be won on workflow speed and trust in AI, and vendors that let clinicians review and adjust every automated step will earn the widest adoption."
Segment Analysis
Product Insights
Treatment planning systems accounted for 48.60% of the market in 2025. These platforms calculate dose, optimize beam arrangements, and produce the plans that are sent to treatment machines, so every radiotherapy center needs one. Upgrades that add faster dose engines, deep learning contouring, and plan comparison tools keep customers on maintenance contracts and support steady revenue. Vendors also provide dose engines that handle photons, electrons, and particles, which broadens the use of a single platform across modalities and lowers training needs for physics teams in large departments. Annual license renewals and optional modules for adaptive, dose summation, and plan comparison allow vendors to grow revenue per site.
Professional services constitute the fastest-growing product category with a CAGR of 11.40% expected between 2026 and 2035. There is a huge requirement for implementation, commissioning, training, and optimization services due to the increasing deployment of adaptive and artificial intelligence-based workflows. Information systems for patients create additional recurring demand due to integration with scheduling, records, and treatment information systems, which are purchased by many treatment centers along with planning software. Combined with maintenance services, they help generate predictable recurring revenues while fostering long-term relationships between suppliers and hospitals or cancer care networks.
Therapy Type Insights
External beam radiation therapy accounted for 76.80% of the market in 2025. Techniques such as intensity modulated and volumetric modulated arc therapy, stereotactic radiosurgery, and body radiotherapy are used for most patients and rely on complex optimization. Linear accelerators are widely installed, so planning software for external beam treatment forms the base of vendor revenue. Standardized protocols and automation tools reduce planning time for common sites such as prostate, breast, and lung, and this supports high patient throughput in busy departments. Hypofractionated schedules have also increased the importance of precise planning, because higher doses per session leave little room for error.
Particle therapy is the fastest growing therapy type, with a projected CAGR of 12.60% from 2026 to 2035. New proton centers and upright treatment concepts require specialized optimization, robust planning, and imaging workflows. Brachytherapy remains important for gynecologic and prostate cancers, and software that combines it with external beam dose is gaining interest. Combined planning for brachytherapy and external beam is also becoming more common in gynecologic care, and vendors are adding dose summation tools that help teams evaluate the full course of treatment. Dose summation tools help teams review prior treatment when patients return for a second course.
Deployment Insights
On-premise solutions accounted for 62.40% of the market in 2025. Large hospitals prefer local servers because of data control, integration with existing treatment machines, and established security policies. Physicists are familiar with these systems, and long validation histories make replacement slow even when new features are attractive. Many hospitals keep on-premise systems for core planning and add cloud tools for contouring or analytics, which creates a hybrid pattern that suits cautious buyers with large installed bases. Vendors often provide migration tools and parallel running periods so that centers can switch without interrupting treatment schedules.
Cloud-based deployments are growing at the highest rate, with a forecasted CAGR of 13.80% from 2026 to 2035. The advantages of remote connectivity, automatic software updates, scalable computing for AI models, and reduced upfront costs attract small centers and network organizations. Software providers now provide hybrid solutions where sensitive data will be stored locally, while the cloud will be used for complex computing tasks. Security assessment, service-level agreement conditions, and data residency requirements continue to play important roles in decision-making on cloud deployments, and those providers that provide transparent information in these areas help reduce the length of the sales process.
End User Insights
Hospital segment had a market share of 68.30% in 2025. Most of the radiotherapy departments function under academic medical centers and community hospitals and spend in planning systems, contouring systems and software for quality assurance as part of the comprehensive oncology programs. Purchase is normally coordinated by the doctors, physicists and the IT departments. Quality assurance and plan review and physician comparison software is also used by the radiation oncology department and it is usually purchased along with other similar software. Large organizations standardize on one brand across all of their locations for easy data transfer among others.
Cancer treatment centers are the fastest growing end user, with a projected CAGR of 10.60% from 2026 to 2035. Freestanding centers and ambulatory networks are expanding in many countries and favor efficient, cloud-ready workflows. Research centers and government institutions add demand through clinical trials, national programs, and development of new techniques. Government institutions and national cancer programs also buy planning software for public hospitals, often through tenders that emphasize interoperability, local training, and long-term service commitments. Public tenders in many countries also require local service presence, which favors suppliers with established regional teams and partners.
Regional Insights
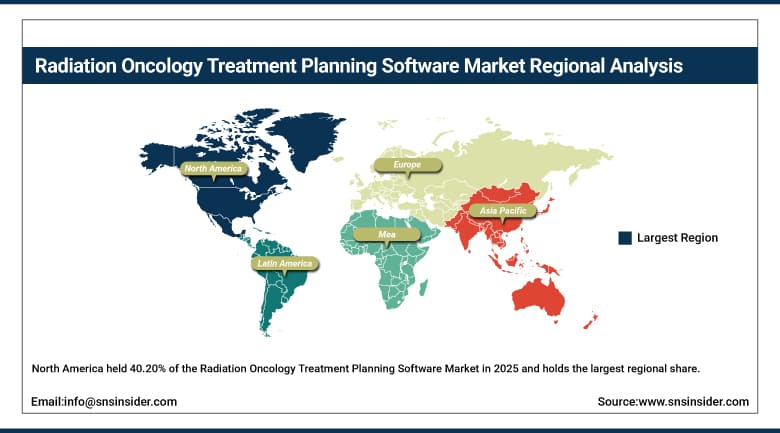
North America held 40.20% of the Radiation Oncology Treatment Planning Software Market in 2025 and holds the largest regional share. The region has a dense network of radiotherapy centers, early adoption of AI-assisted planning, and the headquarters of several leading vendors. Mexico is reported within Latin America in this analysis, so regional figures here cover the United States and Canada only. Academic centers also lead many clinical trials of new planning methods. Canada adds demand through provincial cancer programs.
Get Customized Report as Per Your Business Requirement - Enquiry Now
U.S. Radiation Oncology Treatment Planning Software Market
The U.S. Radiation Oncology Treatment Planning Software Market was valued at USD 902.09 Million in 2025 and is projected to expand at a CAGR of 8.85% from 2026 to 2035. Health systems, academic centers, and freestanding cancer networks account for most purchases, and the country is the main early adopter of auto-contouring and adaptive planning products. Large networks also sign enterprise agreements that cover many sites, and this favors vendors that offer scalable licensing, centralized management, and consistent support.
Payment policy is a constant influence on buying decisions. Practices closely follow changes to radiation oncology fees, and many are looking for software that shortens planning time and allows physicists to treat more patients with the same staff. Cybersecurity and data governance reviews are also standard parts of procurement. Vendors with strong local service teams and training programs tend to win larger share in competitive tenders across the country. Smaller practices often rely on vendor support for upgrades.
Europe Radiation Oncology Treatment Planning Software Market
Europe accounted for 27.80% of the market in 2025, led by Germany, France, the United Kingdom, Italy, and Spain. The region is home to major planning software suppliers and a strong research base. On 16 December 2025, the European Commission published proposals to amend the medical device regulation, including changes that could affect software classification and the way AI products are certified. Hospitals in the region also invest in shared planning services across networks. National programs also support radiotherapy capacity.
Asia Pacific Radiation Oncology Treatment Planning Software Market
Asia Pacific is projected to register the fastest regional CAGR of 11.60% from 2026 to 2035, and the region held 22.60% of the market in 2025. China, Japan, India, South Korea, and Australia lead demand as governments expand cancer care capacity and install more linear accelerators and proton centers. Local vendors are also growing, particularly in China, and demand for AI-assisted tools is strong where specialist staff are scarce. Japan and South Korea also maintain advanced proton and carbon ion programs that need specialized planning.
Latin America Radiation Oncology Treatment Planning Software Market
Latin America held 5.20% of the market in 2025, led by Brazil and Mexico, followed by Argentina, Colombia, and Chile. Public programs and private hospital groups are adding linear accelerators and upgrading older planning systems. Buyers value vendors with regional support and training, and cloud services are drawing interest as a way to reach centers outside large cities. Training programs for physicists are supporting adoption in the region. Public reimbursement limits slow adoption in some countries.
Middle East & Africa Radiation Oncology Treatment Planning Software Market
The Middle East & Africa accounted for 4.20% of the market in 2025, led by Saudi Arabia, the United Arab Emirates, Qatar, Egypt, and South Africa. Gulf countries are investing in comprehensive cancer centers and proton facilities, while parts of Africa are expanding basic radiotherapy access with support from international health programs and training partnerships. Imports of equipment and software are common, and vendors that bundle training and remote support help new centers start treatment quickly and consistently.
Key Radiation Oncology Treatment Planning Software Market Company Insights
Competition in the Radiation Oncology Treatment Planning Software Market spans integrated radiotherapy vendors, imaging and informatics groups, and specialists in AI contouring and plan quality. Leading participants compete on plan quality, speed, integration, adaptive capability, and service. Partnerships between vendors are increasing.
Key Radiation Oncology Treatment Planning Software Companies:
- Varian (Siemens Healthineers AG)
- Elekta AB
- RaySearch Laboratories AB
- Brainlab AG
- GE HealthCare Technologies Inc. (MIM Software)
- Accuray Incorporated
- IBA (Ion Beam Applications S.A.)
- Mirion Technologies, Inc. (Sun Nuclear)
- Radformation, Inc.
- DOSIsoft SA
- TheraPanacea
- Mevion Medical Systems, Inc.
Recent Developments
- In September 2026, Elekta expanded its adaptive radiotherapy portfolio on the Elekta ONE platform, adding online adaptive and real-time adaptive brachytherapy planning workflows.
- In July 2026, Varian, a Siemens Healthineers company, received U.S. clearance for its AI Contouring software for Eclipse, extending automated structure outlining.
- In July 2026, RaySearch Laboratories released RayStation 2026, adding reirradiation tools, new deep learning segmentation models, and proton planning enhancements.
- In June 2026, GE HealthCare received U.S. clearance for MIM Contour ProtegeAI+ 2.0, expanding AI auto-contouring through MIM Software.
- In May 2026, DOSIsoft launched DOSIsoft Theranostics to focus on dosimetry for molecular radiotherapy.
- In March 2026, Radformation received U.S. clearance for its AutoContour software, strengthening its AI planning portfolio.
- In June 2025, Brainlab received U.S. clearance for RT Elements 4.5, which adds AI tumor segmentation for cranial and spine radiosurgery planning.
- In April 2025, Sun Nuclear, a Mirion company, acquired Oncospace to add predictive plan quality tools to its software portfolio.
Scope and Research Methodology
This report estimates the Radiation Oncology Treatment Planning Software Market through a bottom-up build from the installed base of radiotherapy centers and software licenses, typical annual spending per site, and maintenance and upgrade cycles, checked against a top-down view of vendor revenue and cancer treatment volumes in each region. The scope covers treatment planning systems, patient information systems, and related professional services used in radiation oncology. Radiotherapy hardware and general medical oncology information systems are excluded from the estimate. License counts are cross-checked with machine installations, procedure volumes, and vendor disclosures to confirm unit estimates and adoption rates by region and by product. Assumptions on pricing per license are validated against vendor quotations and tender records collected from hospitals in each region.
Secondary research draws on regulatory databases, society publications, company reports, and technical literature. Primary research includes conversations with radiation oncologists, medical physicists, dosimetrists, hospital information technology leaders, and vendor executives, used to confirm pricing, adoption, and workflow trends. Region coverage follows the five regions used throughout this report, with Mexico reported within Latin America. Interviews are repeated across hospital types and regions so that findings do not depend on a single viewpoint, and responses are compared with published treatment statistics wherever such data exist. Where public data are limited, assumptions are documented and tested through expert review.
Segment shares are built from license data and procedure volumes by product, therapy type, deployment model, and end user, then aligned with regional totals. Forecasts apply growth assumptions for each segment and region that reflect treatment center expansion, AI adoption, reimbursement, and regulatory change, and they are tested against alternative scenarios. Figures are reviewed at each update as new data become available, and values are stated in U.S. dollars. Estimates in this report are draft values prepared for internal review and are updated when new data are collected. All estimates are rounded to two decimals for consistency across tables and text.
Radiation Oncology Treatment Planning Software Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.55 Billion |
| Market Size by 2035 | USD 6.09 Billion |
| CAGR | CAGR of 9.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Treatment Planning Systems, Patient Information Systems, and Professional Services) • By Therapy Type (External Beam Radiation Therapy, Brachytherapy, and Particle Therapy) • By Deployment (On-Premise and Cloud-Based) • By End User (Hospitals, Cancer Treatment Centers, Research Centers, and Government Institutions) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Varian, Elekta, RaySearch, Brainlab, GE HealthCare |

Frequently Asked Questions
The market was valued at USD 2.55 Billion in 2025 and is projected to reach USD 6.09 Billion by 2035.
The market is expected to register a CAGR of 9.10% from 2026 to 2035.
North America led the market with a 40.20% share in 2025.
Asia Pacific is expected to grow the fastest, at a CAGR of 11.60% from 2026 to 2035.
Key players include Varian, Elekta, RaySearch, Brainlab, and GE HealthCare.
