
Real World Evidence Solutions Market Report Scope & Overview:
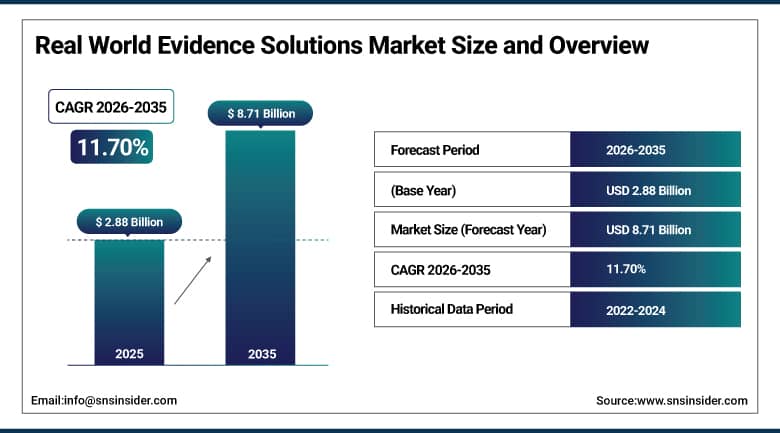
The Real World Evidence Solutions Market was valued at USD 2.88 Billion in 2025 and is expected to reach USD 8.71 Billion by 2035, growing at a CAGR of 11.70% from 2026-2035.
The Real World Evidence Solutions Market is expanding quickly as regulators, payers, and drug developers rely on evidence from routine care. Electronic records, claims, registries, and patient generated data now feed studies that once required a trial. Sponsors use the results to support approvals, label expansions, and coverage decisions. Analytics platforms and federated networks shorten study timelines and lower cost. Artificial intelligence is improving data curation and cohort building. Regulators are publishing clearer expectations for data quality and study design. Pharma companies are building internal evidence teams and also buying services from specialist providers. Oncology and rare disease programs generate the strongest demand.
⮞In December 2025, the U.S. Food and Drug Administration issued final guidance on the use of real world evidence to support regulatory decision making for medical devices, with expectations applying from 17 February 2026. The guidance makes real world data a routine input for device submissions.
To Get More Information On Real World Evidence Solutions Market - Request Free Sample Report
Real World Evidence Solutions Market Trends:
-
Federated data networks that link health systems without moving patient records
-
Use of artificial intelligence for data curation, cohort selection, and natural language queries
-
External control arms and synthetic comparators in rare disease and oncology programs
-
Formal regulatory frameworks for real world evidence in Europe, China, and the Gulf
-
Consolidation of data assets through acquisitions and platform partnerships
U.S. Real World Evidence Solutions Market Outlook:
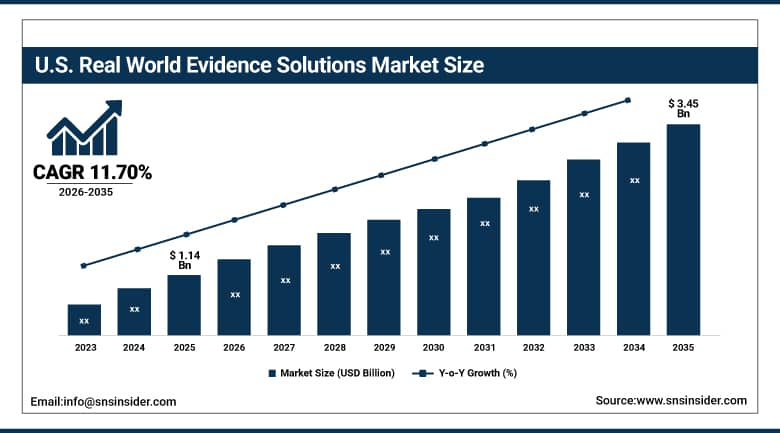
The U.S. Real World Evidence Solutions Market was valued at USD 1.14 Billion in 2025 and is expected to reach USD 3.45 Billion by 2035, growing at a CAGR of 11.70% from 2026-2035.
The U.S. Real World Evidence Solutions Market is the largest national market because of deep data assets and an active regulatory environment. Health systems, payers, and specialty networks hold large longitudinal datasets. Federal programs encourage the use of routine care data in submissions. Pharma sponsors place most of their evidence budgets here because of early access to claims, electronic records, and oncology registries. Value based contracting increases payer demand for outcomes evidence. Technology firms, contract research organizations, and data vendors compete through data breadth, privacy tools, and analytic speed. Privacy rules and data licensing costs shape vendor selection and study design across the country.
⮞In June 2026, TriNetX reported that its LIVE network exceeded 300 million patients. A network of this size gives sponsors fast access to cohorts for feasibility and outcomes research.
Real World Evidence Solutions Market Segment Analysis:
-
By Component, the Services segment dominated the Real World Evidence Solutions Market with approximately 59.12% share in 2025, while the Data Sets segment is the fastest growing with a CAGR of approximately 12.58%.
-
By Application, the Drug Development and Approvals segment dominated the Real World Evidence Solutions Market with approximately 36.70% share in 2025, while the Market Access and Reimbursement segment is the fastest growing with a CAGR of approximately 13.06%.
-
By End User, the Pharma and Medical Device Companies segment dominated the Real World Evidence Solutions Market with approximately 53.68% share in 2025, while the Payers segment is the fastest growing with a CAGR of approximately 12.20%.
-
By Therapeutic Area, the Oncology segment dominated the Real World Evidence Solutions Market with approximately 28.69% share in 2025, while the Neurology segment is the fastest growing with a CAGR of approximately 14.09%.
By Component, Services Dominates the Real World Evidence Solutions Market and Data Sets Grows Fastest
Services lead because most sponsors need study design, protocol development, statistical analysis, and regulatory documentation that data alone cannot provide. Providers combine epidemiologists, biostatisticians, and data scientists to answer specific questions on safety, effectiveness, and cost. Many programs span several data sources, which makes expert curation and harmonization central to quality. Long relationships with pharmaceutical clients create recurring work across product life cycles. Contract research organizations and consultancies are expanding real world teams to capture demand from post approval commitments and health technology assessment submissions. Sponsors also seek help with regulatory interactions.
Data sets are expanding faster as sponsors seek direct access to curated and linked sources. Licensing models now cover claims, electronic records, registries, genomics, and patient reported information. Vendors invest in tokenization and privacy preserving linkage so that records from different sources can be combined without exposing identities. Analytics tools bundled with the data allow sponsors to run their own queries. Competition is shifting toward data quality, refresh frequency, and the ability to document provenance for regulators. Self service access is attracting mid sized biotechs that lack large internal teams.
⮞In July 2025, Datavant completed its acquisition of Aetion, creating an ecosystem of more than 300 data partners. The deal joins connected data with a regulatory grade analytics platform.
By Application, Drug Development and Approvals Dominates the Real World Evidence Solutions Market and Market Access and Reimbursement Grows Fastest
Sponsors use real world evidence mainly to support label expansions, safety commitments, and external comparator arms. Rare disease and oncology programs often lack feasible randomized controls, so historical patient data help establish context. Regulators accept well designed studies as supportive evidence and encourage early dialogue on data fitness. Pharma teams also use natural history studies to refine endpoints and inclusion criteria. Evidence plans are increasingly written before pivotal trials begin, which brings providers into projects earlier and lengthens engagement. This early involvement raises the value of each program.
Payers and health technology assessment bodies now demand proof of value in routine practice, which is lifting the access and reimbursement segment. Outcomes based agreements require ongoing measurement of patient results, which creates recurring analytic work. Sponsors build economic models using claims and electronic records to support price negotiations. Value assessments in Europe and the Asia Pacific region are asking for local data, which increases the number of country specific studies. Providers that combine health economics expertise with accessible data are positioned to win this work. Payer focused analytics tools also support formulary decisions and pathway design.
⮞In April 2026, Thermo Fisher Scientific's PPD clinical research business announced a collaboration to expand access to claims data covering more than 270 million de-identified patient lives. Claims scale of this kind supports both approval and access studies.
By End User, Pharma and Medical Device Companies Dominates the Real World Evidence Solutions Market and Payers Grows Fastest
Pharmaceutical and medical device companies account for the largest share because they fund most evidence generation across the product life cycle. Large sponsors run dedicated real world teams and buy data and analytics from several vendors. Medical device makers are expanding use as regulators clarify how routine care data can support submissions. Post market surveillance commitments add recurring demand. Mid sized and emerging biotech companies outsource more because they lack internal data science capacity, and they favor flexible licensing and subscription access. Global brands also commission studies in several countries to meet local requirements.
Insurers and government programs are the fastest growing customers as value based care models spread. They use real world analytics to monitor outcomes, assess coverage policies, and manage high cost therapies. Partnerships between payers and technology firms provide access to member level data and allow rapid cohort analysis. As cell and gene therapies enter the market, payers want longitudinal evidence on durability, which creates multi year monitoring programs and sustained demand for analytics. Employers and integrated delivery networks also commission outcomes analysis, which widens the customer base further.
⮞In January 2026, Oracle announced a life sciences AI data platform with more than 129 million de-identified patient records. Large provider derived datasets give sponsors direct access to point of care information.
By Therapeutic Area, Oncology Dominates the Real World Evidence Solutions Market and Neurology Grows Fastest
Cancer care generates rich longitudinal records and high value treatment decisions. Targeted therapies and immunotherapies create numerous subpopulations, and trials rarely cover all of them. Real world cohorts fill the gap by showing outcomes across biomarker groups, treatment sequences, and care settings. Genomic data linked to clinical records strengthens these analyses. Cancer centers and specialty networks collaborate with data companies to build disease specific datasets that support regulatory and payer submissions. Sponsors rely on these assets to plan trials and defend value. Demand also comes from post marketing commitments for newly approved drugs.
Sponsors targeting Alzheimer disease, Parkinson disease, multiple sclerosis, and rare neuromuscular disorders are driving faster growth in neurology. Progression is slow and heterogeneous, so natural history evidence is vital for trial design and for demonstrating value. Imaging, biomarker, and registry data are being linked to claims and records to track long term outcomes. Disease modifying therapies raise payer attention to real world effectiveness and safety. Investment in digital biomarkers and wearable data adds new evidence streams for providers with relevant expertise. Specialist neurology data networks are expanding as a result.
⮞In April 2026, Verana Health introduced a prostate cancer dataset covering more than 430,000 patients. Disease specific assets of this type help sponsors design oncology studies and support submissions.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
93.54% |
|
Europe |
United Kingdom |
26.84% |
|
Asia Pacific |
China |
38.27% |
|
Latin America |
Brazil |
52.46% |
|
Middle East & Africa |
Saudi Arabia |
31.18% |
North America Real World Evidence Solutions Market Insights
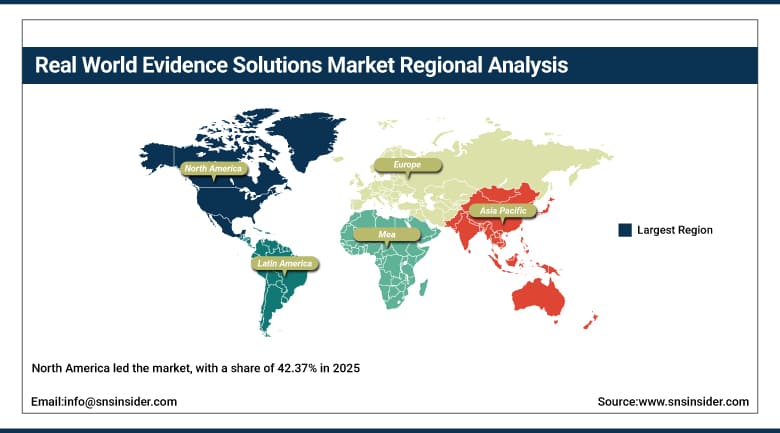
North America led the market, with a share of 42.37% in 2025, supported by large health data assets, regulatory openness, and strong pharmaceutical spending. The United States generates most regional demand, while Canada adds activity through provincial data repositories and academic networks. Sponsors prefer the region for early evidence generation because linked claims, electronic records, and oncology registries are readily available. Technology firms, health systems, and contract research organizations compete through partnerships that expand data coverage. Privacy compliance and data governance expertise are important selection criteria for vendors. Cloud platforms now let analysts query datasets without moving records.
Policy direction continues to strengthen the use of routine care data. Federal agencies are clarifying expectations for study design and data quality, and device regulators have expanded guidance. Large payers and integrated delivery systems are building internal evidence capabilities and partnering with vendors. Pharma sponsors increasingly request external control arms for oncology and rare disease programs. Natural language tools that allow clinicians and analysts to build cohorts without coding are entering the market. Consolidation among data owners is creating larger platforms, which raises the importance of neutral and transparent data access. Canadian health technology assessment agencies are exploring wider use of routine care data.
⮞In April 2026, Labcorp announced an AI driven real world data platform, built with cloud and data connectivity partners, to advance Alzheimer research. The platform shows how laboratory data are becoming a source of research grade evidence.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Real World Evidence Solutions Market Insights
Europe holds the second largest position, supported by national health systems with rich registries and a regulatory network that is investing in federated studies. The United Kingdom, Germany, France, Italy, and Spain contribute most of the regional demand. Health technology assessment bodies increasingly ask for evidence from routine care to support reimbursement decisions. Sponsors use European data to meet requests from multiple agencies and to support pricing negotiations in each country. Strong academic networks and public data repositories provide high quality evidence. Pharma companies place country specific studies to satisfy local access requirements.
Data protection rules shape study design. The general data protection regulation requires careful governance, which favors federated analysis and secure processing environments. Cross border research networks are expanding access to anonymized data for regulators and sponsors. Registry based studies, hospital networks, and national databases form the backbone of evidence generation. Providers differentiate through local language curation, regulatory expertise, and knowledge of national reimbursement processes. These capabilities help sponsors navigate fragmented systems while meeting the growing demand for transparent real world studies, and they support multi country submissions that need consistent methods.
⮞In February 2026, the European Medicines Agency reported that its DARWIN EU network had grown to 40 data partners across 18 countries. The network gives regulators fast access to studies based on routine care data.
Asia Pacific Real World Evidence Solutions Market Insights
Asia Pacific is the fastest growing region with an expected CAGR of 12.98% from 2026 to 2035, led by China, Japan, India, and Australia. Regulators are building formal pathways for real world data in drug registration, and large hospital networks are digitizing records. China is adopting international guidance on observational studies, while Japan encourages the use of routine care data in approval modifications. Sponsors need local evidence for access in each market, which raises study counts. Rising pharmaceutical investment and expanding oncology care add to demand. India and Southeast Asia are building digital health infrastructure that will widen data availability.
Providers are responding with regional data partnerships and local analytics teams. Multinational sponsors want consistent evidence across countries, so vendors that can harmonize data from China, Japan, and Southeast Asia gain an edge. Language, coding, and privacy differences remain challenges, and many vendors partner with local hospitals and registries. Telehealth and mobile health records are increasing the volume of patient level data. Government backed health data platforms in several countries are also improving access for researchers. These developments are expected to lift study volumes in oncology, rare disease, and chronic conditions.
⮞In January 2026, China's National Medical Products Administration announced the adoption of the ICH M14 guideline on observational studies that use real world data, applying to studies that start on or after 27 January 2026. The adoption aligns Chinese expectations with international standards.
MEA & Latin America Real World Evidence Solutions Market Insights
Latin America is developing through public health data programs and growing private hospital networks in Brazil, Mexico, and Argentina. Mexico belongs to this region in market estimates, and its social security institutes hold large patient datasets. Regulators are exploring the use of post registration data to monitor safety and effectiveness. Sponsors use local studies to support pricing and access in public systems, where budget impact is a central concern. Limited data linkage and fragmented records slow adoption, yet digital health investment is raising the quality of available data. Regional contract research organizations are adding real world capabilities.
⮞In December 2024, Brazil's health regulator ANVISA was reported to be preparing a three year pilot with public hospital and research partners to build a post registration real world data model. Such pilots lay the foundation for regulatory use of local evidence.
The Middle East and Africa region is moving from policy design to implementation, led by Saudi Arabia and the United Arab Emirates. Health authorities are publishing frameworks for the use of real world data in marketing authorization and are building national health records. Gulf governments invest in genomic programs and digital health platforms that create valuable datasets. Pharma companies use local studies to support access in centralized procurement systems. Data localization rules and limited data standardization remain barriers, but government funding and international partnerships are raising capabilities across the region.
⮞In April 2026, the Saudi Food and Drug Authority issued a framework on the use of real world data and evidence, effective from 20 July 2026. The framework gives sponsors a formal route to submit routine care evidence in the Kingdom.
Market Dynamics:
Growth Drivers: Regulatory Acceptance and Expanding Digital Health Data Drive Growth in the Real World Evidence Solutions Market
Regulators across major markets now treat real world evidence as a credible complement to clinical trials. Guidance on study design, data quality, and transparency gives sponsors a clearer path, and agencies encourage early scientific dialogue. This reduces uncertainty and encourages investment in evidence plans. Label expansions, safety monitoring, and device submissions all benefit from the extra source of evidence. Pharma companies also use these studies to support external comparators in diseases where randomized trials are difficult. Rising trial costs add incentive to extract more value from routine care data.
The volume and quality of digital health data are also improving. Electronic health records, claims, registries, genomics, and wearable devices create broad longitudinal information, and interoperability standards make it easier to combine them. Artificial intelligence accelerates data cleaning and cohort building, which shortens study timelines. Value based payment models add demand for outcomes monitoring. Collaboration among technology firms, health systems, and contract research organizations is creating integrated offerings that reduce complexity for sponsors. Together these forces support double digit expansion over the forecast period.
⮞In May 2026, the UK Medicines and Healthcare products Regulatory Agency relaunched its real world evidence scientific dialogue programme. The programme gives sponsors early regulatory feedback on study design and data fitness.
Restraints: Data Fragmentation and Privacy Constraints Restrain Growth in the Real World Evidence Solutions Market
Data from the real world come from separate sources that have different coding standards, formats, and degrees of completeness. Problems associated with missing values, inconsistent recording, and limited follow-up create challenges for analysis and bias concerns. Connecting datasets between different sources takes special tools and licenses, and hence time and money. The acquisition of a high-quality longitudinal database costs money and leads to exclusivity. Observational studies are still subject to critical assessment by regulators and payers, which drives sponsors to spend a lot of money on developing robust methodologies.
The legislation regarding privacy and governance is specific for each country and is being made more restrictive. Transfers of data cross border have limitations in certain countries, and restrictions concerning consent prevent using certain records. Vendors will require more sophisticated de-identification and secure environment that raises operational costs. Lack of epidemiologists, data engineers, and health economists hinders the process of scaling up the service. Delayed introduction of the health data framework on a national level affects access to public databases. Therefore, sponsors allocate longer timelines for programs that use multiple countries.
⮞In March 2025, the European Commission confirmed that the European Health Data Space regulation entered into force, with rules for secondary use of health data applying from March 2029. The long lead time delays broad access to public health data across member states.
Opportunities: Artificial Intelligence and Emerging Market Frameworks Create Opportunities in the Real World Evidence Solutions Market
Artificial intelligence offers major efficiency gains in data mapping, cleaning, and evidence synthesis. Natural language interfaces let scientists create cohorts and run feasibility checks without specialist coding. Large language models can extract information from clinical notes, which expands usable data and fills gaps in structured fields. Providers that embed these tools with audit ready workflows can shorten study timelines and offer predictable pricing. Sponsors benefit from faster answers during trial planning and from continuous evidence monitoring after launch. Validation and transparency will determine which tools win regulatory trust.
Emerging markets present a second opportunity as regulators publish formal frameworks for real world data. Governments in the Gulf, Asia, and Latin America are building national health records and genomic programs that create new datasets. Local evidence requirements for pricing and access increase demand for country specific studies. Providers can build regional hubs, partner with local hospitals, and offer federated analysis that respects data localization rules. Early movers can secure data partnerships and regulatory relationships that will be difficult for later entrants to replicate. Multinational sponsors want one partner that can deliver consistent evidence across regions.
⮞In June 2026, the Abu Dhabi Department of Health presented its Living Lab for intelligent life sciences, which combines real world clinical, genomic, and lifestyle data. Government backed platforms of this type create new data sources for sponsors.
Recent Developments:
-
In May 2026, HealthVerity completed its acquisition of Symphony Health from ICON, combining two large sources of claims and linked patient data.
-
In January 2026, ConcertAI announced a linked dataset that combines Foundation Medicine genomic data with clinical records for nearly half a million cancer patients.
-
In February 2026, Veradigm introduced a real world data survey solution that adds patient reported information to its provider network, which includes more than 20,000 practices.
-
In July 2025, Flatiron Health tripled its international oncology research network, adding sites in the United Kingdom, Germany, and Japan for a total of more than 30.
Real World Evidence Solutions Market Key Players are:
-
IQVIA
-
Flatiron Health
-
Oracle Health
-
TriNetX
-
HealthVerity
-
Thermo Fisher Scientific (PPD)
-
Datavant
-
Verana Health
-
ConcertAI
-
Parexel
-
Labcorp
-
Tempus
-
Veradigm
-
Komodo Health
-
Truveta
-
Ontada
-
Carelon Research
-
OM1
-
Merative
-
Norstella
Real World Evidence Solutions Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.88 Billion |
| Market Size by 2035 | USD 8.71 Billion |
| CAGR | CAGR of 11.70% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Services and Data Sets) • By Application (Drug Development and Approvals, Market Access and Reimbursement, Regulatory Decision-Making, and Others) • By End User (Pharma and Medical Device Companies, Payers, Providers, and Others) • By Therapeutic Area (Oncology, Neurology, Cardiology, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | IQVIA, Flatiron Health, Oracle Health, TriNetX, HealthVerity, Thermo Fisher Scientific (PPD), Datavant, Verana Health, ConcertAI, Parexel, Labcorp, Tempus, Veradigm, Komodo Health, Truveta, Ontada, Carelon Research, OM1, Merative, Norstella |

Frequently Asked Questions
Key players in the market include IQVIA, Flatiron Health, Oracle Health, TriNetX, Datavant, and Thermo Fisher Scientific (PPD), among others.
Key opportunities include artificial intelligence for data curation, cohort building, and evidence synthesis, and emerging market frameworks that open new datasets and country specific study demand.
Regulatory acceptance of real world evidence is the major growth factor, supported by expanding digital health data. Clearer guidance encourages sponsors and payers to invest in evidence from routine care.
The Services segment dominated the market in 2025 with approximately 59.12% share, as sponsors need study design, analysis, and regulatory documentation that data alone cannot supply.
North America dominated the market in 2025 with approximately 42.37% share, supported by large health data assets, regulatory openness, and strong pharmaceutical spending.
