
Ruminant Methane Reduction Market Report Scope & Overview:
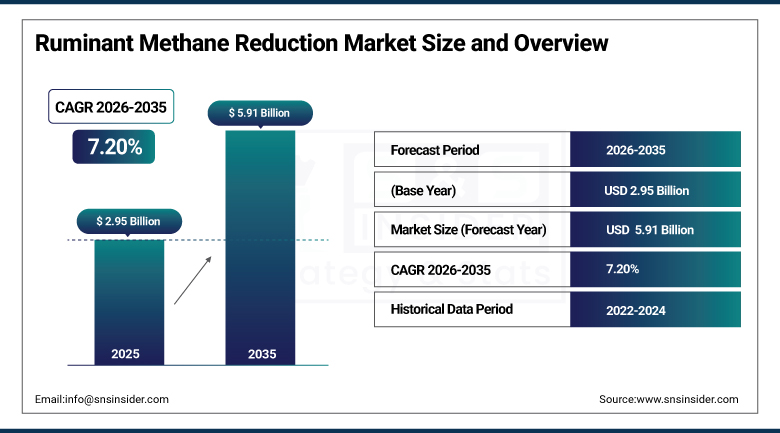
The Ruminant Methane Reduction Market was valued at USD 2.95 Billion in 2025 and is expected to reach USD 5.91 Billion by 2035, growing at a CAGR of 7.20% from 2026-2035.
Ruminant methane reduction solutions constitute a rapidly maturing category within sustainable agriculture, integrating feed additives, genetic breeding programs, and management practices designed to lower enteric methane emissions from cattle, sheep, goats, and buffalo. Rising global commitments under the Global Methane Pledge, expanding corporate net-zero targets across the dairy and beef supply chain, and mounting regulatory pressure on agricultural greenhouse gas output continue to broaden demand for validated mitigation technology. Livestock farmers, feed manufacturers, and an expanding base of food and beverage companies rely on these solutions to demonstrate measurable emissions reductions across their supply chains. Sustained growth is being shaped by accelerating regulatory clearance activity, growing carbon market participation, and rising government research funding, reinforcing this market's position within the broader climate-smart agriculture industry.
By 2024, dsm-firmenich's Bovaer feed additive had achieved regulatory approval across more than 55 countries, including Australia, Brazil, and European Union member states. The company stated that the additive reduces enteric methane emissions by an average of 30% in dairy cattle and up to 45% in beef cattle.
To Get more information On Ruminant Methane Reduction Market - Request Free Sample Report
Ruminant Methane Reduction Market Trends
-
Growing regulatory clearance activity accelerating commercial rollout of methane-inhibiting feed additives.
-
Rising corporate participation in voluntary carbon markets tied to verified livestock emissions reductions.
-
Expanding research into red seaweed-derived and biotechnology-based methane mitigation compounds.
-
Increasing adoption of precision livestock farming tools supporting individualized emissions monitoring.
-
Rising government research funding supporting genetic breeding programs for lower-emitting cattle herds.
-
Growing manufacturer investment in vaccine-based approaches targeting methane-producing rumen microorganisms.
U.S. Ruminant Methane Reduction Market Overview
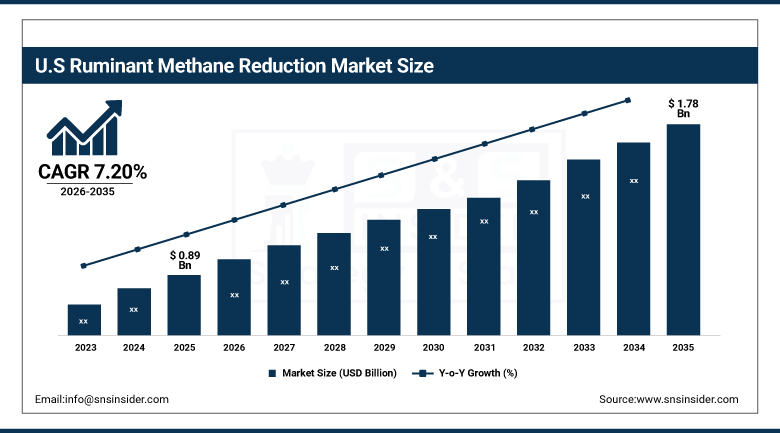
The U.S. Ruminant Methane Reduction Market was valued at USD 0.89 Billion in 2025 and is expected to reach USD 1.78 Billion by 2035, growing at a CAGR of 7.20% from 2026-2035.
The domestic demand will continue to be driven by the size of the country’s cattle herds and fast regulatory clearing for the commercial introduction of methane inhibitors to livestock feed products. The biggest players will be increasing their distribution alliances with feed mills and cooperatives, while voluntary entry into carbon markets will keep increasing amongst commercial livestock operators looking for reductions in their emissions. Federal funding for research aimed at genetic and biotechnological mitigation techniques will also contribute to the development of domestic innovation pipeline leading towards commercialization of solutions. The commitment to sustainability on the part of the dairy processors, along with academic partnerships with land grant universities, will keep building up the case for producer adoption.
On May 28, 2024, the U.S. Food and Drug Administration completed its review of Bovaer (3-NOP) and determined the product meets safety and efficacy requirements for use in lactating dairy cattle. The approval paved the way for dsm-firmenich's strategic partner Elanco Animal Health to launch the feed ingredient commercially in the United States.
Ruminant Methane Reduction Market Segment Analysis
-
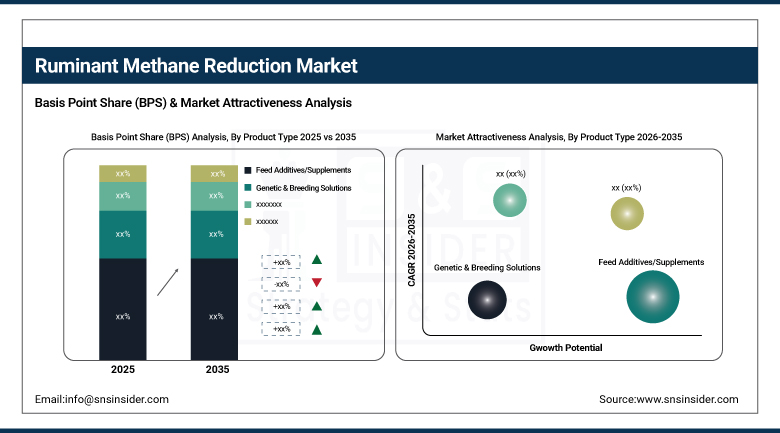
By Product Type, the Feed Additives/Supplements segment dominated the market with a 58.60% share in 2025, while the Biotechnology Solutions segment is the fastest growing with a CAGR of 9.80% during 2026-2035.
-
By Animal Type, the Cattle segment dominated the market with an 80.08% share in 2025, while the Goats segment is the fastest growing with a CAGR of 9.40% during 2026-2035.
-
By Application, the Commercial Livestock Operations segment dominated the market with a 44.50% share in 2025, while the Research & Development segment is the fastest growing with a CAGR of 9.60% during 2026-2035.
-
By End-Use, the Livestock Farmers segment dominated the market with a 41.60% share in 2025, while the Food & Beverage Companies segment is the fastest growing with a CAGR of 9.20% during 2026-2035.
By Product Type, Feed Additives/Supplements Dominates the Market and Biotechnology Solutions Grows Fastest
Feed Additives/Supplements dominated the market in 2025, a position built on their proven effectiveness, ease of integration into existing feeding routines, and immediate measurable impact on methane output from the moment of first administration. Livestock producers favour this product category precisely because it delivers a consistent, well-documented reduction in enteric methane without requiring changes to herd genetics, breeding programs, or farm infrastructure, a combination that continues to make feed additives the default entry point for producers pursuing verified emissions reductions. This everyday practicality, spanning small family farms through large industrial feedlots, keeps feed additives central to methane mitigation strategy across virtually every livestock operation type worldwide, sustaining recurring procurement even as newer product categories continue to expand around it.
Biotechnology Solutions, including vaccine-based and microbiome-targeting approaches, are projected to be the fastest-growing product category over the forecast period. Researchers and livestock producers increasingly favour these emerging technologies for their potential to deliver longer-lasting or even permanent methane reduction relative to daily feed additive administration, while continued advancement in rumen microbiome science keeps expanding the range of viable biological intervention points. As venture capital and government research funding continue flowing into this category, biotechnology solutions continue to pull ahead of more established product types in overall percentage growth even as feed additives retain the larger overall commercial deployment base.
By Animal Type, Cattle Dominates the Market and Goats Grows Fastest
Cattle dominated the market in 2025. The sheer scale of the global cattle population, combined with cattle's outsized contribution to overall livestock methane emissions relative to other ruminant species, continues to anchor this segment's leading position across the broader animal type mix. Dairy and beef cattle operations alike continue to represent the primary commercial target for methane mitigation solution developers, given both the scale of emissions involved and the relative ease of integrating feed additives into established, closely managed cattle feeding routines across commercial dairy and feedlot operations worldwide.
Goats are expected to be the fastest-growing animal type category over the forecast period. Increasing awareness of the environmental impact of methane emissions from smaller ruminant species, combined with growing interest in extending validated mitigation technology beyond cattle-focused applications, continues to drive research and commercial interest in this previously underserved segment. As mitigation technology developers increasingly adapt cattle-focused solutions for smaller ruminant physiology, goats continue to close the gap with more established animal type categories in overall market demand.
By Application, Commercial Livestock Operations Dominates the Market and Research & Development Grows Fastest
Commercial Livestock Operations dominated the market in 2025. Large-scale dairy and beef production facilities continue to represent the most economically attractive deployment context for methane mitigation solutions, given both the scale of emissions involved and these operations' greater capacity to absorb the incremental cost of feed additives or biotechnology-based interventions. This foundational commercial role continues to sustain commercial operations as the largest application category by a clear margin, even as research and development applications continue gaining ground as government and university-led validation programs expand across the broader mitigation technology pipeline.
Research & Development applications are projected to expand fastest over the forecast period. Growing government and university investment in validating emerging mitigation technologies, spanning vaccine-based approaches through genetic breeding programs, continues to expand the pool of technically promising solutions moving toward eventual commercial deployment. As implant registries and emissions verification protocols continue maturing across major markets, research and development applications continue closing the gap with commercial operations in overall market demand.
By End-Use, Livestock Farmers Dominates the Market and Food & Beverage Companies Grows Fastest
Livestock Farmers dominated the market in 2025. Direct on-farm adoption of feed additives and management practices continues to represent the most immediate and widespread pathway for achieving measurable methane reductions, given farmers' direct control over daily feeding routines and herd management decisions. This direct adoption pathway, spanning small family operations through large industrial livestock enterprises, continues to sustain farmers as the clear leading end-use category across the broader market.
Food & Beverage Companies are expected to be the fastest-growing end-use category over the forecast period. Mounting corporate net-zero commitments and Scope 3 emissions reporting requirements continue pulling major dairy and meat processing companies directly into methane mitigation procurement decisions, as these companies increasingly require verified emissions reductions from their supply chain partners. This structural shift toward corporate-driven procurement is expected to continue reshaping end-use demand patterns well beyond the current forecast horizon.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
79.40% |
|
Europe |
Germany |
29.80% |
|
Asia Pacific |
China |
35.60% |
|
Latin America |
Brazil |
48.90% |
|
Middle East & Africa |
South Africa |
35.20% |
North America Ruminant Methane Reduction Market Insights
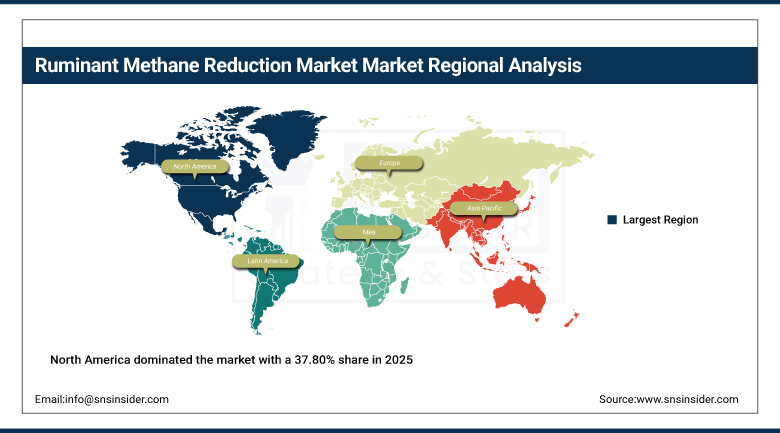
North America dominated the market with a 37.80% share in 2025. Robust research and development initiatives, the presence of major key players with advanced manufacturing capabilities, and the availability of financial incentives and support mechanisms for methane reduction projects continue to anchor this leadership position across both dairy and beef cattle operations. Voluntary carbon market participation keeps extending well beyond flagship commercial operations into mid-sized family farms, as producers and processors alike grow increasingly comfortable integrating verified emissions reductions into their business models, reinforcing the region's position at the technological forefront of this industry.
Canada contributes steady incremental demand as its dairy and beef sectors continue widening adoption of validated mitigation technology across both large-scale and family-owned operations. Continued investment in biotechnology-based solutions and genetic breeding programs across the broader region is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets that continue building out livestock emissions mitigation infrastructure from a considerably smaller existing base.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Ruminant Methane Reduction Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 9.50% during 2026-2035, supported by escalating livestock emissions, expanding government climate commitments, and growing public awareness of agriculture's contribution to greenhouse gas output across an enormous and rapidly expanding livestock population base. China continues to anchor regional demand as government agencies expand agricultural emissions monitoring capability across both established dairy regions and rapidly developing livestock production zones, supported by sustained government investment in modernising the country's broader agricultural sustainability infrastructure.
India's expanding dairy sector and rising government climate commitments continue adding meaningful regional growth as domestic researchers extend mitigation technology validation into previously underserved livestock populations. Australia and New Zealand contribute further depth through established, technically advanced agricultural research systems, with regional developers notably active in biotechnology-based and seaweed-derived mitigation compound development, positioning the wider region to sustain the fastest percentage growth of any global market through 2035.
Europe Ruminant Methane Reduction Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established feed additive manufacturers and continued advancement in regulatory frameworks supporting early product authorization. Germany's substantial dairy and feed manufacturing base anchors regional demand, supported by a well-developed agricultural policy framework that continues to favour early adoption of next-generation methane mitigation technology across both large-scale and family-owned farming operations throughout the country and neighbouring markets.
The United Kingdom, France, and other major European markets contribute consistent demand as national agricultural policy frameworks keep extending emissions reduction incentives into routine farming practice. Continued consumer awareness campaigns and dairy processor sustainability commitments across the region keep informing farmer adoption decisions, reflecting the region's role as both an established regulatory pioneer and a mature, steadily growing end market for methane mitigation technology.
MEA & Latin America Ruminant Methane Reduction Market Insights
Latin America's market is anchored by Brazil, where a sizeable domestic cattle herd and growing export market access requirements continue to sustain steady mitigation technology demand across both large-scale commercial ranching operations and smaller family farms. Argentina contributes further incremental growth as beef export markets increasingly require verified sustainability credentials, positioning the broader region as an increasingly important adoption market for validated methane mitigation solutions.
The Middle East & Africa market is supported by growing agricultural development investment across South Africa and Gulf Cooperation Council markets, where rising government climate commitments continue to lift interest in modern livestock emissions mitigation technology across both commercial and smallholder farming operations. Regional governments continue channeling growing investment into agricultural sustainability programs, including dedicated research initiatives designed to adapt mitigation technology for regional livestock breeds and farming conditions.
Growth Drivers: Climate Commitments and Corporate Sustainability Pressure
Growing awareness about climate change and the need for ruminant methane reduction stands as the primary growth driver, reinforced by expanding government financial incentives, rising corporate net-zero commitments, and growing rates of consumer demand for sustainably produced dairy and beef products worldwide. More than 100 countries have recognized methane reduction as among the most effective near-term strategies for limiting global warming, a commitment that continues to underpin sustained long-term demand as this policy consensus translates directly into expanding regulatory support across both developed and emerging agricultural systems alike.
Rising research and development investment by government agencies and market players represents a second major driver, supported by growing recognition that cost-effective and efficient mitigation solutions remain essential to achieving sector-wide emissions targets. Increasing prevalence of voluntary carbon market participation, paired with rising demand for verified emissions reduction credentials among food and beverage companies, continues to reinforce sustained market expansion across both established Western agricultural systems and rapidly developing markets.
Restraints: Producer Adoption Costs and Consumer Perception Concerns
Incremental feed additive and technology costs remain a genuine restraint on market growth, as the ongoing per-animal expense of methane mitigation solutions continues to command a meaningful share of margin-sensitive livestock operation budgets, particularly for smaller family farms operating with tighter capital constraints. This cost barrier particularly affects producers in emerging markets, where the incremental investment required for the most validated available solutions can meaningfully exceed what many smallholder operations can reasonably allocate toward emissions mitigation in any given production cycle.
Consumer perception concerns present a further restraint, as public backlash surrounding certain feed additive trials has demonstrated that skepticism toward synthetic livestock interventions can meaningfully complicate producer and processor adoption decisions despite favourable underlying safety and efficacy data. This requires manufacturers to sustain substantial ongoing public communication investment, spanning consumer education campaigns, transparent labeling practices, and third-party safety validation that can meaningfully affect commercial rollout timelines.
Opportunities: Biotechnology Innovation and Carbon Market Expansion
Continued advancement of biotechnology-based mitigation solutions, spanning vaccine-based approaches through microbiome-targeting compounds, offers a substantial opportunity, as developers securing regulatory clearance for tools delivering longer-lasting methane reduction stand to capture meaningful new demand from producers seeking to reduce daily administration burden. Livestock producers increasingly view these technologies not as a novelty feature but as a genuine operational necessity capable of delivering measurable emissions reductions while reducing daily management complexity relative to conventional feed additive administration.
The continued expansion of voluntary and compliance carbon markets presents a further avenue for growth, as verified livestock emissions reductions increasingly translate into direct revenue opportunities for participating producers. This economic pathway continues to lower the effective net cost of adoption for livestock operations while giving mitigation technology developers a genuine commercial differentiator relative to solutions lacking robust third-party emissions verification.
Recent Developments
-
In January 2024, Rumin8, an Australian climate technology company, opened its manufacturing demonstration plant in Perth, Western Australia, to refine production processes for its methane-reducing feed and water additive technology.
-
In September 2024, CH4 Global and Blue Ocean Barns secured significant funding to expand commercial-scale Asparagopsis seaweed cultivation across facilities in Australia and Hawaii.
-
In 2024, Symbrosia reported that its SeaGraze algae-based feed additive achieved a 77% reduction in methane emissions during a trial with Parker Ranch in Hawaii, supported in part by a USDA grant exceeding USD 1.2 million.
-
In 2024, ArkeaBio reported early trial results for its prototype vaccine, demonstrating a 13% reduction in methane emissions from cattle across an initial ten-animal study cohort.
Ruminant Methane Reduction Companies are:
-
Cargill, Incorporated
-
Yara International ASA
-
Evonik Industries AG
-
Land O'Lakes, Inc.
-
Koninklijke DSM N.V. (dsm-firmenich)
-
Alltech, Inc.
-
Elanco Animal Health Incorporated
-
Zoetis Inc.
-
Archer-Daniels-Midland Company
-
Blue Ocean Barns, Inc.
-
Mootral SA
-
ArkeaBio Corp.
-
Rumin8 Ltd.
-
Symbrosia, Inc.
-
Volta Greentech AB
-
CH4 Global, Inc.
-
Zelp Ltd.
-
Fonterra Co-operative Group Limited
Ruminant Methane Reduction Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.95 Billion |
| Market Size by 2035 | USD 5.91 Billion |
| CAGR | CAGR of 7.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Feed Additives/Supplements, Genetic & Breeding Solutions, Management Practices, and Biotechnology Solutions) • by Animal Type (Cattle, Sheep, Goats, and Buffalo) • by Application (Commercial Livestock Operations, Small & Medium Farms, and Research & Development) • by End-Use (Livestock Farmers, Feed Manufacturers, Food & Beverage Companies, and Government & Research Institutions) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Cargill, Incorporated, Yara International ASA, Evonik Industries AG, Land O'Lakes, Inc., Koninklijke DSM N.V. (dsm-firmenich), Nutreco N.V., Alltech, Inc., Elanco Animal Health Incorporated, Zoetis Inc., Archer-Daniels-Midland Company, Blue Ocean Barns, Inc., Mootral SA, ArkeaBio Corp., Rumin8 Ltd., Hoofprint Biome, Symbrosia, Inc., Volta Greentech AB, CH4 Global, Inc., Zelp Ltd., Fonterra Co-operative Group Limited |

Frequently Asked Questions
Key players include Cargill, Yara International, Evonik Industries, Land O'Lakes, dsm-firmenich, Nutreco, Alltech, Elanco Animal Health, Zoetis, and Archer-Daniels-Midland, among others.
Continued advancement of biotechnology-based mitigation solutions and the continued expansion of voluntary and compliance carbon markets represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by growing awareness about climate change and rising government financial incentives, combined with expanding corporate net-zero commitments across the dairy and beef supply chain.
By Animal Type, Cattle dominated the market with an 80.08% share in 2025, reflecting the scale of the global cattle population and its outsized contribution to livestock methane emissions.
North America dominated the market with a 37.80% share in 2025, supported by robust research and development initiatives and the presence of major key players with advanced manufacturing capabilities.
