
Sciatica Treatment Market Report Scope & Overview:
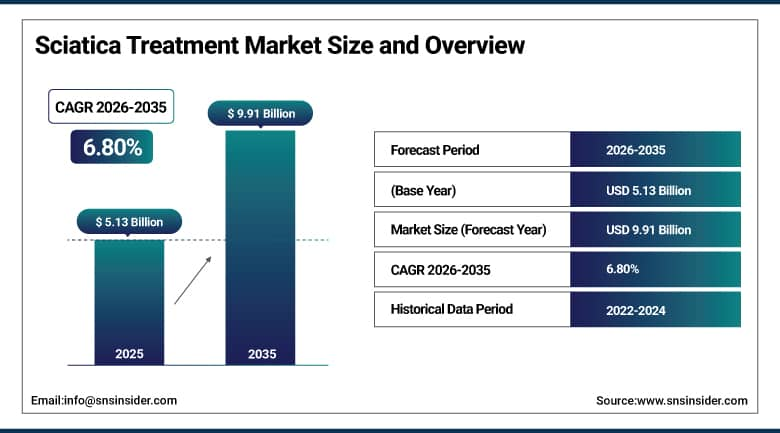
The Sciatica Treatment Market was valued at USD 5.13 Billion in 2025 and is expected to reach USD 9.91 Billion by 2035, growing at a CAGR of 6.80% from 2026-2035.
Sciatica treatment is a wide-ranging field of pain treatment that includes anti-inflammatory drugs and neuropathic drugs, epidural treatment and transdermal therapy, physical therapy and rehabilitation, minimally invasive procedures and surgery. Sciatica treatment aims at alleviating the pain caused by the sciatic nerve, which usually occurs due to disc herniation or spinal stenosis. The incidence of increasing number of sedentary lifestyle, obesity and spine degeneration along with ageing demographics and increased knowledge about the availability of treatment is constantly widening the pool of patients requiring treatment. These treatments are offered by hospitals, pain management centers, physiotherapy centers and retail pharmacies for both acute and chronic forms of sciatica. Growth in this sector is driven by the development of non-opioid drugs, targeted injectable and image-guided minimally invasive procedures.
On January 30, 2025, the U.S. FDA approved Vertex Pharmaceuticals' Journavx (suzetrigine), a first-in-class Nav1.8 sodium channel blocker for moderate-to-severe acute pain. Vertex also reported Phase 2 results in painful lumbosacral radiculopathy in December 2024, and a Phase 3 study in that condition was underway.
To Get More Information On Sciatica Treatment Market - Request Free Sample Report
Sciatica Treatment Market Trends:
-
Growing development of non-opioid analgesics targeting pain pathways such as the Nav1.8 sodium channel.
-
Rising interest in preservative-free corticosteroid formulations designed specifically for epidural use.
-
Expanding use of minimally invasive intradiscal and image-guided procedures for herniated lumbar discs.
-
Increasing adoption of transdermal and topical delivery to reduce systemic exposure to pain medicines.
-
Rising use of radiofrequency ablation and other interventional techniques for chronic radicular pain.
-
Growing emphasis on early imaging and personalized care pathways supported by artificial intelligence.
U.S. Sciatica Treatment Market Overview:
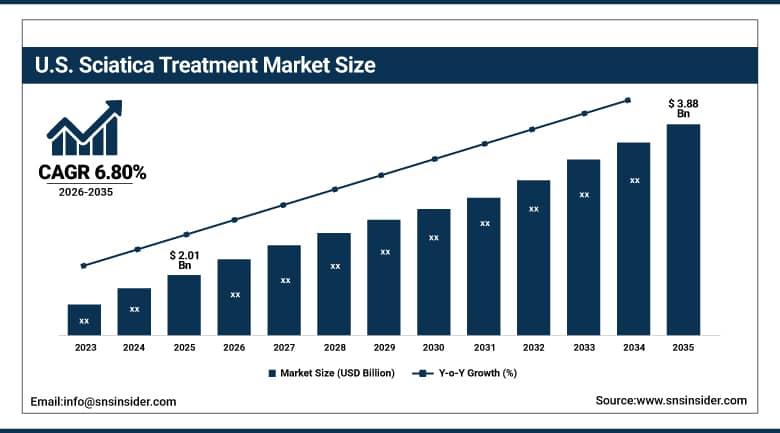
The U.S. Sciatica Treatment Market was valued at USD 2.01 Billion in 2025 and is expected to reach USD 3.88 Billion by 2035, growing at a CAGR of 6.80% from 2026-2035.
The U.S. Sciatica Treatment Market is growing steadily, driven by a high prevalence of lumbar disc disease, an ageing population, and widespread reliance on physician-directed pain management. Millions of Americans are affected by lumbar disc herniation each year, and treatment currently ranges from conservative care and epidural steroid injections to surgery. Pharmaceutical and device developers are pursuing new options in the country, including non-opioid analgesics, the first corticosteroid formulated specifically for epidural use, and minimally invasive intradiscal therapies moving into pivotal trials. Strong reimbursement, a large interventional pain physician community, and heightened concern about opioid use further support demand for alternatives, positioning the U.S. as the largest contributor to global revenue throughout the forecast period and keeping it at the center of new product introductions.
In May 2025, Scilex Holding Company presented an analysis at the 27th Annual Meeting of the American Society of Interventional Pain Physicians in Orlando on the clinical meaningfulness of SP-102 (SEMDEXA) for lumbosacral radicular pain. If approved, SP-102 would be the first corticosteroid approved for epidural injection.
Sciatica Treatment Market Segment Analysis:
-
By Drug Class, the NSAIDs segment dominated the market with a 39.47% share in 2025, while the Corticosteroids segment is the fastest growing with a CAGR of 7.90% during 2026-2035.
-
By Type, the Chronic Sciatica segment dominated the market with a 54.05% share in 2025, while the Acute Sciatica segment is the fastest growing with a CAGR of 9.92% during 2026-2035.
-
By Route of Administration, the Oral segment dominated the market with a 57.10% share in 2025, while the Transdermal segment is the fastest growing with a CAGR of 9.90% during 2026-2035.
-
By Non-Pharmacological Modality, the Physical & Exercise Therapy segment dominated the market with a 34.20% share in 2025, while the Radiofrequency Ablation segment is the fastest growing with a CAGR of 10.60% during 2026-2035.
By Drug Class, NSAIDs Dominates the Market and Corticosteroids Grows Fastest
NSAIDs dominated the market in 2025, a position built on their wide availability, low cost, and established first-line role in relieving the inflammation and pain associated with sciatica. Physicians favour these drugs precisely because they are familiar, available over the counter and by prescription, and considered safer than opioids for short-term use, a combination that keeps NSAIDs the default choice for patients presenting with acute leg and back pain, even as more targeted therapies continue to expand around them and attract growing clinical attention.
Corticosteroids are projected to be the fastest-growing drug class over the forecast period. Their potent anti-inflammatory effect makes them central to managing nerve root inflammation, particularly through epidural injection, and new formulations designed specifically for epidural use, including preservative-free gels, are addressing long-standing safety concerns. As physicians seek effective options that reduce reliance on opioids and as interventional pain practices expand, corticosteroids continue to close the gap with NSAIDs in overall market demand.
By Type, Chronic Sciatica Dominates the Market and Acute Sciatica Grows Fastest
Chronic Sciatica dominated the market in 2025. Patients whose symptoms persist beyond several weeks require ongoing management through repeated medication, injections, physiotherapy, and sometimes procedures, generating far more cumulative spending than short-lived episodes. This long treatment duration, together with the tendency of underlying disc and spinal conditions to recur, continues to sustain chronic cases as the largest type category across the broader market.
Acute Sciatica is expected to be the fastest-growing type over the forecast period. Faster imaging, including tools supported by artificial intelligence, is directing patients toward early intervention rather than prolonged watchful waiting, and new non-opioid analgesics are aimed at short-term severe pain. As early treatment pathways develop and patients seek prompt relief, acute presentations continue to close the gap with chronic cases in overall market demand.
By Route of Administration, Oral Dominates the Market and Transdermal Grows Fastest
Oral administration dominated the market in 2025. Tablets and capsules are convenient, familiar to prescribers, and supported by a large portfolio of generic NSAIDs, muscle relaxants, and neuropathic agents, making oral therapy the simplest first step for most patients. Established prescribing habits and easy access through retail and hospital pharmacies continue to sustain the oral route as the largest category across the broader market.
Transdermal delivery is projected to expand fastest over the forecast period. Patches and topical formulations deliver medicine locally or steadily while reducing systemic exposure and gastrointestinal or sedative side effects, which appeals to older patients and those on multiple medications. As developers formulate topical versions of neuropathic and anti-inflammatory agents and as patients prefer non-oral options, transdermal products continue to close the gap with oral therapy in overall market demand.
By Non-Pharmacological Modality, Physical & Exercise Therapy Dominates the Market and Radiofrequency Ablation Grows Fastest
Physical & Exercise Therapy dominated the non-pharmacological market in 2025. Guidelines recommend structured exercise, stretching, and manual therapy as first-line care, and most patients are referred to physiotherapy early in their treatment. Its low risk, broad availability, and role in preventing recurrence continue to sustain physical therapy as the largest modality category across the broader market.
Radiofrequency Ablation is expected to be the fastest-growing modality over the forecast period. Improved patient selection and growing outcome data are supporting its use for chronic radicular and spinal pain that has not responded to conservative treatment, offering longer-lasting relief than injections without the risks of surgery. As interventional pain practices expand, radiofrequency ablation continues to close the gap with conventional therapy in overall market demand.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
88.60% |
|
Europe |
Germany |
26.40% |
|
Asia Pacific |
China |
38.20% |
|
Latin America |
Brazil |
51.60% |
|
Middle East & Africa |
South Africa |
31.40% |
North America Sciatica Treatment Market Insights
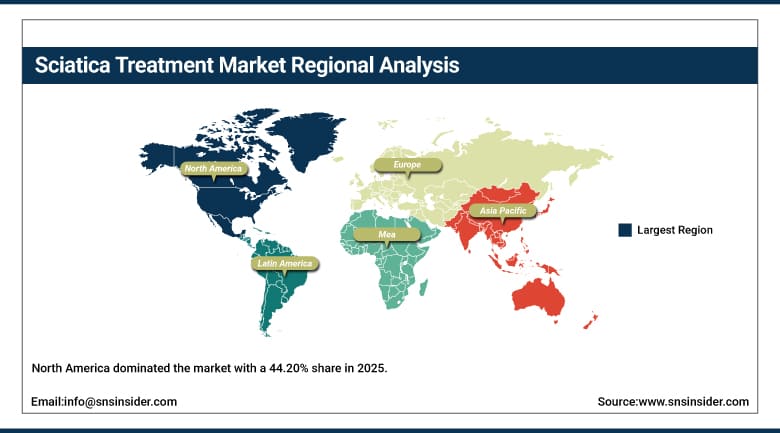
North America dominated the market with a 44.20% share in 2025. Advanced treatment options, high healthcare spending, a large population with lumbar disc disease, and a well-developed interventional pain community continue to anchor this leadership position. The United States shapes regional demand through its concentration of pharmaceutical and device developers and frequent prescription of NSAIDs, corticosteroids, and injectable therapies.
Canada contributes additional regional volume through provincial health programs and growing use of physiotherapy and interventional procedures. Continued innovation in non-opioid drugs and minimally invasive procedures is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets with ageing populations.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Sciatica Treatment Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 8.40% during 2026-2035, supported by rapidly ageing populations, urbanization with sedentary work patterns, and widening access to spine and pain care. China anchors regional demand as its share of global sciatica revenue rises steadily with expanding hospital capacity and growing use of both pharmacological and rehabilitative treatments.
Japan contributes depth through advanced spine care and a very high proportion of older adults, while South Korea, India, and Australia add growth through improving insurance coverage and awareness. Together these markets position the wider region to sustain the fastest percentage growth of any global market through 2035.
Europe Sciatica Treatment Market Insights
Europe holds a meaningful share of the global market, underpinned by an ageing population, universal health coverage, and strong physiotherapy and rehabilitation traditions. Germany anchors regional demand through high volumes of spinal procedures and pharmaceutical use, and regulators are reviewing new intradiscal treatments and biologic options for lumbar disc herniation.
The United Kingdom, France, Italy, and Spain contribute consistent demand as health systems emphasize conservative management before surgery and extend access to injections and interventional procedures. Rising awareness and steady demographic pressure are expected to support stable regional growth through the forecast period.
MEA & Latin America Sciatica Treatment Market Insights
Market in Latin America is dominated by Brazil, accounting for most of the demand owing to increased urbanization and sedentary jobs and also the rise in private care. Mexico and Argentina contribute to additional volume, but limited availability of interventional pain procedures and cost sensitivity will keep them favoring oral generic medicines.
In Middle East & Africa, there is a growth of the market from a low base level, wherein the demand emanates from GCC countries owing to increased investments being made into orthopedic and pain management therapies. South Africa is the demand driver in Africa owing to the relatively advanced private healthcare sector and physiotherapy availability.
Market Dynamics:
Growth Drivers: Rising Sciatica Prevalence and Treatment Demand
The rising prevalence of sciatica represents the primary growth driver, reinforced by sedentary lifestyles, obesity, and spinal degeneration in an ageing population that increase the incidence of disc herniation and spinal stenosis. A large global patient pool, and the fact that many cases become chronic, sustain recurring demand for medicines, injections, rehabilitation, and procedures.
Growing demand for effective non-opioid options provides a second major driver. Concern about opioid risks is pushing prescribers toward NSAIDs, targeted injectables, topical therapies, and new drug classes, while rising numbers of prescriptions and heightened awareness encourage earlier treatment. Investment in research and partnerships by leading companies further widens the pipeline of options.
Restraints: Mixed Trial Outcomes and Side Effect Concerns
Mixed clinical trial outcomes remain a genuine restraint on market growth. Sciatica trials are prone to strong placebo responses, and several promising candidates have shown only modest advantages, as illustrated by a Phase 2 study in painful lumbosacral radiculopathy in which the drug and placebo groups showed similar pain reductions, prompting the need for larger, better-controlled studies.
Side effect and safety concerns present further restraints. Long-term NSAID use carries gastrointestinal and cardiovascular risks, opioids carry dependence risk, and off-label epidural steroid products have been linked to safety warnings, especially when they contain preservatives or particles. Regulatory hurdles and uncertain reimbursement for novel therapies can slow the introduction of new treatments.
Opportunities: Targeted Injectables and Minimally Invasive Procedures
Targeted injections represent an enormous opportunity because of the ability to create specific epidural steroids and other drugs that would be used to treat pain where there is no drug on the market. For companies that will show efficacy and safety in their big trials, there is a chance to gain the trust of physicians amid the increasing need for alternative treatment to opioids and surgeries.
Minimally invasive and image-guided procedures offer another path to grow in this space. The direct targeting of herniated disc or nerves by intradiscal injections, percutaneous decompressions and ablations is what fills the void between non-surgical options and surgery. The granting of breakthrough designation and pivotal trials in this field proves increasing interest from investors and clinicians.
Recent Developments:
-
2025, MIRA Pharmaceuticals announced the successful formulation of Ketamir-2 into a topical treatment for localized neuropathic and inflammatory pain.
-
2025, Stayble Therapeutics was running a trial of STA363, an intradiscal injection of lactic acid, in patients with sciatica caused by lumbar disc herniation.
-
2026, Seikagaku Corporation announced the resubmission of its biologics license application for condoliase (SI-6603) to the U.S. FDA for lumbar disc herniation, addressing issues raised in a prior Complete Response Letter.
-
2026, SpinaFX Medical announced that the FDA had granted an Investigational Device Exemption for a pivotal trial of Triojection, an intradiscal ozone and oxygen treatment, following a Breakthrough Device Designation in August 2025.
Sciatica Treatment Market Key Players:
-
Endo International plc
-
Johnson & Johnson
-
Pfizer Inc.
-
Abbott Laboratories
-
Bayer AG
-
Novartis AG
-
GlaxoSmithKline plc
-
Bristol Myers Squibb Company
-
Scilex Holding Company
-
Vertex Pharmaceuticals Incorporated
-
Medtronic plc
-
Boston Scientific Corporation
-
Stryker Corporation
-
Globus Medical, Inc.
-
Nevro Corp.
-
Hisamitsu Pharmaceutical Co., Inc.
-
Grunenthal GmbH
-
Viatris Inc.
-
Sun Pharmaceutical Industries Ltd.
-
Teva Pharmaceutical Industries Ltd.
Sciatica Treatment Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.13 Billion |
| Market Size by 2035 | USD 9.91 Billion |
| CAGR | CAGR of 6.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Drug Class (NSAIDs, Corticosteroids, Anticonvulsants, Opioids, and Others) • By Type (Acute Sciatica and Chronic Sciatica) • By Route of Administration (Oral, Transdermal, and Injectable) • By Non-Pharmacological Modality (Physical & Exercise Therapy, Radiofrequency Ablation, Surgery, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Endo International plc, Johnson & Johnson, Pfizer Inc., Abbott Laboratories, Bayer AG, Novartis AG, GlaxoSmithKline plc, Bristol Myers Squibb Company, Scilex Holding, Company, Vertex Pharmaceuticals Incorporated, Medtronic plc, Boston Scientific Corporation, Stryker Corporation, Globus Medical, Inc., Nevro Corp., Hisamitsu Pharmaceutical Co., Inc., Grunenthal GmbH, Viatris Inc., Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd. |

Frequently Asked Questions
Key players include Endo International, Johnson & Johnson, Pfizer, Abbott, Bayer, Novartis, GlaxoSmithKline, Bristol Myers Squibb, Scilex Holding Company, and Vertex Pharmaceuticals, among others.
The development of targeted injectables for radicular pain and the expansion of minimally invasive, image-guided procedures represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by the rising prevalence of sciatica in an ageing, increasingly sedentary population, combined with growing demand for effective non-opioid treatment options.
By Drug Class, NSAIDs dominated the market with a 39.47% share in 2025, reflecting their wide availability, low cost, and established first-line role in relieving sciatica pain.
North America dominated the market with a 44.20% share in 2025, supported by advanced treatment options, high healthcare spending, and a large interventional pain community, led by the United States.
