
Security Automation Market Report Scope & Overview:
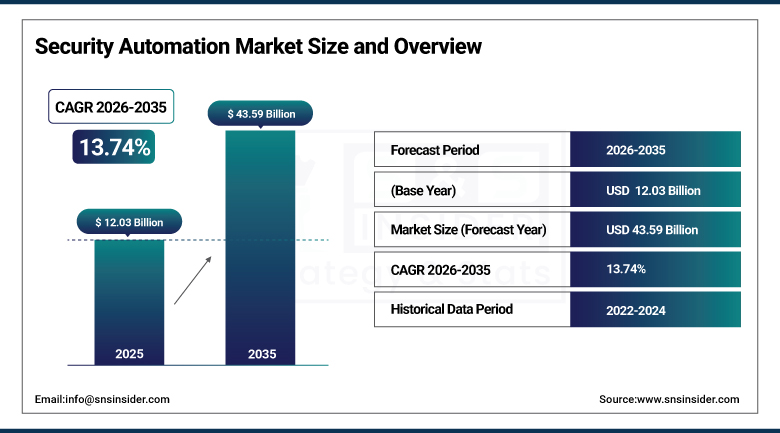
The Security Automation Market was valued at USD 12.03 Billion in 2025 and is estimated at USD 13.68 Billion in 2026. It is projected to reach USD 43.59 Billion by 2035, registering a compound annual growth rate (CAGR) of 13.74% from 2026 to 2035. Growing alert volumes, mandatory incident reporting deadlines, and a persistent shortage of security staff are moving organizations from manual triage toward orchestrated and artificial intelligence (AI) driven response. Vendors are also adding autonomous agents to widen coverage.
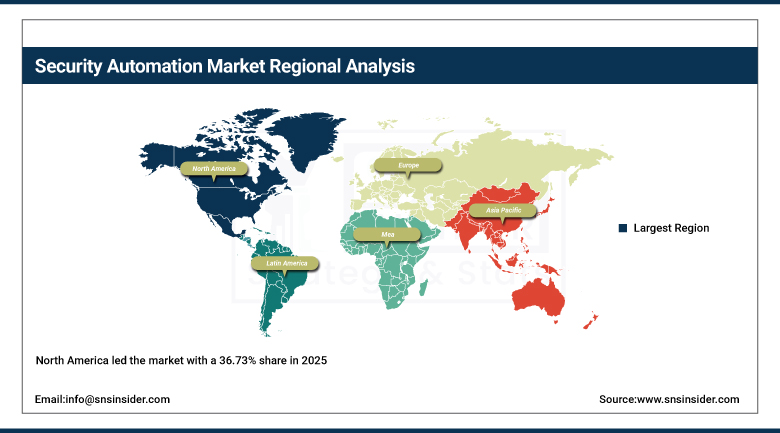
North America commanded the highest market share of 36.73% in 2025, owing to the rapid adoption of security operations platforms, stringent disclosure policies, and a high number of vendors. The second highest share comes from Europe due to the rising focus on resilience of operations and network security laws. Asia Pacific will be the fastest-growing region until 2035 due to the increasing use of digital services and cloud services and disclosure laws in China, India, and Southeast Asian countries. Latin America and the Middle East & Africa are relatively smaller but growing regions.
To Get more information Security Automation Market - Request Free Sample Report
Key Report Takeaways
-
By component, solutions held a 64.37% share in 2025, while services are the fastest growing.
-
By deployment, cloud held a 62.41% share in 2025, while on-premises is the fastest growing.
-
By application, endpoint security held a 30.46% share in 2025, while incident response management is the fastest growing.
-
By industry vertical, BFSI held a 27.64% share in 2025, while healthcare and life sciences is the fastest growing.
-
By region, North America held a 36.73% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
-
Security operations teams are adding autonomous AI agents that triage alerts, enrich evidence, and run response playbooks.
-
Vendors are merging orchestration, detection, and case management into single security operations platforms.
-
No-code and low-code workflow builders are widening automation use beyond specialist engineers.
-
Exposure management and vulnerability remediation are being tied directly to automated ticketing and patching.
-
Governance controls for AI-driven actions, including approval gates and audit trails, are becoming standard features.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Rising alert volumes and cost of incident response |
+4.38% |
North America, Europe |
Short term (2 years or less) |
|
Mandatory incident reporting and resilience rules |
+3.92% |
North America, Europe, India |
Medium term (2 to 4 years) |
|
Shortage of skilled security staff |
+3.47% |
Global |
Long term (4 years or more) |
|
Adoption of agentic AI in security operations |
+3.21% |
North America, Asia Pacific |
Short term (2 years or less) |
|
Cloud and hybrid infrastructure expansion |
+2.18% |
Global |
Medium term (2 to 4 years) |
Rising Alert Volumes and the Cost of Incident Response Push Teams Toward Automation
Security teams receive thousands of alerts each day from endpoint, network, identity, and cloud tools, and most of them require repetitive checks before an analyst can decide on action. Longer dwell times and faster attacker handoffs reduce the time available to respond, which makes manual triage costly and slow. Automation platforms enrich alerts, correlate evidence, and execute containment steps in seconds, lowering response times and limiting damage from each incident. Organizations with large estates therefore treat automation as a core control.
Mandatory Incident Reporting and Resilience Rules Raise the Need for Documented Response
Regulators now set short deadlines for reporting cyber incidents, and companies need evidence that can be assembled quickly and consistently. SEC regulations have mandated public companies to disclose material cybersecurity incidents through Form 8-K filings within four business days from the materiality determination of the incident as per July 2023. An orchestration platform logs each step taken, assigns the task, and generates audit trails, which aid the compliance of legal, risk, and security teams with these deadlines. Automated evidence capture shortens the time needed to judge materiality.
Shortage of Skilled Security Staff Strengthens the Case for Automated Workflows
Finding experienced security analysts is still problematic, as most of the teams lack staff capable of working around the clock. According to ISC2, 59.00% of survey respondents stated having critical and significant skill requirements in December 2025, while in 2024, the number of such respondents was 44.00%. Thanks to the use of automated playbooks, small teams can cope with basic cases of phishing, malware, and access on their own. Senior analysts can then focus on threat hunting and complex investigations instead of ticket handling.
Adoption of Agentic AI in Security Operations Expands the Scope of Automation
Vendors are embedding AI agents that read alerts, gather context from many tools, propose or take actions, and write case summaries. These agents extend automation from fixed rules to flexible reasoning, which allows coverage of cases that earlier playbooks could not handle. Security leaders are piloting them first for investigation and enrichment, then for remediation under approval controls. As trust grows, the share of incidents handled without human intervention is expected to rise. Early deployments report quicker investigations and consistent case notes.
Cloud and Hybrid Infrastructure Expansion Multiplies Systems That Need Coordinated Response
Workloads now span public clouds, software-as-a-service applications, containers, and remote endpoints, and each environment produces its own logs and controls. Coordinating response across these systems manually is slow and error-prone. Automation platforms connect through application programming interfaces to isolate hosts, revoke tokens, change firewall rules, and open tickets in one workflow. Growth in cloud spending therefore expands the footprint that security automation must cover. Automation also keeps configurations consistent across regions, which supports audits and limits missed controls. Coverage grows with each new platform.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Integration complexity and legacy tool sprawl |
-1.38% |
Global |
Medium term (2 to 4 years) |
|
High implementation cost and tuning effort |
-0.94% |
Asia Pacific, Latin America |
Short term (2 years or less) |
|
Trust and control concerns over autonomous actions |
-0.64% |
North America, Europe |
Short term (2 years or less) |
|
Data privacy and sovereignty limits on cloud platforms |
-0.46% |
Europe, Middle East |
Long term (4 years or more) |
Integration Complexity and Legacy Tool Sprawl Slow Deployment
Many enterprises run dozens of security products from different vendors, and connecting them requires custom connectors, clean data, and maintained credentials. Legacy systems may lack modern interfaces, which forces manual steps inside otherwise automated workflows. Projects often take months before the first playbooks run in production, and ongoing maintenance consumes engineering time. Smaller organizations hesitate to start because they lack the people to build and support integrations. Vendors are therefore offering packaged connectors and certified integrations to shorten the start-up period for customers.
High Implementation Cost and Tuning Effort Limit Adoption Among Smaller Buyers
Licensing, professional services, and staff training add to the cost of an automation program, and benefits arrive only after playbooks are designed, tested, and tuned. Poorly tuned workflows can create false positives or disrupt business systems, so teams proceed cautiously. Buyers in price-sensitive markets often prioritize basic detection tools before automation, and managed service options are only beginning to reach them in volume. Managed service options and prebuilt playbook libraries are reducing this burden, although buyers still need budget for tuning and periodic testing of workflows.
Trust and Control Concerns Over Autonomous Actions Create Caution
It is a major concern for security leaders to ensure that an automated decision such as quarantining the server or disabling accounts may not cause any disruption of essential services if the decision itself turns out to be faulty. This concern is heightened in view of the opaque nature of the AI decision-making process, particularly in the context of regulated industries, where any action has to be justifiable to auditors. While vendors are introducing features such as approvals, simulations, and logging, most organizations only automate non-critical processes.
Data Privacy and Sovereignty Limits on Cloud Platforms Restrict Deployment Choices
Security automation platforms handle logs, identities, and case data that may contain personal information, and some jurisdictions restrict where such data can be processed. Government, defense, and financial buyers often require local hosting or on-premises operation, which increases cost and reduces access to shared threat intelligence. Vendors are opening regional data centers and sovereign options, but approval processes lengthen sales cycles. Sovereign cloud regions and customer-managed keys are easing these concerns, although approval steps remain long for public sector contracts.
Security Automation Market Segment Analysis
By Component, Solutions Dominate Security Automation Market; Services to Register Fastest Growth.
Solutions accounted for a 64.37% share in 2025 because organizations first buy the orchestration, detection, and response software that forms the automation backbone. These platforms combine case management, playbooks, threat intelligence, and integrations, and vendors sell them through subscriptions that renew each year. Large security teams standardize on a few platforms, which concentrates spending on solution licenses. Bundled threat intelligence feeds, prebuilt playbooks, and certified integrations add further value to platform licenses and make switching costly for established customers.
The Services are expected to record a CAGR of 14.76% during the forecast period of 2026 to 2035 owing to the rising demand for external assistance in the areas of integration, playbook development, and continuous monitoring from the consumers. The managed security providers automate the process for the consumers without internal capabilities. The services like consulting, training, and tuning rise in numbers as the deployments get matured and due to the governance of artificial intelligence capabilities. Fees follow usage.
By Deployment, Cloud Dominates Security Automation Market; On-Premises to Register Fastest Growth.
Cloud accounted for a 62.41% share in 2025 because most vendors deliver their platforms as services that deploy quickly, scale with alert volumes, and update without customer effort. Security teams value fast access to new integrations and shared threat data. The shift of applications and identity systems to the cloud also makes cloud-hosted automation the natural fit. Updates arrive continuously, and teams avoid hardware purchases and patching windows, which lowers the effort of running the platform. Costs stay predictable.
The on-premises segment is expected to exhibit a CAGR of 14.89% over the forecast period of 2026 to 2035, driven by the fact that the government sector, defense organizations, banks, and critical infrastructure players keep their data in controlled environments due to data residency and air-gap network requirements. Containers and private versions have been developed by vendors that replicate cloud functionality locally. Hybrid architectures link local sensors with cloud analytics, so customers can adopt automation step by step without moving every workload at once.
By Application, Endpoint Security Dominates Security Automation Market; Incident Response Management to Register Fastest Growth.
The endpoint security market was at 30.46% share in 2025 due to the fact that the use of laptops, servers, and mobile phones is still the most prevalent means by which attacks take place and create high alert levels. The automation of isolations, processes termination, and rollbacks minimizes the impact of ransomware and malware. Endpoint solutions have high integration with orchestration platforms and this allows for faster adoption. Playbooks that cover phishing mitigation, password reset, and isolation are also included in the solution, thus providing quantifiable time savings.
Incident response management is projected to register a CAGR of 15.94% from 2026 to 2035 as organizations formalize case handling, evidence collection, and reporting under new disclosure rules. Platforms that assign tasks, track service levels, and generate regulatory notifications gain budget. Integration with legal, communications, and risk teams extends the use of automation beyond the security operations center. Vendors add dashboards that track response times and open cases, which helps managers show improvement to auditors and boards. Reports are standardized.
By Industry Vertical, BFSI Dominates Security Automation Market; Healthcare and Life Sciences to Register Fastest Growth.
BFSI accounted for a 27.64% share in 2025 because banks, insurers, and payment firms face constant attacks, strict regulation, and high costs from downtime or fraud. These institutions maintain large security operations centers and invest in automation to meet supervisory expectations on resilience and reporting. Their budgets and mature processes make them early buyers of advanced platforms. Large banks also run fraud, anti-money laundering, and cyber teams that share data, which raises the value of coordinated workflows. Budgets are large.
It is estimated that healthcare and life sciences will grow at a CAGR of 15.54% between 2026 and 2035 due to digitalization of records and devices in hospitals, laboratories, and pharmaceutical firms in the face of ransomware and privacy challenges. The small security team in the industry depends on automation to manage large estate sizes. Connected medical devices and shared patient portals create many alerts, so automated triage is valuable for lean teams. Staffing is lean.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
74.58% |
|
Europe |
Germany |
22.46% |
|
Asia Pacific |
China |
31.84% |
|
Middle East & Africa |
Saudi Arabia |
28.73% |
|
Latin America |
Brazil |
51.92% |
North America Security Automation Market
North America led the market with a 36.73% share in 2025, supported by early adoption of security operations platforms, strict disclosure rules, and a dense base of vendors. The United States generated USD 3.30 Billion in 2025 and is projected to grow at a CAGR of 13.91% from 2026 to 2035. Security Operations Centers, along with orchestration, are maintained by banks, tech organizations, healthcare organizations, and government agencies. In Canada, the finance and energy industries generate more demand for orchestration. Insurance companies and energy companies generate further demand.
Regional vendors deploy new agent-based capabilities first and public companies align their incident response process with their disclosure process. Automation by managed security providers is available to middle-sized organizations unable to establish their own security operation centers. Technology vendors and cloud providers also run partner programs that train integrators in playbook design and deployment. Enterprises ask for approval gates, action logs, and role-based controls before allowing automated remediation, and pricing is increasingly based on usage.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Security Automation Market
Europe is the second biggest regional market and holds 26.84% of the share in 2025. Germany dominates this region with the UK, France, Italy, and Spain following suit. There are efforts being made by financial institutions, energy companies, and governmental bodies to improve their monitoring and reaction abilities to meet the needs of network and information security guidelines. Data privacy regulations also impact the hosting of platforms and storage of case data. Nordic and Benelux organizations embrace new security tools and industrial organizations from Central Europe contribute to the demand through plant connectivity to corporate networks.
The Digital Operational Resilience Act was introduced by the EU to all banks, insurers, and IT providers within Europe in January 2025, making it obligatory for all companies to classify, report, and test incidents. Such requirements make the demand for software that would log all response steps higher, and they encourage vendors to offer local deployment and explicit terms of data management. Cross-border organizations prefer platforms that use the same response process in various regulatory environments, while regional managed service providers automate processes in local languages. Local hosting wins.
Asia Pacific Security Automation Market
Asia Pacific is expected to record the fastest growth, at a CAGR of 15.88% from 2026 to 2035, as digital services, cloud adoption, and national reporting rules spread across the region. China is the leading country in terms of regional ownership, followed by Japan, India, Australia, and South Korea. Fast growth of online transactions and e-commerce contributes to increased attack surfaces and greater needs for automated protection. Japan and South Korea generate extra demand from major producers and telecommunication operators with extensive device fleets.
The Indian Computer Emergency Response Team provided guidance in April 2022 on reporting covered incidents within six hours and retaining logs for 180 days, which is a policy that continues to motivate the development of automated detection and reporting systems. The critical infrastructure policies in Singapore and Australia raise the bar further, and managed services providers in the region help mid-sized firms. The regional expansion of cloud computing and data localization policies has become another factor affecting platform choices, and software vendors establish data centers locally in order to win contracts in the region.
Latin America Security Automation Market
Latin America accounted for 6.78% of the market in 2025, led by Brazil, followed by Mexico, Argentina, Colombia, and Chile. Banks, telecom operators, and government agencies are the main buyers, and a rise in ransomware and payment fraud is prompting wider investment in security operations. Open banking and instant payment systems expand the number of connected services that must be monitored. Peru and Uruguay add smaller but growing demand from banks and government digital programs. Fintech growth adds further demand.
Local managed security providers often deliver automation as a service because few firms can staff round-the-clock centers. Data protection laws in Brazil and other countries are adding reporting duties, and regional cloud expansion by global providers improves access to modern platforms for mid-sized organizations. Mexico is developing nearshore security operations centers that serve North American clients, which expands the pool of trained analysts and raises demand for tools that standardize their work across customers. Partnerships with global vendors widen access.
Middle East & Africa Security Automation Market
The Middle East and Africa held a 6.68% share of the market in 2025. Gulf countries lead demand, with Saudi Arabia holding the largest national share, followed by the United Arab Emirates and Qatar. The development of national cybersecurity strategies, major digital transformation initiatives, and critical infrastructure protection results in spending on security operation centers and automation platforms. In the Gulf, telecom operators, energy companies, and airlines are growing their round-the-clock monitoring centers. The investment of sovereign wealth into tech parks is another contributor to regional security operations centers.
In terms of market development in Africa, South Africa is far ahead of other countries. Banks and telecom operators are the main drivers of security operations center adoption. In Nigeria and Kenya, an increasing number of security operations centers is seen amid the growth of mobile banking. Government programs that fund cyber skills training and national operations centers are creating a base of users, and vendors are partnering with regional integrators to localize playbooks and support. Training pipelines are slowly widening supply.
Competitive Landscape
The Security Automation Market is fragmented. Network security leaders, endpoint specialists, cloud platform companies, observability and logging vendors, and focused automation start-ups all sell orchestration and response capabilities, and no single provider holds a large share of total spending. Large vendors compete through platform breadth and data advantages, while specialists compete on flexibility, integrations, and speed of deployment.
Vendors follow three main strategic lines. First, they combine detection, orchestration, and case management into unified security operations platforms. Second, they add AI agents that investigate alerts and propose or take action under governance controls. Third, they build wide integration libraries and no-code builders so that customers can automate workflows across many tools without custom development.
Security Automation Market Industry Leaders
1. Palo Alto Networks: Offers Cortex XSOAR and the Cortex AgentiX agent platform for security orchestration and automated response.
2. IBM: Sells QRadar SOAR for orchestrated incident response and case management.
3. Fortinet: Delivers FortiSOAR and the FortiSOC platform for automated security operations.
4. Microsoft: Integrates automation into Microsoft Sentinel and Defender for security operations.
Companies Covered in this Report
-
Palo Alto Networks
-
IBM
-
Fortinet
-
Microsoft
-
Google
-
CrowdStrike
-
ServiceNow
-
Swimlane
-
Torq
-
Tines
-
Cyware
-
Sumo Logic
-
Trellix
-
D3 Security
-
Rapid7
Recent Developments
-
October 2025: Palo Alto Networks introduced Cortex AgentiX, positioned as the next generation of Cortex XSOAR, with prebuilt agents and more than 1,000 integrations.
-
October 2025: Trellix added a no-code hyperautomation workflow builder to its Helix platform for faster investigation and response.
-
January 2026: Swimlane released a fleet of AI agents and an agent builder in its Turbine platform.
-
March 2026: Fortinet previewed FortiSOC, which combines FortiSOAR with FortiAnalyzer, FortiSIEM, and its threat intelligence services.
-
March 2026: Cyware launched Agentic Fabric with an analyst agent hub and an agent catalog.
-
August 2026: ServiceNow launched six autonomous security products, including agentic incident response and unified exposure management.
-
September 2026: CrowdStrike unveiled Charlotte Agentic SOAR within a single governed automation workspace at its Fal.Con event.
Scope and Research Methodology
The study defines the Security Automation Market as software platforms and associated services that automate the detection, investigation, and response to cyber threats and the management of vulnerabilities and compliance tasks. Covered offerings include security orchestration and response solutions, automated case management, playbook engines, and professional and managed services delivered through cloud and on-premises deployments. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are expressed in USD. Stand-alone antivirus products, hardware appliances, and general information technology automation are excluded. Security information and event management products are included only where they provide orchestration or automated response functions, and managed detection services are included only where automation platforms are part of the delivery.
The research program combines secondary and primary research. Secondary research draws on company annual reports, investor presentations, regulatory filings, government advisories, trade association publications, and peer-reviewed and industry literature. Primary research consists of structured interviews and surveys with security operations leaders, chief information security officers, platform vendors, and managed service providers across the value chain. These discussions validate assumptions on adoption, pricing, and deployment mix. Interview findings are weighted by the relevance and seniority of each respondent, and conflicting inputs are checked against company disclosures, product documentation, and published government advisories.
Market engineering follows a bottom-up build from vendor revenue, customer counts, and contract values, cross-checked top-down against cybersecurity spending. The triangulation in both cases reduces the disparities prior to the fixation of values. The forecasts are dependent on the factors like incidence rates, reporting practices, and adoption of AI. The values for each region are made consistent such that the value of countries adds up to the total regional value, and every forecast is reviewed by the analyst prior to publishing. The sensitivity tests are conducted on the basis of changes in incidences, adoption rate, and regulations.
Security Automation Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 12.03 Billion |
| Market Size by 2035 | USD 43.59 Billion |
| CAGR | CAGR of 13.74% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Solutions and Services) • By Deployment (Cloud and On-Premises) • By Application (Network Security, Endpoint Security, Incident Response Management, Vulnerability Management, Identity and Access Management, Compliance and Policy Management, and Others) • By Industry Vertical (BFSI, IT and Telecom, Healthcare and Life Sciences, Manufacturing, Government and Defense, Retail and E-Commerce, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | IBM, Fortinet, Microsoft, Google, CrowdStrike, ServiceNow, Swimlane, Torq, Tines, Cyware, Sumo Logic, Trellix, D3 Security, Rapid7 |

Frequently Asked Questions
The market was valued at USD 12.03 Billion in 2025 and is projected to reach USD 43.59 Billion by 2035 at a CAGR of 13.74%.
North America led the market with a 36.73% share in 2025, supported by early adoption of security operations platforms and strict disclosure rules.
Asia Pacific is expected to grow the fastest, at a CAGR of 15.88% from 2026 to 2035.
Solutions, cloud deployment, endpoint security, and BFSI hold the largest shares in their segments.
Services, on-premises deployment, incident response management, and healthcare and life sciences are the fastest growing segments.
Major players include Palo Alto Networks, IBM, Fortinet, and Microsoft.
Integration complexity, implementation cost, trust in autonomous actions, and data sovereignty limits slow faster growth.
