
Shunt Reactor Market Report Scope & Overview:
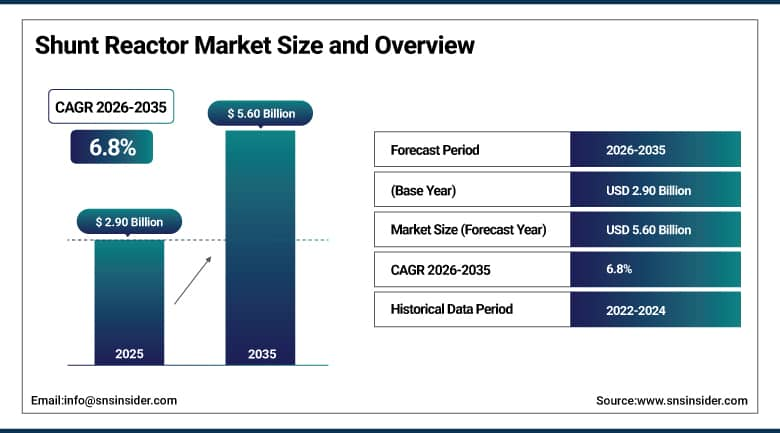
The Shunt Reactor Market was valued at USD 2.90 Billion in 2025 and is expected to reach USD 5.60 Billion by 2035, growing at a CAGR of 6.8% from 2026–2035.
Shunt reactors are used for absorbing the reactive power and ensuring the stability of the voltage on the high-voltage power transmission and distribution networks. Shunt reactors become very important in this regard as power grids start adding more and more long-distance transmission lines and variable sources of renewable energy. In addition, the constant development of transmission and distribution systems worldwide, along with the constantly increasing demand for electricity due to population growth and industrialization, results in the need for the continuous modernization of grids, making shunt reactors an increasingly necessary part of grid stability.
The growing focus of utility companies around the globe on innovations that increase voltage stability and decrease losses due to variability resulting from integration of renewable energy sources into the grid has led to the increasing importance of the use of shunt reactors. As part of their efforts to address the growing need among utility customers for sustainable product features in grid components, manufacturers are beginning to introduce sustainable changes in their products through incorporating greater levels of recycled material usage in the production of shunt reactors. While still at the initial stage of development and implementation, circular materials initiatives indicate what lies ahead as utility customers incorporate considerations of sustainable supply chains into their decisions concerning capital equipment purchases.
In May 2025, GE Vernova secured a large order to supply more than 70 units of 765 kV transformers and shunt reactors to POWERGRID in India, reflecting the scale of transmission infrastructure investment underway across rapidly electrifying Asian markets.
To Get More Information On Shunt Reactor Market - Request Free Sample Report
Shunt Reactor Market Trends
-
Rising demand for variable shunt reactors offering dynamic reactive power control amid renewable grid integration
-
Growing adoption of shunt reactors in offshore wind and submarine cable transmission applications
-
Increasing utility investment in grid modernization driving replacement of aging reactive power infrastructure
-
Rising deployment of higher-voltage reactors above 400 kV supporting long-distance transmission networks
-
Growing manufacturer focus on recycled-material content and sustainable reactor design practices
-
Expanding single-phase reactor adoption for localized reactive power compensation in space-constrained urban grids
U.S. Shunt Reactor Market Outlook
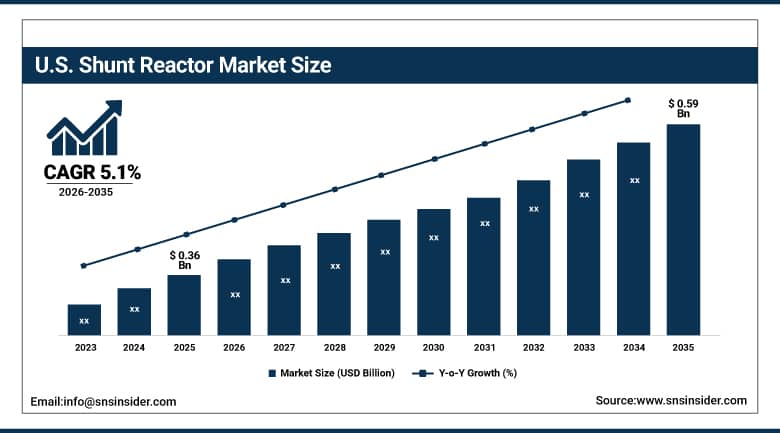
The U.S. Shunt Reactor Market was valued at approximately USD 0.36 Billion in 2025 and is expected to reach approximately USD 0.59 Billion by 2035, growing at a CAGR of approximately 5.1%.
Increased investments into grid infrastructure have been seen by the US market through various initiatives, such as GRIP program that has been carried out by Department of Energy Grid Deployment Office with the goal of increasing resilience and reliability of the power systems in the US. The initiative is estimated at USD 10.5 billion of investments into increased power system resiliency and reliability. The US Energy Information Administration expects 63 GW of new additions to utility scale generating capacity in 2025, a 30% increase compared to the estimates for 2024 year, directly supporting the demand for shunt reactor-based reactive power compensators to accommodate growing grid. Development of high voltage transmission grid built specially to connect new capacity of wind and solar generation capacity to load points will continue to be the major growth driver of the demand for shunt reactors as long distance power transmission lines need reactive power compensation for voltage stabilization in view of non-stable generation of power sources.
Shunt Reactor Market Segment Analysis
-
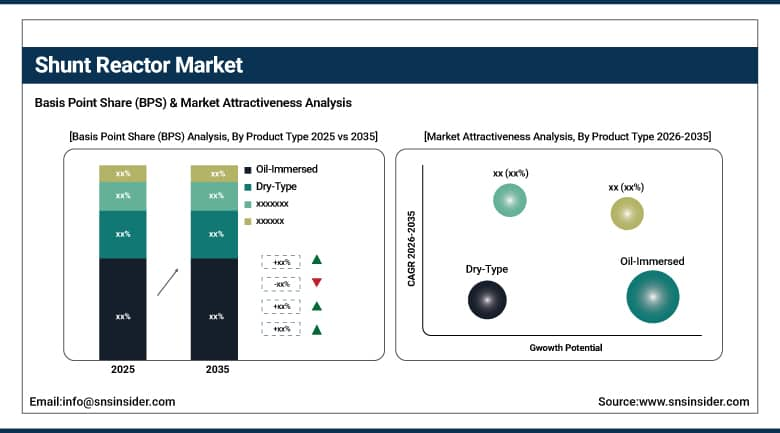
By Product Type, the Oil-Immersed segment dominated the Shunt Reactor Market with approximately 57.0% share in 2025, while the Dry-Type segment is the fastest growing with a CAGR of approximately 9.2%.
-
By Phase, the Three Phase segment dominated the Shunt Reactor Market with approximately 64.0% share in 2025, while the Single Phase segment is the fastest growing with a CAGR of approximately 8.4%.
-
By End-User, the Electric Utility segment dominated the Shunt Reactor Market with approximately 68.4% share in 2025, while the Renewable Energy segment is the fastest growing with a CAGR of approximately 9.6%.
By Product Type, Oil-Immersed dominates, Dry-Type registers the fastest growth
Oil-Immersed was the most dominant segment in the Shunt Reactor Market because of the nature of this design that involves using oil as the cooling and insulation agent that can absorb and dissipate the huge amount of heat produced by this reactor during the high voltage performance. This type of design has been found to be the most suitable for utility transmission due to its high reliability at high power ratings.
The Dry-Type shunt reactors market is the fastest growing segment in the Shunt Reactor Market because of the safety features of this design which are devoid of the fire hazards and environmental pollution risk involved in the Oil-Immersed design. There have been continued efforts of the manufacturers in developing more efficient oil formulations and oil containment systems to improve on the environmental and fire safety hazards in the oil-immersed designs despite its cooling performance benefits.
By Phase, Three Phase dominates, Single Phase registers the fastest growth
Three Phase dominated the Shunt Reactor Market in 2025 due to the fact that this configuration remains the standard specification for utility-scale transmission network reactive power compensation, offering superior efficiency and cost-effectiveness for the large majority of high-voltage grid applications where balanced three-phase power flow is the norm.
Single Phase is the fastest-growing segment in the Shunt Reactor Market due to the fact that the increasing demand for localized reactive power compensation in distribution networks favors single-phase units' suitability for lower voltage applications and ease of installation in urban environments facing space limitations that make larger three-phase installations impractical.
By End-User, Electric Utility dominates, Renewable Energy registers the fastest growth
Electric Utility dominated the Shunt Reactor Market in 2025 due to the fact that utilities remain the largest and most established consumer of reactive power compensation equipment globally, given their direct responsibility for maintaining voltage stability and power quality across transmission and distribution networks serving the full range of residential, commercial, and industrial customers.
Renewable Energy is the fastest-growing segment in the Shunt Reactor Market due to the fact that the global energy sector's swift transition toward wind, solar, and hydropower generation is introducing greater variability into grid load profiles, requiring substantially expanded reactive power compensation infrastructure to maintain grid stability as renewable penetration continues to rise. Independent power producers operating large-scale wind and solar farms increasingly specify shunt reactors directly as part of project interconnection agreements, reflecting growing recognition that reactive power compensation infrastructure investment is essential to securing grid connection approval for new renewable capacity.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
79.0% |
|
Europe |
Germany |
26.0% |
|
Asia Pacific |
China |
48.0% |
|
Middle East & Africa |
Saudi Arabia |
34.0% |
|
Latin America |
Brazil |
31.0% |
Asia Pacific Shunt Reactor Market Insights
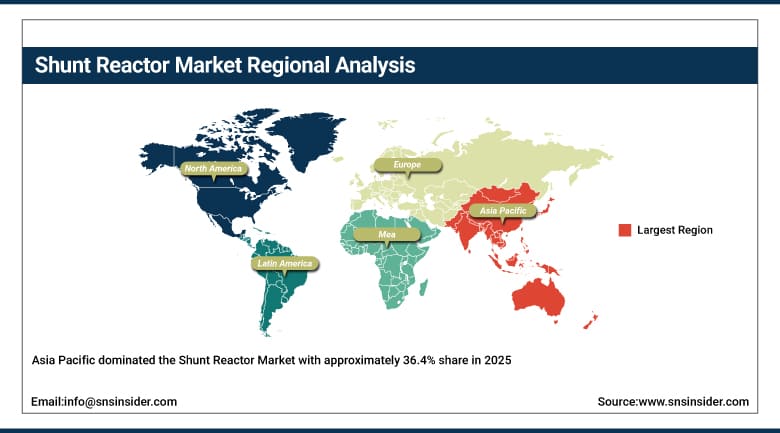
Asia Pacific dominated the Shunt Reactor Market with approximately 36.4% share in 2025, driven by rapid electrification, large-scale renewable energy build-outs, and extensive transmission network expansion across China and India.
China continues to lead regional and global shunt reactor demand given the scale of its transmission network expansion, while India's rapidly growing power infrastructure investment, including large-scale 765 kV transmission projects, continues to drive substantial incremental regional demand. Southeast Asian markets, including Vietnam and Indonesia, continue to expand transmission network investment to support rapidly growing electricity demand, gradually building a serviceable installed base for both new shunt reactor installations and future replacement cycles.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Shunt Reactor Market Insights
North America's market continues to expand steadily, driven by heightened investments in power grid infrastructure, integration of renewable energy sources, and growing grid stability needs across an aging transmission network requiring modernization.
Canadian shunt reactor demand continues to grow alongside expanding hydroelectric and wind generation capacity, while Mexican grid modernization investment is gradually increasing regional demand for reactive power compensation equipment. U.S. transmission system operators continue to prioritize reactive power compensation investment as part of broader grid resilience initiatives, particularly in regions experiencing rapid renewable generation capacity growth that requires expanded voltage stability infrastructure.
Europe Shunt Reactor Market Insights
The market in Europe will benefit from substantial additions to offshore wind capacity that require submarine cable transmissions, thus leading to large-scale requirements of shunt reactors due to the issues related to reactive power compensation associated with submarine cable transmission.
Continued additions to interconnector systems for high-voltage direct current connecting offshore wind capacity with onshore grids by transmission network operators in Germany and the United Kingdom will lead to significant demand for the equipment.
MEA & Latin America Shunt Reactor Market Insights
The Middle East & Africa region is the fastest-growing region in the Shunt Reactor Market with a CAGR of approximately 8.8% through the forecast period, driven by Gulf state grid modernization initiatives and expanding renewable energy project development requiring new reactive power compensation infrastructure. Saudi Arabia's National Transformation Program continues to fund substantial power grid expansion, including new transmission corridors connecting large-scale solar and wind projects to major population centers, directly reinforcing regional shunt reactor demand growth.
Latin America is growing steadily as Brazilian and Chilean grid expansion continues, supported by substantial hydroelectric and growing wind and solar generation capacity requiring expanded transmission network reactive power compensation infrastructure. Mexican grid modernization investment continues to expand alongside growing renewable energy capacity additions, though the pace of shunt reactor demand growth in the country remains more moderate relative to Brazil's larger-scale transmission infrastructure investment program.
Market Dynamics
Growth Drivers: Grid modernization and renewable energy integration fueling reactive power compensation demand
Continuous expansion of the global T&D infrastructure serves as the main structural factor that drives the demand for shunt reactors because growing electricity consumption due to growing population and industrialization requires further development of the electric grid. High integration of renewable energy systems brings considerable variability in the loads of electric grids, and there is a need to install more facilities for compensating reactive power to ensure voltage stability since renewable generation systems are replacing traditional power plants with stable characteristics of generation.
The aging of power grid infrastructure in several well-established markets is resulting in considerable demand for both replacement and modernization efforts, with utilities focusing on technology that minimizes transmission losses and maximizes grid stability in light of the increasing consumption of electricity. The rising capacity of offshore wind energy sources that would require transmission via submarine cables is generating a specific niche in demand for shunt reactors, considering the unique challenges of compensating reactive power via long submarine cable transmission systems. Increasingly, the use of digital technology in monitoring and automating grid processes among utilities is being combined with the deployment of flexible shunt reactors, in search of an integrated solution that would allow for automatic adjustment of reactive power compensation based on grid performance. Increased funding programs aimed at the development of the grid infrastructure in several countries is providing direct financial assistance to the construction of transmission networks, thereby supporting indirectly the purchase of shunt reactors for new high-voltage lines.
Restraints: High capital costs and long project development timelines limiting deployment pace
High capital costs associated with utility-scale shunt reactor installations, particularly high-voltage oil-immersed units, continue to require substantial capital budget allocation that can compete with other grid infrastructure investment priorities within utility capital planning processes. Long project development and permitting timelines for major transmission infrastructure projects, within which shunt reactor installations are typically embedded, continue to extend the overall pace at which new reactive power compensation capacity can be brought online.
Limited manufacturing capacity for the largest, highest-voltage reactor units among a relatively small number of qualified global suppliers can create order backlogs during periods of unusually strong simultaneous demand from multiple large transmission infrastructure projects worldwide. Specialized raw material requirements, including high-grade electrical steel and copper for reactor core and winding construction, continue to expose manufacturers to input cost volatility that can complicate long-term project pricing and margin forecasting.
Opportunities: Offshore wind expansion and smart grid automation widening addressable demand
Rapid global offshore wind capacity expansion presents a substantial growth opportunity for shunt reactor manufacturers, as submarine cable transmission connections require specialized reactive power compensation solutions distinct from conventional overhead transmission line applications. Growing utility interest in variable, dynamically controllable shunt reactors capable of automated response to real-time grid conditions presents an opportunity for manufacturers to differentiate on smart grid integration capability rather than competing purely on conventional fixed-reactor pricing.
Expanding grid infrastructure investment across Middle Eastern and African emerging markets presents a significant growth opportunity for manufacturers able to establish local supply and service relationships as these regions accelerate power infrastructure development to support economic diversification and renewable energy goals. Growing utility interest in predictive maintenance and condition monitoring technology for reactive power compensation equipment presents an opportunity for manufacturers to develop higher-margin, service-inclusive product offerings beyond standalone equipment sales. Growing utility interest in bundled equipment and long-term maintenance service contracts presents an opportunity for manufacturers to build more durable, recurring revenue relationships with major transmission system operators beyond one-time equipment sales.
Recent Developments:
-
In May 2025, GE Vernova secured an order to supply more than 70 units of 765 kV transformers and shunt reactors to POWERGRID in India.
-
In August 2025, Siemens Energy announced delivery initiatives for shunt reactors featuring increased recycled-material content, including pilot units incorporating 100% recycled copper.
-
In 2024, Hitachi Energy expanded its shunt reactor manufacturing capacity in Europe to serve growing offshore wind submarine cable transmission project demand.
-
In 2023, Hyundai Heavy Industries Co., Ltd. announced expanded shunt reactor production capacity in South Korea to serve growing regional grid modernization demand.
-
In 2024, TBEA Co., Ltd. expanded its high-voltage reactor manufacturing capacity in China to meet growing domestic and export transmission infrastructure demand.
-
In 2023, Fuji Electric Co., Ltd. introduced an updated dry-type shunt reactor platform targeting urban substation and indoor installation applications requiring enhanced fire safety characteristics.
-
In 2023, Mitsubishi Electric Corporation expanded its shunt reactor manufacturing capacity in Japan to serve growing domestic and export transmission infrastructure demand.
-
In 2024, CG Power and Industrial Solutions announced expanded high-voltage reactor manufacturing capacity in India, targeting growing domestic transmission network expansion under national grid modernization programs.
-
In 2023, Toshiba Energy Systems expanded its power transformer and reactor manufacturing capacity to serve growing Asian transmission infrastructure demand, including large-scale renewable energy grid connection projects.
-
In 2024, Bharat Heavy Electricals Limited announced expanded shunt reactor production capacity in India to support the country's ambitious national transmission network expansion targets.
-
In 2023, Hyosung Heavy Industries expanded its power transmission equipment manufacturing capacity in South Korea, adding dedicated shunt reactor production lines to serve growing regional and export demand.
Shunt Reactor Market Key Players
-
Siemens Energy AG
-
GE Vernova
-
Hitachi Energy
-
ABB Ltd.
-
TBEA Co., Ltd.
-
Hyundai Heavy Industries Co., Ltd.
-
Fuji Electric Co., Ltd.
-
Nissin Electric Co., Ltd.
-
Toshiba Energy Systems
-
Mitsubishi Electric Corporation
-
CG Power and Industrial Solutions
-
Schneider Electric SE
-
Bharat Heavy Electricals Limited (BHEL)
-
Hyosung Heavy Industries
-
China XD Electric Co., Ltd.
-
Elspec Engineering
-
WEG S.A.
-
Hilkar Elektrik
-
Trench Group
-
Reinhausen Group
Shunt Reactor Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.90 Billion |
| Market Size by 2035 | USD 5.60 Billion |
| CAGR | CAGR of 6.8% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Oil-Immersed, Dry-Type) • by Phase (Three Phase, Single Phase) • byEnd-User (Electric Utility, Renewable Energy) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Ingredion Incorporated, Cargill, Incorporated, Roquette Frères, Tate & Lyle plc, Archer Daniels Midland Company, Royal Avebe U.A., Emsland Group, Grain Processing Corporation, AGRANA Beteiligungs-AG, Südstärke GmbH, Sanstar Ltd., Global Bio-chem Technology Group Company Limited, Universal Starch-Chem Allied Ltd., Gujarat Ambuja Exports Limited, Manildra Group, KMC (Kartoffelmelcentralen A.m.b.A.), Meihua Holdings Group Co., Ltd., Zhucheng Xingmao Corn Developing Co., Ltd., China Essence Group Limited, Japan Corn Starch Co., Ltd. |
Frequently Asked Questions
Leading companies include Siemens Energy AG, GE Vernova, Hitachi Energy, ABB Ltd., and TBEA Co., Ltd., among other major power transmission and distribution equipment manufacturers.
Opportunities include rapid global offshore wind capacity expansion requiring submarine cable reactive power compensation, growing demand for dynamically controllable variable reactors, and expanding grid infrastructure investment across Middle Eastern and African emerging markets.
Growth is driven by continuous expansion of global transmission and distribution infrastructure, rapid renewable energy integration requiring reactive power compensation, and aging power grid infrastructure driving replacement demand.
Oil-Immersed dominates by product type with approximately 57.0% share, Three Phase dominates by phase with roughly 64.0% share, and Electric Utility dominates by end-user with about 68.4% share; Dry-Type, Single Phase, and Renewable Energy are the fastest-growing segments within their respective categories.
Asia Pacific is the largest regional market with approximately 36.4% share, led by China, while the Middle East & Africa is the fastest-growing region at approximately 8.8% CAGR through the forecast period.
