
Single-Use Bioreactors Market Report Scope & Overview:
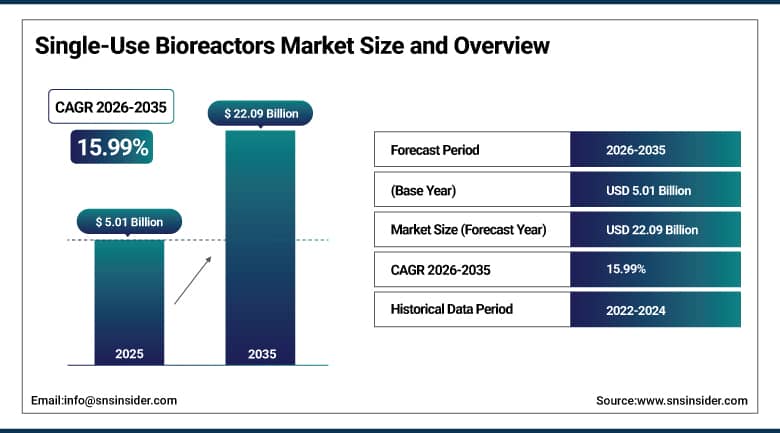
The Single-Use Bioreactors Market was valued at USD 5.01 Billion in 2025 and is expected to reach USD 22.09 Billion by 2035, growing at a CAGR of 15.99% from 2026-2035.
Single-use bioreactors are pre-sterilised, disposable vessels made from medical-grade plastic film that replace the stainless-steel tanks traditionally used to grow mammalian, bacterial, and yeast cells during biopharmaceutical manufacturing. Because each vessel is used once and then discarded, manufacturers eliminate the cleaning validation, steam sterilisation, and cross-contamination risk that stainless-steel systems require between batches, delivering roughly 40% cost savings and cutting total energy and water consumption by 45% to 50% according to industry estimates. The COVID-19 pandemic demonstrated the critical importance of rapid, flexible vaccine and biologics production capacity, and that lesson has continued to drive sustained investment in single-use bioprocessing infrastructure well beyond the pandemic itself.
In February 2025, Thermo Fisher Scientific announced its acquisition of Solventum's Purification and Filtration business, a deal designed to expand the company's single-use bioprocessing capabilities, followed in April 2025 by the launch of its 5-litre DynaDrive bench-scale single-use bioreactor, supporting seamless scale-up from 5 litres to 5,000 litres using consistent platform design and film materials across the entire production journey.
To Get More Information On Single-Use Bioreactors Market - Request Free Sample Report
Single-Use Bioreactors Market Trends:
-
Rising adoption of large-scale single-use bioreactors exceeding 4,000 litres for commercial-volume production.
-
Growing demand for cell and gene therapy manufacturing capacity supporting personalised medicine commercialisation.
-
Expanding bio-circular and sustainable single-use fluid management technology reducing plastic waste footprint.
-
Increasing integration of automation and advanced process control within single-use bioreactor platforms.
-
Rising contract manufacturing organisation capacity investment supporting outsourced biologics production.
-
Growing regional bioprocess design centre expansion supporting localised customer process development.
U.S. Single-Use Bioreactors Market Overview:
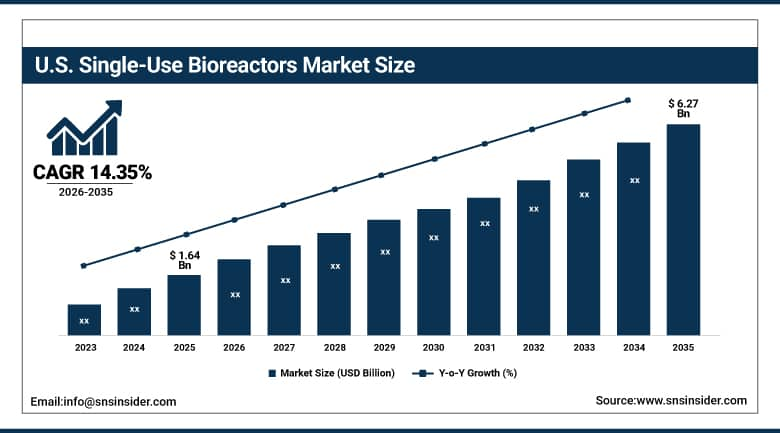
The U.S. Single-Use Bioreactors Market was valued at USD 1.64 Billion in 2025 and is expected to reach USD 6.27 Billion by 2035, growing at a CAGR of 14.35% from 2026-2035.
The U.S. Single-Use Bioreactors Market benefits from a substantial concentration of biopharmaceutical and biotechnology companies, strong investment in biologics, vaccines, and cell and gene therapy manufacturing capacity, and the presence of leading bioprocessing equipment manufacturers headquartered in the country that continue to compete on scale, automation, and total cost of ownership. Continued Food and Drug Administration approval activity for biologics and biosimilars continues to expand the addressable manufacturing base for single-use technology, while major contract manufacturing organisations continue investing in additional single-use bioreactor capacity to serve both U.S. and international biopharmaceutical customers seeking flexible, rapidly deployable production capability. Leading equipment manufacturers continue to expand bioprocess design centres and applications support capacity to serve this growing customer base directly. Continued growth in cell and gene therapy commercialisation, alongside sustained biologics pipeline expansion, is expected to support strong demand growth throughout the forecast period.
In December 2025, Cytiva completed major bioprocess manufacturing and capacity expansion projects across the United States to strengthen supply of single-use bioreactor and filtration technologies, while Thermo Fisher Scientific reported in its fourth-quarter 2025 results that it had established a strategic collaboration with OpenAI to expand artificial intelligence use across its operations and products, alongside continued expansion of its bioprocess design centers supporting pharma and biotech customers.
Single-Use Bioreactors Market Segment Analysis:
-
By Cell Type, the Mammalian Cells segment dominated the market with a 62.34% share in 2025, while the Yeast Cells segment is the fastest growing with a CAGR of 15.89% during 2026-2035.
-
By Product, the Single-Use Bioreactor Systems segment dominated the market with a 42.15% share in 2025, while the Filtration Assemblies segment is the fastest growing with a CAGR of 16.65% during 2026-2035.
-
By Molecule Type, the Monoclonal Antibodies segment dominated the market with a 45.21% share in 2025, while the Stem Cell Applications segment is the fastest growing with a CAGR of 16.87% during 2026-2035.
-
By Application, the Biopharmaceutical Production segment dominated the market with a 58.75% share in 2025, while the Cell and Gene Therapy Manufacturing segment is the fastest growing with a CAGR of 19.45% during 2026-2035.
-
By End Use, the Biopharmaceutical and Biotechnology Companies segment dominated the market with a 54.35% share in 2025, while the Contract Manufacturing Organizations segment is the fastest growing with a CAGR of 18.65% during 2026-2035.
By Cell Type, Mammalian Cells Dominates the Market and Yeast Cells Grows Fastest
Mammalian cells dominated the market in 2025 with a 62.34% share, reflecting their essential role in producing monoclonal antibodies, recombinant proteins, and other complex biologics that require the post-translational modification capability only mammalian expression systems reliably provide. Chinese hamster ovary cell lines in particular continue to serve as the workhorse expression system for the large majority of approved biologics, sustaining mammalian cell culture as the dominant cell type category across the broader single-use bioreactor market by a considerable margin.
Yeast cells are projected to be the fastest-growing cell type over the forecast period, registering a CAGR of 15.89% as yeast expression systems continue gaining favour for their faster growth cycles, lower production costs, and genuine suitability for an expanding range of simpler protein and vaccine antigen production applications. Rising interest in yeast-based platforms for certain vaccine and enzyme production programs continues to drive above-market growth for this cell type relative to the broader mammalian-cell-dominated segment, particularly among manufacturers seeking to reduce production timelines and overall manufacturing cost.
By Product, Single-Use Bioreactor Systems Dominates the Market and Filtration Assemblies Grows Fastest
Single-use bioreactor systems dominated the market in 2025, capturing the largest share of overall revenue as these complete, ready-to-use vessels remain the foundational purchase for any biomanufacturing facility transitioning away from stainless-steel infrastructure. Biopharmaceutical manufacturers continue to specify complete systems, including the bioreactor bag, control unit, and integrated sensors, as their primary capital investment when building new single-use production capacity, and the breadth of scale options now available, spanning bench-top research volumes through commercial-scale vessels exceeding 4,000 litres, continues to sustain this category's position as the largest product segment across the broader market.
Filtration assemblies are projected to be the fastest-growing product category over the forecast period, registering a CAGR of 16.65% as downstream purification steps increasingly adopt single-use formats alongside upstream cell culture. Rising biologics and biosimilars production volume continues to expand demand for single-use filtration capacity capable of handling increasingly complex purification workflows, and manufacturers that can deliver reliable, high-throughput filtration assemblies compatible with existing single-use bioreactor platforms are capturing a growing share of overall bioprocessing capital spending as facilities continue converting downstream processing to disposable formats alongside upstream cell culture.
By Molecule Type, Monoclonal Antibodies Dominates the Market and Stem Cell Applications Grows Fastest
Monoclonal antibodies dominated the market in 2025 with a 45.21% share. These therapeutics continue to represent one of the largest and fastest-growing categories within the broader biologics industry, treating everything from cancer through autoimmune disease, and the sheer scale of global monoclonal antibody manufacturing volume continues to anchor this molecule type as the largest source of single-use bioreactor demand by a clear margin over every other category.
Stem cell applications are projected to be the fastest-growing molecule type over the forecast period, registering a CAGR of 16.87% as cell therapy commercialisation continues to accelerate globally. Rising clinical and commercial interest in stem cell-based regenerative medicine, combined with the unique manufacturing requirements these therapies present relative to conventional biologics, continues to drive specialised single-use bioreactor demand tailored specifically to the smaller batch sizes and higher sterility assurance stem cell manufacturing typically requires.
By Application, Biopharmaceutical Production Dominates the Market and Cell and Gene Therapy Manufacturing Grows Fastest
Biopharmaceutical production dominated the market in 2025. Commercial-scale manufacturing of approved biologics, vaccines, and biosimilars continues to consume the largest share of overall single-use bioreactor capacity worldwide, reflecting the sheer production volume required to supply global patient populations, and this established, high-volume manufacturing base continues to anchor biopharmaceutical production as the clear leading application category.
Cell and gene therapy manufacturing is projected to be the fastest-growing application over the forecast period, registering a CAGR of 19.45% as personalised and advanced therapy commercialisation continues to accelerate. These therapies typically require smaller, more flexible batch sizes than conventional biologics manufacturing, making single-use systems particularly well suited to their production requirements, and continued regulatory approval of new cell and gene therapies continues to expand this application's addressable manufacturing base well ahead of the broader market average.
By End Use, Biopharmaceutical and Biotechnology Companies Dominates the Market and Contract Manufacturing Organizations Grows Fastest
Biopharmaceutical and biotechnology companies dominated the market in 2025. In-house manufacturing capacity remains the default choice for many established biologics developers with sufficient capital to build and operate their own production infrastructure, and this substantial installed manufacturing base continues to anchor biopharmaceutical and biotechnology companies as the largest end-use category across the broader single-use bioreactor market.
Contract manufacturing organizations are projected to be the fastest-growing end-use category over the forecast period, registering a CAGR of 18.65% as biopharmaceutical companies increasingly outsource production to specialised manufacturing partners rather than building costly in-house capacity themselves. Rising demand for flexible, rapidly deployable manufacturing capability continues to favour contract organisations that have invested heavily in single-use infrastructure capable of serving multiple customers and programs without extensive facility reconfiguration between projects.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
79.25% |
|
Europe |
Germany |
28.45% |
|
Asia Pacific |
China |
36.75% |
|
Latin America |
Brazil |
22.85% |
|
Middle East & Africa |
United Arab Emirates |
19.65% |
North America Single-Use Bioreactors Market Insights
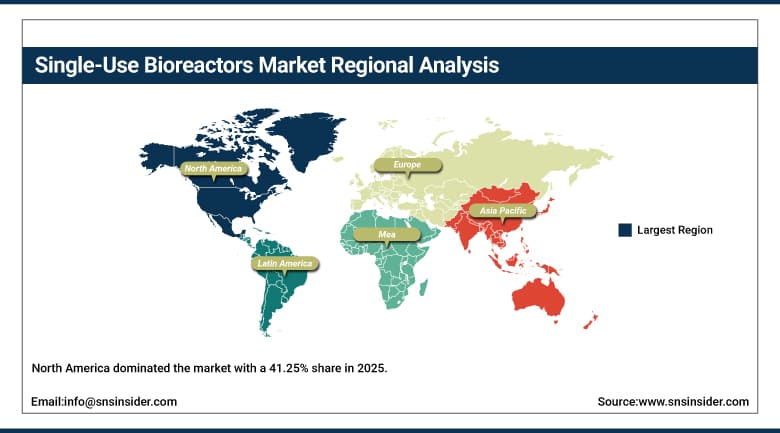
North America dominated the market with a 41.25% share in 2025. Strong investment in biologics, vaccines, and cell and gene therapies, supported by major players including Thermo Fisher Scientific, Cytiva, and Sartorius continuing to expand their single-use portfolios, continues to reinforce the region's leadership position across every major product and application category.
Canada contributes meaningful incremental regional demand through its own growing biotechnology sector and expanding contract manufacturing capacity. Continued facility expansion by leading equipment manufacturers, combined with sustained biologics pipeline growth among domestically headquartered biopharmaceutical companies, is expected to keep North America in the lead through the forecast period, even as its growth rate trails the faster-scaling markets of Asia Pacific.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Single-Use Bioreactors Market Insights
Asia Pacific is projected to be the fastest-growing region over the forecast period, registering a CAGR of approximately 17.47%, as rapidly expanding contract manufacturing capacity, growing domestic biopharmaceutical industries, and substantial government investment in biotechnology infrastructure continue to accelerate regional adoption of single-use bioprocessing technology.
China anchors regional demand through its rapidly expanding domestic biopharmaceutical manufacturing base and growing contract manufacturing sector serving both domestic and international customers. Singapore contributes substantial regional depth as a leading contract manufacturing hub, exemplified by continued large-scale facility investment from major biologics manufacturers, while Japan and South Korea add further regional depth through established biotechnology and pharmaceutical manufacturing sectors.
Europe Single-Use Bioreactors Market Insights
Europe holds a significant share of the global market, anchored by Germany's substantial biopharmaceutical manufacturing base and its position as home to several of the world's leading bioprocessing equipment manufacturers. The region's mature biologics industry and strong regulatory framework continue to sustain steady demand across every major single-use bioreactor category.
The United Kingdom, France, and Switzerland add consistent regional demand as national biopharmaceutical and biotechnology sectors continue extending single-use technology adoption. Continued regional investment in sustainable, bio-circular single-use technology is expected to sustain steady growth across the broader European market through the forecast period.
MEA and Latin America Single-Use Bioreactors Market Insights
The Middle East and Africa region is supported by growing biopharmaceutical manufacturing investment across the United Arab Emirates and Saudi Arabia, where regional governments continue expanding domestic biotechnology and pharmaceutical manufacturing capability as part of broader economic diversification strategies.
Latin America is anchored by Brazil, where a growing domestic biopharmaceutical sector sustains steady demand for single-use bioprocessing technology. Mexico contributes further incremental growth as regional biotechnology manufacturing investment continues to expand gradually across the broader region.
Market Dynamics:
Growth Drivers: Biologics Commercialisation and Cost Efficiency Advantages
Rapid commercialisation of biologics, biosimilars, and cell and gene therapies stands as the primary growth driver, as each of these therapeutic categories continues to benefit disproportionately from the speed and flexibility single-use systems offer relative to fixed stainless-steel infrastructure. Continued approval of new biologics and advanced therapies worldwide continues to expand the manufacturing capacity required across the entire industry, and single-use technology continues to capture a growing share of that expanding capital investment given its meaningfully faster deployment timeline relative to traditional stainless-steel facility construction.
Substantial cost and operational efficiency advantages represent a second major driver, as switching to single-use systems delivers approximately 40% cost savings by eliminating cleaning and sterilisation cycles between batches, while simultaneously reducing total energy and water consumption by 45% to 50% relative to conventional stainless-steel infrastructure. These efficiency gains continue to make single-use technology an increasingly compelling choice even for manufacturers with existing stainless-steel capacity considering their next capacity expansion decision.
Restraints: Plastic Waste Concerns and Supply Chain Dependency
Growing concern over plastic waste generation remains a genuine restraint, as single-use systems inherently generate more disposable plastic waste than reusable stainless-steel alternatives, prompting some manufacturers and regulators to scrutinise the environmental footprint of an industry that has grown rapidly in scale over the past decade without fully resolving its end-of-life material disposal challenge.
Dependency on a concentrated base of specialised film and component suppliers presents a further restraint, as the technical complexity of manufacturing medical-grade, cell-culture-compatible plastic film continues to limit the number of qualified suppliers capable of meeting biopharmaceutical manufacturing quality standards, creating genuine supply chain concentration risk that became particularly visible during periods of surging pandemic-driven demand.
Opportunities: Large-Scale Commercial Production and Sustainable Technology Development
Continued expansion into large-scale commercial production represents a substantial opportunity, as manufacturers that can reliably deliver single-use bioreactors exceeding 4,000 litres capacity stand to capture demand from large contract manufacturing organisations and biopharmaceutical companies seeking genuine single-use alternatives to stainless-steel systems even at the largest commercial production scales.
Continued development of bio-circular and more sustainable single-use fluid management technology offers a further avenue for growth, as manufacturers that can meaningfully reduce plastic waste footprint while maintaining sterility assurance and manufacturing reliability are positioned to capture demand from biopharmaceutical companies increasingly prioritising environmental sustainability alongside cost and operational efficiency in their capital equipment purchasing decisions.
Recent Developments:
-
2026, Sartorius expanded its sustainable single-use bioprocessing portfolio, extending ISCC Plus-certified materials to additional production sites and product lines, including Flexsafe bags and Sartopore Evo filters. The initiative is aimed at reducing fossil-based plastic content in single-use manufacturing components.
-
2026, Thermo Fisher Scientific marked 20 years of its HyPerforma Single-Use Bioreactor platform, highlighting continued development of disposable bioreactor technology for scalable biologics manufacturing. The platform is available across capacities from 50 L to 2,000 L for applications including batch, fed-batch, and perfusion cultures.
-
2025, Thermo Fisher Scientific expanded its bioprocessing infrastructure in Hyderabad, India, establishing a Bioprocess Design Center equipped with single-use bioreactor technologies and supporting bench-to-pilot-scale process development for biologics and vaccines.
-
2025, Telangana launched Telangana 1 Bio in Genome Valley, a single-use bioprocess design and scale-up facility developed with Thermo Fisher Scientific and other partners. The facility includes a 500-L bioreactor-equipped center, upstream and dow
Single-Use Bioreactors Market Key Players:
-
Sartorius AG
-
Thermo Fisher Scientific Inc.
-
Danaher Corporation (Cytiva)
-
Merck KGaA
-
Getinge AB
-
Eppendorf SE
-
PBS Biotech, Inc.
-
Finesse Solutions, LLC
-
Celltainer Biotech B.V.
-
ABEC, Inc.
-
Applikon Biotechnology B.V.
-
Distek, Inc.
-
Infors HT
-
Meissner Filtration Products, Inc.
-
Corning Incorporated
-
Parker Hannifin Corporation
-
Repligen Corporation
-
Esco Aster Pte. Ltd.
-
Cellexus International Ltd.
-
Solaris Biotechnology S.r.l.
Single-Use Bioreactors Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.01 Billion |
| Market Size by 2035 | USD 22.09 Billion |
| CAGR | CAGR of 15.99% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Single-Use Bioreactor Systems, Filtration Assemblies, Single-Use Accessories, and Media Bags and Containers) • By Cell Type (Mammalian Cells, Bacterial Cells, Yeast Cells, Insect Cells, and Other Cell Types) • By Molecule Type (Monoclonal Antibodies, Vaccines, Stem Cells, Gene Therapy Products, and Other Biologics) • By Application (Biopharmaceutical Production, Research and Development, and Cell and Gene Therapy Manufacturing) • By End Use (Biopharmaceutical and Biotechnology Companies, Contract Manufacturing Organizations, and Academic and Research Institutes) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Sartorius AG, Thermo Fisher Scientific Inc., Danaher Corporation (Cytiva), Merck KGaA, Getinge AB, Eppendorf SE, PBS Biotech, Inc., Finesse Solutions, LLC, Celltainer Biotech B.V., ABEC, Inc., Applikon Biotechnology B.V., Distek, Inc., Infors HT, Meissner Filtration Products, Inc., Corning Incorporated, Parker Hannifin Corporation, Repligen Corporation, Esco Aster Pte. Ltd., Cellexus International Ltd., Solaris Biotechnology S.r.l. |

Frequently Asked Questions
Key players include Sartorius AG, Thermo Fisher Scientific Inc., Danaher Corporation, Merck KGaA, and Getinge AB, among other bioprocessing equipment manufacturers.
Continued expansion into large-scale commercial production and continued development of bio-circular, sustainable single-use technology represent the primary opportunities.
Growth is primarily driven by rapid commercialisation of biologics, biosimilars, and cell and gene therapies, combined with substantial cost and operational efficiency advantages.
North America dominated the market with a 41.25% share in 2025, supported by strong biologics, vaccine, and cell and gene therapy investment.
By Product, Single-Use Bioreactor Systems dominated the market with a 42.15% share in 2025, reflecting their role as the foundational purchase for single-use biomanufacturing.
