
Soil Moisture Sensor Market Report Scope & Overview:
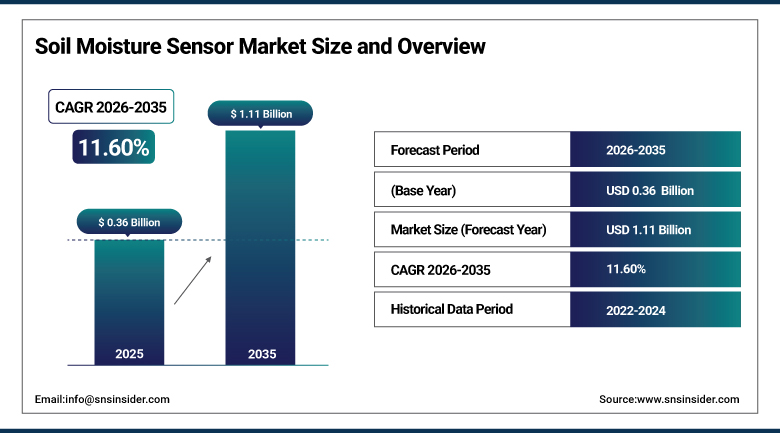
The Soil Moisture Sensor Market was valued at USD 0.36 Billion in 2025 and is expected to reach USD 1.11 Billion by 2035, growing at a CAGR of 11.60% from 2026-2035.
The Soil Moisture Sensor Market covers devices that measure the water content or water tension of soil and send readings to controllers, data loggers or cloud platforms. Volumetric probes based on capacitance or time domain methods, tensiometers, gypsum blocks and granular matrix sensors help growers, groundskeepers and researchers decide when and how much to irrigate. Farms use them to save water and protect yields, while golf courses, sports fields, gardens and construction sites use them for turf health and slope safety. Wireless low-power networks, multi-depth probes and analytics software are making installation easier and information more useful through 2035. Vendors that pair hardware with analytics are best placed.
⮞The World Meteorological Organization reported on 17 September 2026 that river flows were below normal across 36% of global basin area in 2025, and that nearly two-thirds of monitored wells fell outside their historical norm.
To Get more information Soil Moisture Sensor Market - Request Free Sample Report
Soil Moisture Sensor Market Trends
-
Multi-depth probes that record moisture, temperature and salinity at several soil layers on one cable are replacing single-point sensors on commercial farms.
-
Long-range low-power wireless networks such as LoRaWAN and NB-IoT are letting sensors run for years on a battery and report from remote fields.
-
Irrigation equipment makers are integrating sensor data directly into pivot and drip control platforms for automatic, field-by-field scheduling.
-
Analytics software is converting raw readings into irrigation advice, crop stress alerts and compliance reports for water regulators.
-
Sensor makers are partnering with telecom and technology firms to bundle hardware with connectivity and irrigation navigation services.
U.S. Soil Moisture Sensor Market Outlook
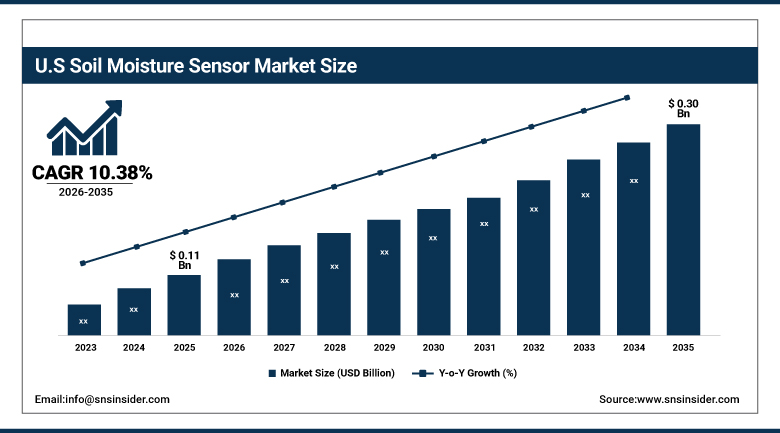
The U.S. Soil Moisture Sensor Market was valued at USD 0.11 Billion in 2025 and is expected to reach USD 0.30 Billion by 2035, growing at a CAGR of 10.38% from 2026-2035.
The U.S. Soil Moisture Sensor Market is the largest national market in North America, supported by extensive irrigated cropland in the Plains, the West and the Southeast, by golf and sports turf operators, and by a strong base of agricultural technology firms. Persistent drought in the Colorado River and Rio Grande basins pushes growers and municipalities to document and cut water use. Center-pivot owners, specialty crop farms and landscape contractors install probes to schedule irrigation more precisely. Cost-share programs, university extension services and growing comfort with data platforms keep adoption moving upward through 2035. Water districts in the West also fund sensor programs for urban landscapes.
⮞The National Integrated Drought Information System reported on 16 September 2026 that 47.6% of the United States was in drought on 25 August 2026 and that summer 2026 was the warmest on record for the contiguous U.S.
Soil Moisture Sensor Market Segment Analysis
-
By Sensor Type, the Tensiometers segment dominated the Soil Moisture Sensor Market with approximately 27.86% share in 2025, while the Capacitance Sensors segment is the fastest growing with a CAGR of approximately 15.34%.
-
By Connectivity, the Wired segment dominated the Soil Moisture Sensor Market with approximately 53.74% share in 2025, while the Wireless segment is the fastest growing with a CAGR of approximately 14.82%.
-
By Application, the Agriculture segment dominated the Soil Moisture Sensor Market with approximately 47.62% share in 2025, while the Sports segment is the fastest growing with a CAGR of approximately 15.91%.
-
By Type, the Digital segment dominated the Soil Moisture Sensor Market with approximately 56.38% share in 2025 and is also the fastest growing with a CAGR of approximately 12.74%.
By Sensor Type, Tensiometers Dominate the Soil Moisture Sensor Market and Capacitance Sensors Grow Fastest
Tensiometers hold approximately 27.86% of the Soil Moisture Sensor Market in 2025 because they measure soil water tension directly, which tells growers how hard a plant must work to extract water. Readings are independent of soil texture, they are inexpensive, and they have decades of agronomic research behind their interpretation. Orchards, vineyards, vegetable farms and research plots rely on them to trigger irrigation at the right moment. Their long track record and simple maintenance routines keep them in wide use despite newer electronic alternatives. Lower cost per measuring point also helps them in budget-limited projects. Product development in this group remains active.
Capacitance sensors are the fastest growing type, with a CAGR of approximately 15.34% during 2026-2035. They estimate volumetric water content from the dielectric properties of soil, respond quickly, require little upkeep and are easy to combine with temperature and salinity measurements. Falling electronics costs and multi-depth probes with accuracy of a few percentage points are widening their use on commercial farms and turf. Compatibility with data loggers and wireless nodes makes them the preferred choice for connected irrigation systems. Vendors also offer factory calibration for common soil classes, which shortens setup time.
⮞The Australian Bureau of Agricultural and Resource Economics and Sciences reported in June 2026 that the 2026-27 winter crop was forecast at 23.6 Billion hectares, down 7%, after soil moisture stayed very low in northern New South Wales and southern Queensland until mid-May.
By Connectivity, Wired Dominates the Soil Moisture Sensor Market and Wireless Grows Fastest
Wired sensors account for approximately 53.74% of the market in 2025. They connect straight to irrigation controllers, data loggers and weather stations, delivering dependable readings without battery replacement or radio coverage concerns. Golf courses, greenhouses, research stations and landscape installations use them where cables are practical and power is available. Low unit prices and compatibility with established irrigation controllers sustain their lead, and many commercial growers prefer proven analog and SDI-12 interfaces over new wireless systems. Maintenance staff at turf and greenhouse sites value the predictable behavior of such installations. Product development in this group remains active.
Wireless sensors are the fastest growing connectivity option, at a CAGR of approximately 14.82% during 2026-2035. Low-power wide-area networks transmit readings over several kilometers, and batteries now last five years or more, which removes the cost of trenching cables across large fields. Farmers can add or relocate nodes easily, and cloud dashboards give instant access on phones. Falling gateway prices and expanding rural coverage are encouraging both large growers and smallholders to switch from wired setups. Solar-powered nodes and mesh gateways further extend range in hilly or heavily vegetated terrain.
⮞The Food and Agriculture Organization reported in December 2025 through its AQUASTAT update that agriculture accounts for about 72% of global freshwater withdrawals.
By Application, Agriculture Dominates the Soil Moisture Sensor Market and Sports Grows Fastest
Agriculture holds approximately 47.62% of the Soil Moisture Sensor Market in 2025 because irrigation is the largest single use of water and soil moisture is the most direct signal for scheduling it. Row crops, orchards, vineyards, vegetables and pasture growers deploy probes to avoid over-watering, reduce pumping and fertilizer losses, and protect yields during dry spells. Water restrictions, rising energy costs for pumping and government irrigation modernization programs all strengthen the business case for measuring conditions in the root zone. Insurers and food buyers are also beginning to ask for documented irrigation practices. Product development in this group remains active.
Sports facilities are the fastest growing application, with a CAGR of approximately 15.91% through 2035. Stadiums, golf courses, racetracks and training grounds use in-ground sensors to keep playing surfaces firm and consistent while using less water. Handheld probes allow groundskeepers to map moisture across a field within minutes. Pressure from water utilities, sustainability goals at professional venues and the high cost of damaged turf encourage continued investment in precise monitoring. Handheld probes allow groundskeepers to map moisture across a field within minutes, supporting daily maintenance routines and event preparation.
⮞The U.S. Bureau of Reclamation reported that, as of 30 August 2026, 10 of 12 major reservoirs were below average and Lake Mead had reached an all-time record low on 7 August 2026.
By Type, Digital Dominates the Soil Moisture Sensor Market and Also Grows Fastest
Digital sensors represent approximately 56.38% of the market in 2025 because they output calibrated readings through interfaces such as SDI-12, Modbus and wireless protocols. Built-in microcontrollers apply temperature compensation and soil-specific calibration, which improves accuracy and reduces the effort needed by installers. They can report several parameters at once, including moisture, temperature and electrical conductivity, and many support remote firmware updates. These features make them the standard choice for professional agriculture and research. Vendors also provide application programming interfaces that let farm software firms pull readings directly. Manufacturers also supply standard connectors. Product development in this group remains active.
Digital sensors are also the fastest growing type, at a CAGR of approximately 12.74% during 2026-2035. As irrigation platforms move to cloud analytics, buyers prefer devices that plug into data networks without custom circuitry. Lower chip prices and robust low-power designs make the extra functionality affordable. Analog probes continue to serve low-cost hobby and controller applications, but the shift toward connected, standardized sensing points keeps digital products growing ahead of the market. Dealers report that growers now ask first about software integration when comparing probes.
⮞The U.S. Drought Monitor reported on 22 October 2026 that Lake Powell stood at about 22% of capacity, with long-term hydrologic drought persisting in the Colorado River and Rio Grande basins.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.12% |
|
Asia Pacific |
China |
38.54% |
|
Europe |
Germany |
21.83% |
|
Latin America |
Brazil |
46.92% |
|
Middle East & Africa |
Israel |
24.58% |
North America Soil Moisture Sensor Market Insights
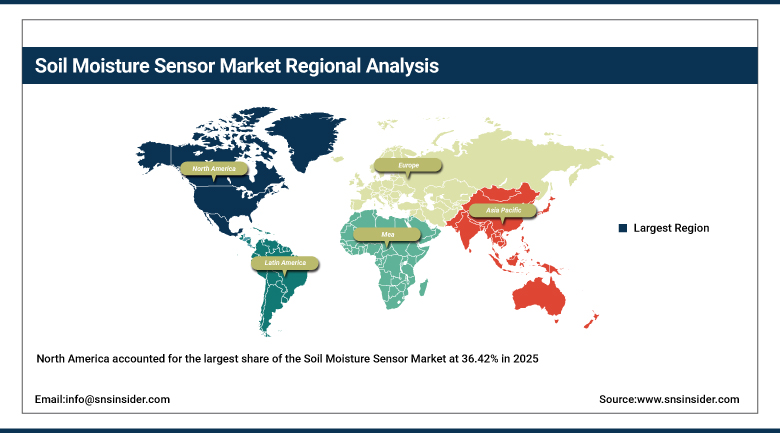
North America accounted for the largest share of the Soil Moisture Sensor Market at 36.42% in 2025, with the United States contributing about 84.12% of regional demand and Canada the balance. The region has large irrigated areas, a mature precision agriculture industry and a dense network of sensor makers, irrigation equipment manufacturers and software firms. Drought in the West and variable rainfall elsewhere raise interest in measured irrigation. Turf, golf and sports venues add steady demand for in-ground and portable probes. Distributors and dealers provide installation and agronomy support.
Canada adds demand through prairie grain and potato growers, who use sensors to manage moisture stress and disease risk. Mexico, which belongs to Latin America, supplies export vegetables that depend on United States buyers who set water-use expectations. Equipment manufacturers bundle probes with irrigation controllers and telematics, and university extension programs train growers to interpret readings. Competition among established brands and venture-backed entrants keeps product improvement rapid. Growers also use sensor records to document responsible water use for sustainability programs run by food buyers.
⮞The U.S. Department of Agriculture's National Agricultural Statistics Service reported on 5 October 2026 that Wisconsin topsoil moisture was rated 5% very short, 15% short, 67% adequate and 13% surplus.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Soil Moisture Sensor Market Insights
Europe held approximately 25.46% of the Soil Moisture Sensor Market in 2025, led by Spain, France, Italy, Germany and the Netherlands. Southern Mediterranean farmland faces recurring drought and water restrictions, and the Common Agricultural Policy rewards efficient resource use. Greenhouse horticulture in the Netherlands and Spain, vineyards in France and Italy, and large arable farms in Germany all use soil monitoring. Strict nutrient and water regulations encourage documented measurement. Water-use permitting in Spain and Italy also leads some irrigators to submit measured data.
European manufacturers specialize in research-grade probes and wireless nodes, supported by strong university and institute networks. Eastern European farms are adopting sensors as financing and extension services improve. The United Kingdom has high interest in turf and potato production, while Nordic countries use sensors for forestry and cold-climate crops. Buyers pay close attention to calibration, durability in frost conditions and data-protection practices when selecting systems. Distributors in the region frequently bundle sensors with agronomy advice, which raises the share of buyers that act on readings.
⮞Eurostat reported in 2026 that irrigated area in the European Union stands at 10.0 Billion hectares, or 6.5% of utilized agricultural area, largely unchanged since 2010.
Asia Pacific Soil Moisture Sensor Market Insights
Asia Pacific held approximately 24.13% of the Soil Moisture Sensor Market in 2025 and is the fastest growing region, with a CAGR of 13.37% during 2026-2035. China, India, Australia, Japan and Southeast Asia combine very large irrigated areas with strong policy support for water-saving agriculture. Growing farm sizes, labor shortages and rising incomes encourage investment in automation, and local manufacturers supply low-cost probes. Water stress in the Indo-Gangetic plain and northern China adds urgency. Government extension networks and mobile advisory apps further spread awareness among small and mid-sized farmers.
China leads regional demand through national water-saving irrigation targets and smart agriculture pilots. India is expanding micro-irrigation and digital advisory services for Billions of farmers, and Australia relies on sensors in cotton, horticulture and dryland cropping. Japan has a strong sensor and telecom base and is creating new joint ventures for irrigation guidance. South Korea, Thailand and Vietnam add demand through greenhouses and high-value crops. Local manufacturers in China and Taiwan supply low-cost nodes that international brands increasingly match with software offers.
⮞The Ministry of Water Resources of China reported on 9 January 2026 that effective irrigated farmland reached 1.09 billion mu, about 72.67 Billion hectares, at the end of 2025.
MEA & Latin America Soil Moisture Sensor Market Insights
The Middle East and Africa and Latin America together account for approximately 13.99% of the Soil Moisture Sensor Market in 2025, with Latin America at 7.39% and the Middle East and Africa at 6.60%. In the Middle East, Israel, Saudi Arabia and the United Arab Emirates pair scarce water with advanced irrigated agriculture and controlled-environment farming. Africa is led by South Africa, Egypt and Morocco, where commercial fruit and vegetable exporters adopt monitoring, while smallholder uptake remains limited by cost. Greenhouse projects in the Gulf add steady demand for monitoring hardware.
Latin America is led by Brazil, Argentina and Chile. Brazil has a rapidly expanding irrigated area in coffee, sugarcane, grains and fruit, and Chile and Peru use sensors in export avocados, berries and grapes. Mexico, a major vegetable exporter, is added to the Latin American total. Dealers and agronomy consultants play a central role in education, and pay-as-you-go or service-based models are lowering barriers for mid-sized farms. Currency swings and import dependence continue to affect pricing. Cooperative buying groups are also emerging among smaller growers.
⮞The Saudi General Authority for Statistics reported on 5 January 2025 that agricultural water consumption was 12,298 Billion cubic meters in 2023, including 9,356 Billion cubic meters of non-renewable groundwater, down 7% from 2022.
Market Dynamics
Growth Drivers: Water Scarcity and Irrigation Modernization Drive Growth in the Soil Moisture Sensor Market
Water scarcity is the strongest force behind the Soil Moisture Sensor Market. Agriculture uses most of the freshwater withdrawn worldwide, and droughts, falling aquifers and competition from cities are pushing farmers and regulators toward measured irrigation. Sensors show when the root zone is dry and when it is already full, preventing wasted pumping and nutrient leaching. Growers who adopt them often cut water and energy use while protecting yield and quality, which creates a clear payback case. Insurance and lending programs are also starting to reward documented water management.
Government programs for irrigation modernization are the second driver. Subsidies for drip and sprinkler systems, water-use reporting rules and national smart agriculture plans increasingly include sensing as an eligible component. Connected irrigation platforms and satellite services need ground-truth data to calibrate their models, which broadens demand beyond individual farms. Equipment makers bundle probes with new systems, and falling prices for electronics and connectivity widen the pool of buyers. Research institutions and agricultural universities continue to publish irrigation guidelines that rely on soil measurements.
⮞The Ministry of Agriculture and Farmers Welfare of India reported on 29 August 2026 that the Per Drop More Crop component had brought 11.5 Billion hectares under micro-irrigation as of July 2026, about 8.11% of net sown area.
Restraints: Cost, Calibration and Low Irrigation Adoption Restrain Growth in the Soil Moisture Sensor Market
Cost and complexity restrain the Soil Moisture Sensor Market, particularly among smallholders. A reliable multi-depth probe, gateway and subscription can cost more than many small farms are willing to spend, and the benefits depend on correct installation and interpretation. Readings vary with soil texture, salinity, compaction and contact between probe and soil, so poorly calibrated sensors can mislead users. Disappointing early experiences can make farmers wary of further investment. Distribution partners must therefore invest heavily in training. Farmers with thin margins often postpone purchases until prices fall.
Limited irrigation infrastructure is a deeper constraint in some regions. Where most cropland depends on rain, there is little to control, and sensor demand stays low. Rural connectivity gaps, theft or damage in open fields, battery maintenance and the shortage of trained advisers add friction. Fragmented standards between brands also make it hard for growers to mix equipment, and low-priced unbranded probes pressure margins for established suppliers. Warranty claims from harsh soils and farm machinery damage can erode supplier returns.
⮞The International Finance Corporation reported in July 2025 that only about 6% of Africa's cultivated land is irrigated.
Opportunities: Analytics Services and Emerging Irrigation Markets Create Opportunities in the Soil Moisture Sensor Market
Analytics and service models create a major opportunity. Vendors are shifting from selling probes to selling outcomes, such as irrigation schedules, crop stress alerts, water budgets and compliance reports. Artificial intelligence can combine soil readings with weather, satellite imagery and crop models to recommend actions field by field. Subscription revenue improves vendor economics and keeps customers engaged, while acquisitions of imaging and spectroscopy firms broaden the data that supplier platforms can offer. Data ownership terms and clear privacy practices will matter as platforms scale.
Emerging irrigation markets provide further growth. Brazil, India, Southeast Asia, Africa and the Gulf are expanding irrigated area, and leasing or pay-per-season models can make sensors accessible to mid-sized farms. Golf, sports and municipal landscapes, green roofs, construction slope monitoring and forestry research open further uses. Rugged, low-cost devices designed for developing regions, together with local training partnerships, could expand the customer base significantly. Public research funding for climate-smart agriculture further supports pilot projects that later convert into purchases. Local training partnerships further help new users.
⮞The Brazilian Association of Machinery and Equipment Industry, with the University of São Paulo, reported on 16 June 2026 that Brazil has about 8.19 Billion hectares irrigated against a potential of about 55.8 Billion hectares.
Recent Developments:
-
2025: Internet Initiative Japan and Sony Semiconductor Solutions agreed to establish a joint venture for soil moisture sensors and irrigation navigation services, to be formed from April 2026 with ownership of 85% for the former and 11% for the latter.
-
2026: CropX Technologies launched the Apex soil sensor in 12, 24 and 36 inch configurations, recording moisture, temperature and salinity every 4 inches of depth and validated against laboratory soil samples.
-
2026: LI-COR, Inc. introduced the LI-300 and LI-350 soil moisture sensors, which measure volumetric water content from 0 to 1 cubic meter per cubic meter with typical accuracy of ±0.03 and temperature from −40 to 70 degrees Celsius.
-
2026: Phoenix Contact’s PMD EM M-30 LR LoRaWAN soil moisture sensor became available through Mouser, measuring volumetric water content at 30 cm depth and reporting hourly with parameterization for different soil types.
Soil Moisture Sensor Market Key Players are:
-
CropX Technologies Ltd.
-
METER Group, Inc.
-
Sensoterra International B.V.
-
LI-COR, Inc.
-
Sentek Pty Ltd
-
Dragino Technology Co., Limited
-
RAKwireless Technology Limited
-
Phoenix Contact GmbH & Co. KG
-
Seeed Technology Co., Ltd.
-
Delta-T Devices Ltd
-
Hunter Industries Incorporated
-
Sony Semiconductor Solutions Corporation
Soil Moisture Sensor Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.36 Billion |
| Market Size by 2035 | USD 1.11 Billion |
| CAGR | CAGR of 11.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Sensor Type (Tensiometers, Capacitance Sensors, Gypsum Blocks, Granular Matrix Sensors, Time Domain Transmissometry Sensors, and Others) • By Connectivity (Wired and Wireless) • By Application (Agriculture, Residential, Landscaping and Ground Care, Sports, Forestry, Construction and Mining, and Others) • By Type (Digital and Analog) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | CropX Technologies Ltd., METER Group, Inc., Sensoterra International B.V., LI-COR, Inc., Sentek Pty Ltd, Dragino Technology Co., Limited, RAKwireless Technology Limited, Phoenix Contact GmbH & Co. KG, Seeed Technology Co., Ltd., Delta-T Devices Ltd, Hunter Industries Incorporated, Sony Semiconductor Solutions Corporation |

Frequently Asked Questions
The key players in the Soil Moisture Sensor Market include CropX Technologies Ltd., METER Group, Inc., Sensoterra International B.V., LI-COR, Inc., Sentek Pty Ltd, among others.
Key opportunities include analytics and subscription services, expanding irrigated area in Brazil, India, Southeast Asia, Africa and the Gulf, and use in sports turf, landscapes and construction monitoring.
The major growth factor is water scarcity, which pushes farmers and regulators toward measured irrigation supported by government modernization programs.
The Tensiometers segment dominated the Soil Moisture Sensor Market with approximately 27.86% share in 2025, because they measure soil water tension directly and have a long agronomic track record.
North America dominated the Soil Moisture Sensor Market with a 36.42% share in 2025, driven by large irrigated areas, mature precision agriculture and drought-driven water management in the United States.
