
Solar Panel Recycling Market Report Scope & Overview:
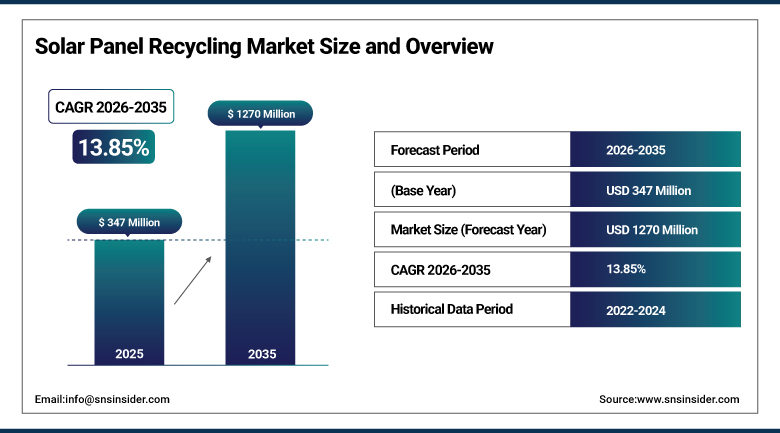
The Solar Panel Recycling Market was valued at USD 347 Million in 2025 and is expected to reach USD 1,270 Million by 2035, growing at a CAGR of 13.85% from 2026-2035.
Growth in the Solar Panel Recycling Market is being driven by rapid growth in solar photovoltaic installations and increase in the quantity of panels that reach end-of-life status. Environmental concerns relating to e-waste, resource conservation, and environmental pollution have led to the creation of waste management mechanisms by government authorities and other industry stakeholders. Growing need for recovered silicon, silver, aluminum, copper, and glass are making the recycling process more economically viable. Strict waste management regulations, extended producer responsibility, and sustainability goals are adding to the encouragement of manufacturers and solar power plants to resort to recycling. Technological advances in mechanical, thermal, chemical, and laser recycling processes are contributing towards higher efficiencies of material recovery and lower cost of the process.
In February 2025, PV Circonomy, a California-based startup, introduced a proprietary, highly automated recycling technology for end-of-life silicon photovoltaic panels. The energy-efficient process consumes only 1 kilowatt-hour per panel and complies with California's regulations banning chemical and thermal treatments in recycling processes.
To Get more information Solar Panel Recycling Market - Request Free Sample Report
Solar Panel Recycling Market Trends
-
Growing adoption of chemical separation processes recovering high-purity materials from end-of-life panels.
-
Rising volumes of early-loss panels retired before their design lifespan due to defects and upgrades.
-
Expanding regulatory emphasis on photovoltaic waste management under evolving national frameworks.
-
Increasing investment in automated recycling technology improving processing efficiency and cost economics.
-
Rising demand for laser-based recycling techniques enabling precise, minimal-loss material recovery.
-
Growing research into environmentally friendly recycling methods for emerging perovskite solar cell technology.
U.S. Solar Panel Recycling Market Overview
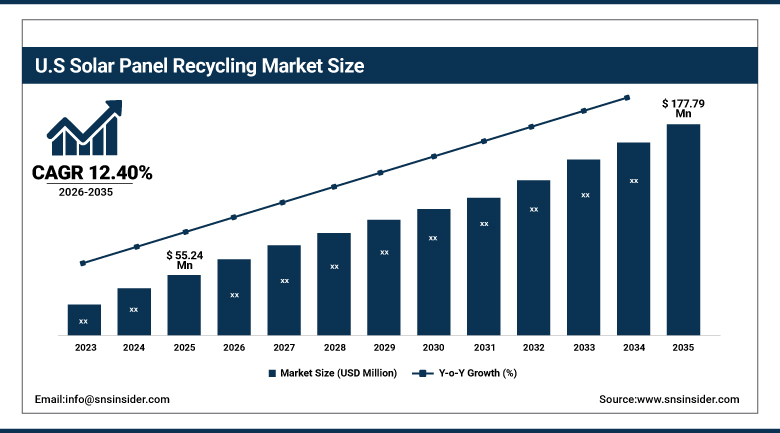
The U.S. Solar Panel Recycling Market was valued at USD 55.24 Million in 2025 and is expected to reach USD 177.79 Million by 2035, growing at a CAGR of 12.40% from 2026-2035.
Domestic demand continues to be underpinned by growing concerns over solar waste management and strong regulatory emphasis on electronic and photovoltaic waste, alongside a rapidly increasing number of domestic solar installations reaching the end of their operational lifecycle. Leading recyclers continue expanding automated, chemically compliant processing technology, while continued private capital investment keeps strengthening domestic recycling capacity. Significant investment in solar infrastructure further supports domestic market expansion, forecasting a surge in future waste volumes that positions U.S. recyclers to serve an increasingly large installed base of decommissioned panels nationwide.
In February 2025, researchers at Linköping University developed an environmentally friendly method to recycle perovskite solar cells using water as the primary solvent. The development reflects continued academic and industry investment in sustainable recycling technology extending beyond conventional silicon-based photovoltaic recovery processes.
Solar Panel Recycling Market Segment Analysis
-
By Type, the Monocrystalline segment dominated the market with a 48.60% share in 2025, while the Thin Film segment is the fastest growing with a CAGR of 10.10% during 2026-2035.
-
By Process, the Mechanical segment dominated the market with a 55.20% share in 2025, while the Chemical segment is the fastest growing with a CAGR of 18.50% during 2026-2035.
-
By Shelf Life, the Early Loss segment dominated the market with a 62.80% share in 2025, while the Normal Loss segment is the fastest growing with a CAGR of 10.20% during 2026-2035.
-
By End-User, the Industrial segment dominated the market with a 45.50% share in 2025, while the Residential segment is the fastest growing with a CAGR of 15.41% during 2026-2035.
By Type, Monocrystalline Dominates the Market and Thin Film Grows Fastest
Monocrystalline panels dominated the market in 2025, a position built on their status as the most widely deployed crystalline silicon technology across global solar installations, with over 95% of the solar panel market relying on crystalline silicon designs. Recyclers favour processing this panel type precisely because it delivers predictable, well-characterized material recovery economics across silicon, silver, and aluminum content, a combination that continues to make monocrystalline panels the default recycling feedstock across virtually every recycling facility worldwide, even as thin film volumes continue to expand around it.
Thin Film panels are projected to be the fastest-growing type category over the forecast period. Rising deployment of thin film technology across specific utility-scale and building-integrated applications continues to expand the addressable recycling feedstock base for this panel type as installed thin film capacity reaches end-of-life. As thin film panel installations from earlier deployment cycles increasingly reach decommissioning age, this segment continues to close the gap with crystalline silicon technology in overall market demand.
By Process, Mechanical Dominates the Market and Chemical Grows Fastest
Mechanical recycling dominated the market in 2025, reflecting its effectiveness in processing various panel materials at scale and its position as the most mature, widely deployed recycling technology across the industry. Recyclers favour mechanical processing precisely because it delivers proven, cost-effective material separation across the widest range of panel compositions, a combination that continues to make mechanical recycling the default specification across the substantial majority of commercial recycling facilities worldwide.
Chemical recycling is projected to be the fastest-growing process category over the forecast period, driven by advancements in chemical separation technologies capable of recovering higher-purity materials than conventional mechanical approaches. As recyclers increasingly seek to maximize material recovery value from complex, multi-layer panel compositions, chemical processing continues to close the gap with mechanical recycling in overall market demand.
By Shelf Life, Early Loss Dominates the Market and Normal Loss Grows Fastest
Early Loss panels dominated the market in 2025. Panels decommissioned before their design lifespan due to manufacturing defects, installation errors, weather damage, or replacement with more efficient alternatives continue to represent the largest single source of recyclable panel volume, particularly as rapid solar expansion saw entrants with unproven reliability enter the market. This foundational volume role continues to sustain early loss panels as the dominant shelf life category across the broader market.
Normal Loss panels are expected to be the fastest-growing shelf life category over the forecast period. As the industry's substantial installed base from earlier deployment cycles increasingly approaches its natural twenty-to-thirty-year design lifespan, panels reaching end-of-life through normal aging rather than premature failure continue to represent a growing share of overall recyclable volume. This structural shift continues to reshape shelf life demand patterns as the market matures.
By End-User, Industrial Dominates the Market and Residential Grows Fastest
Industrial end-users dominated the market in 2025, driven by large-scale solar installations and higher recycling volumes concentrated across utility-scale and industrial rooftop deployments. Industrial customers favour formal recycling partnerships precisely because they generate the concentrated panel volumes necessary to justify dedicated collection and processing logistics, a combination that continues to make industrial end-users the dominant customer segment across the broader market.
Residential end-users are expected to be the fastest-growing end-user category over the forecast period. Rising residential solar adoption over the past decade continues to expand the installed base of smaller-scale systems that will require recycling as these installations approach end-of-life. As residential solar deployment from earlier adoption waves increasingly reaches decommissioning age, this segment continues to close the gap with industrial and commercial end-users in overall market demand.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|
Asia Pacific |
China |
44.60% |
|
North America |
United States |
79.60% |
|
Europe |
Germany |
34.60% |
|
Latin America |
Brazil |
38.60% |
|
Middle East & Africa |
United Arab Emirates |
32.60% |
North America Solar Panel Recycling Market Insights
North America is projected to be the fastest-growing region, registering a CAGR of 12.40% during 2026-2035, driven by an increasing number of solar installations reaching the end of their lifecycle and growing concerns over solar waste management. The United States shapes regional demand through strong regulatory emphasis on electronic and photovoltaic waste alongside significant investment in solar infrastructure forecasting a surge in future waste volumes.
Canada contributes additional regional demand through its participation in North American renewable energy infrastructure development. Continued domestic recycling capacity investment is expected to keep North America expanding at the fastest pace of any region through the forecast period, even as Asia Pacific retains the larger overall revenue base.
Europe Solar Panel Recycling Market Insights
Europe accounts for a significant share of the global market based on strict Waste Electrical and Electronic Equipment regulation within the European Union and recycling technology that is increasing the recovery of photovoltaic end-of-life materials. The large installation of solar panels and manufacturing capability of Germany provide for regional demand, along with recycling infrastructure for both the domestic and wider European market of photovoltaic waste material.
France and other major European countries make up regular demand due to regional solar companies implementing recycling practices at the end of life for the solar panels. The focus on circular economy from the European Union continues to provide regular regional demand for solar panel recycling capabilities.
Asia Pacific Solar Panel Recycling Market Insights
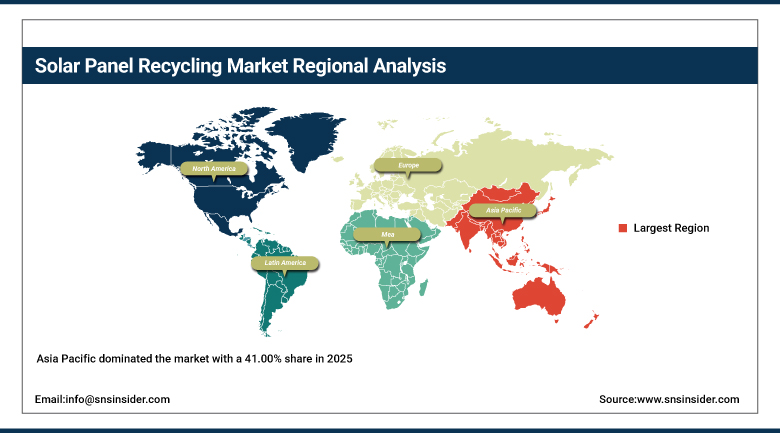
Asia Pacific dominated the market with a 41.00% share in 2025. The region's massive installed solar capacity, combined with an expanding domestic recycling infrastructure base, continues to anchor this leadership position across both established and rapidly developing solar markets. China continues to anchor regional demand as the world's largest solar panel manufacturer and installer, generating substantial recyclable panel volume as its extensive early-generation solar capacity approaches end-of-life.
India's solar panel recycling industry continues to evolve, driven by the expected retirement of aging photovoltaic systems, adding meaningful regional growth as domestic recycling infrastructure development accelerates. Japan and South Korea contribute further depth through established, technically advanced solar manufacturing and recycling sectors, positioning the wider region to sustain its position as the largest global market for solar panel recycling through the forecast period.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Solar Panel Recycling Market Insights
Latin America's market is anchored by Brazil, which accounts for the majority of regional demand on the strength of its growing solar installation base and expanding renewable energy infrastructure. Gradual growth in domestic recycling capacity continues to support steady regional market development.
The Middle East & Africa region continues to grow in strategic importance, with demand concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where extensive utility-scale solar project development is increasingly driving interest in end-of-life panel management. South Africa continues to anchor demand on the African continent, supported by its comparatively more developed renewable energy infrastructure.
Market Dynamics
Growth Drivers: Rising Panel Installation and Early-Loss Waste Volume
Increasing installation of solar panels across the globe represents the primary growth driver, as this rapid expansion continues to fuel the need for recycling to reduce waste generation from an industry generating rapidly growing volumes of end-of-life panel waste. This dynamic is reinforced by rapid solar expansion that saw entrants with unproven reliability enter the market, increasing failure rates and creating urgent demand for recycling solutions addressing early-loss panel volume.
Growing volume of solar panel waste provides an additional significant source of demand, as more solar panel systems continue nearing the end of their operational lives across markets with substantial installed capacity. Significant investment in solar infrastructure further supports market growth by forecasting a continued surge in future waste volumes requiring formal recycling capacity.
Restraints: Recycling Cost Economics and Hazardous Material Handling
Economic considerations relating to recycling costs are undoubtedly a real constraint to market expansion, given that the value that can be realized from materials recovered from standard silicon solar panels may sometimes not completely cover the cost of collection, transportation, and processing, as compared to just disposing of the panels in landfills, in places where there is no stringent regulation on the disposal of the material. This is more of a challenge for small-scale recyclers, whose processing capacities may not always reach the threshold of positive economics without enough density of solar panel waste in the region.
Another constraint relates to the handling of hazardous materials, in that solar panels contain materials such as lead and cadmium, among others, which need special handling, storage, and processing facilities.
Opportunities: Chemical Recovery Innovation and Emerging Market Infrastructure Development
Further innovation of chemical separation and recycling technology provides a significant potential opportunity for recyclers who develop technology able to recover higher purity material using less energy and thus attract the interest of solar developers looking for cost-effective and environmentally-friendly recycling partners. For recycling firms, advanced recycling technology is no longer a novelty factor but a real competitive edge in comparison with traditional mechanical separation alone.
Further infrastructure development of recycling facilities in emerging solar markets also provides a potential opportunity for recyclers, because those countries whose installed capacity of solar panels grows fast understand the necessity of having recycling capability before facing the growing volumes of waste.
Recent Developments:
-
2026: Canadian Solar reported that its 2025 sustainability efforts included recycling 6,909 end-of-life solar modules globally, highlighting continued progress toward resource efficiency and circular-economy practices.
-
2026: ENVARIS continues providing professional photovoltaic waste-management services covering solar modules, inverters and mounting structures, while also supporting reuse and recycling of materials including silicon, glass and metals.
-
2025: First Solar reported approximately 95% average material recovery from its global recycling facilities in 2024, with recovered glass, metals and semiconductor materials supporting resource recovery and circularity.
Solar Panel Recycling Market Key Players
-
Canadian Solar Inc.
-
Envela Corporation
-
Envaris GmbH
-
First Solar, Inc.
-
Hanwha Group
-
Reclaim PV Recycling Pty Ltd
-
Reiling GmbH & Co. KG
-
SILCONTEL LTD
-
Silrec Corporation
-
TotalEnergies SE
-
Total Green Recycling
-
Trina Solar Limited
-
We Recycle Solar
-
ROSI
-
Etavolt Pte. Ltd.
-
PV Circonomy
-
Veolia Environnement S.A.
-
ECS Refining
-
SolarCycle, Inc.
-
Rinovasol Group
Solar Panel Recycling Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 347 Million |
| Market Size by 2035 | USD 1,270 Million |
| CAGR | CAGR of 13.85% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Monocrystalline, Polycrystalline, Thin Film) • By Process (Mechanical, Thermal, Laser, Chemical) • By Shelf Life (Early Loss, Normal Loss) • By End-User (Industrial, Commercial, Residential) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Canadian Solar Inc., Envela Corporation, Envaris GmbH, First Solar, Inc., Hanwha Group, Reclaim PV Recycling Pty Ltd, Reiling GmbH & Co. KG, SILCONTEL LTD, Silrec Corporation, TotalEnergies SE, Total Green Recycling, Trina Solar Limited, We Recycle Solar, ROSI, Etavolt Pte. Ltd., PV Circonomy, Veolia Environnement S.A., ECS Refining, SolarCycle, Inc., Rinovasol Group |
Frequently Asked Questions
Key players include Canadian Solar, Envela Corporation, Envaris, First Solar, Hanwha Group, Reclaim PV Recycling, Reiling, SILCONTEL, Silrec Corporation, and TotalEnergies, among others.
Continued advancement of chemical separation and automated recycling technology and the continued development of recycling infrastructure across emerging solar markets represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by increasing installation of solar panels across the globe, combined with rapid solar expansion increasing failure rates and early-loss panel waste volume.
By Process, Mechanical recycling dominated the market with a 55.20% share in 2025, reflecting its effectiveness in processing various panel materials at scale.
Asia Pacific dominated the market with a 41.00% share in 2025, supported by the region's massive installed solar capacity, led by China.
