
Solid Oxide Fuel Cell for CHP Application Market Report Scope & Overview:
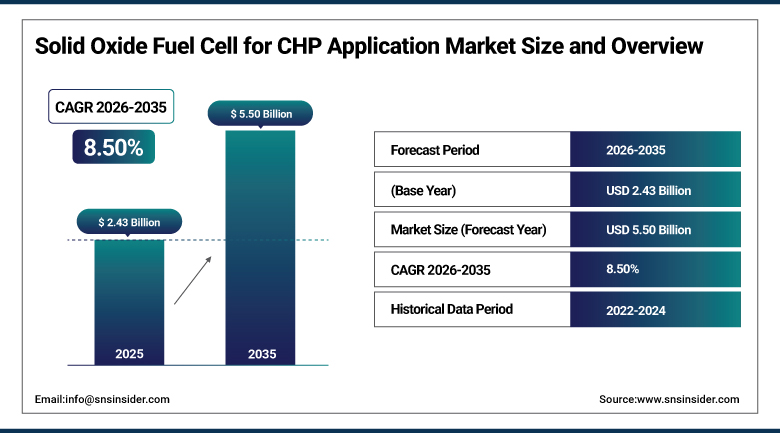
The Solid Oxide Fuel Cell for CHP Application Market was valued at USD 2.43 Billion in 2025 and is expected to reach USD 5.50 Billion by 2035, growing at a CAGR of 8.50% from 2026 to 2035.
The Solid Oxide Fuel Cell for CHP Application Market has quietly shifted from a niche decentralized-power technology into something genuinely strategic, as high-temperature ceramic electrochemical systems convert natural gas, biogas, or hydrogen directly into both electricity and usable heat with efficiency well above conventional gas engines. That dual-output capability, power and heat from a single conversion step, is exactly what makes SOFCs valuable for combined heat and power applications where recovering waste thermal energy meaningfully improves overall system economics. What is genuinely reshaping this category right now is demand from an entirely new customer type, AI data centers facing years-long grid interconnection delays are increasingly treating on-site SOFC generation as primary power rather than backup, a role reversal that barely existed in this market two years ago.
In 2025, Bloom Energy Corporation launched a new Combined Heat and Power (CHP) solution designed to increase system efficiency for its Energy Server platform, expanding beyond pure power generation into integrated thermal energy recovery.
To Get more information Solid Oxide Fuel Cell for CHP Application Market - Request Free Sample Report
Solid Oxide Fuel Cell for CHP Application Market Trends
-
Data center operators are increasingly deploying SOFC systems as primary on-site power rather than backup generation.
-
IP licensing business models are gaining traction, letting technology developers scale through manufacturing partners rather than direct production.
-
Infrastructure funds are forming multi-billion-dollar partnerships with SOFC developers to finance large-scale behind-the-meter deployments.
-
Micro-CHP systems continue expanding in residential and light commercial applications supported by favorable regulatory incentives.
-
Integration with hydrogen infrastructure is accelerating as SOFC systems demonstrate genuine fuel flexibility across natural gas and hydrogen blends.
U.S. Solid Oxide Fuel Cell for CHP Application Market Outlook
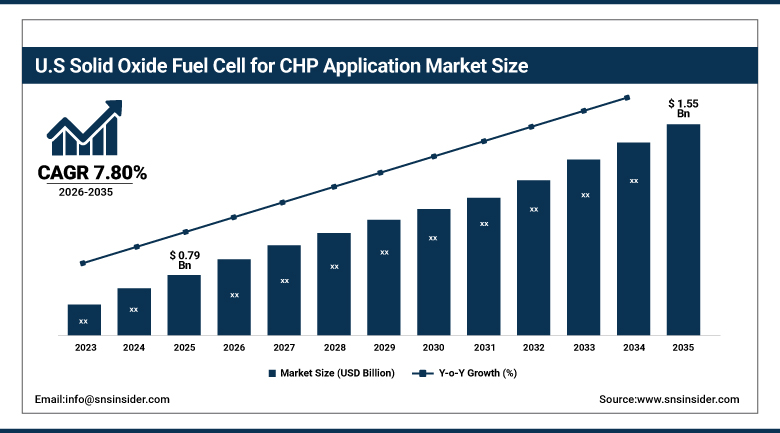
The U.S. Solid Oxide Fuel Cell for CHP Application Market was valued at USD 0.79 Billion in 2025 and is projected to reach USD 1.55 Billion by 2035, growing at a CAGR of 7.80% during 2026-2035.
The business case for using SOFC systems domestically has changed from a complementary power source to critical infrastructure to being a main power source due to prolonged interconnection delays of up to six to ten years and lack of funding for power grid upgrading and increased power demands from AI data centers. The region where solid oxide fuel cells are going to be deployed is now limited to the US market because of the increased need for power at data centers, favorable policies of the US government, especially the incentives under the Inflation Reduction Act, and heavy congestion of the power grid. Long-term service agreements and offtake agreements with power companies have become the key validation stage for technology suppliers, offering steady income generation from predictable, repetitive sources.
In October 2025, Brookfield Asset Management set up an investment vehicle worth USD 5 billion to deploy the SOFC technology by Bloom Energy Corporation at AI data centers worldwide.
Solid Oxide Fuel Cell for CHP Application Market Segment Analysis
-
By End-Use, commercial dominates the Solid Oxide Fuel Cell for CHP Application Market while industrial grows fastest, with commercial holding 51% share in 2025 and industrial registering a CAGR of 10.20% from 2026 to 2035.
-
By Fuel Type, natural gas dominates the Solid Oxide Fuel Cell for CHP Application Market while hydrogen grows fastest, with natural gas holding 58% share in 2025 and hydrogen registering a CAGR of 12.60% from 2026 to 2035.
-
By Scale, small scale dominates the Solid Oxide Fuel Cell for CHP Application Market while large scale grows fastest, with small scale holding 46% share in 2025 and large scale registering a CAGR of 11.40% from 2026 to 2035.
-
By Component, fuel cell stack dominates the Solid Oxide Fuel Cell for CHP Application Market while balance of plant grows fastest, with fuel cell stack holding 48% share in 2025 and balance of plant registering a CAGR of 10.80% from 2026 to 2035.
By End-Use, Commercial Dominates the Solid Oxide Fuel Cell for CHP Application Market While Industrial Grows Fastest
Commercial holds 51% of the Solid Oxide Fuel Cell for CHP Application Market, the largest single category, benefiting from favorable regulations that have driven large-scale demand for micro-CHP systems across office buildings, hotels, and mixed-use commercial developments seeking reliable, efficient on-site power and heat. Established commercial building energy management practices continue reinforcing this segment's position as the category's anchor end-use.
Industrial is growing at a 10.20% CAGR, the fastest pace among end-use categories, as data centers and industrial facilities increasingly deploy SOFC systems as primary power sources rather than backup generation, driven by persistent grid interconnection delays and surging electricity demand. Data centers specifically are expected to emerge as the fastest-growing end-user segment within the broader stationary fuel cell market, reinforcing industrial demand's above-average growth.
By Fuel Type, Natural Gas Dominates the Solid Oxide Fuel Cell for CHP Application Market While Hydrogen Grows Fastest
Natural Gas holds 58% of the market by fuel type, the largest single category, remaining the default fuel source thanks to existing pipeline infrastructure and established supply chains that let SOFC systems operate without requiring dedicated hydrogen production or delivery capability. This fuel flexibility advantage, converting readily available natural gas at high efficiency, keeps natural gas the practical default across most current commercial deployments.
Hydrogen is growing fastest, at a 12.60% CAGR, as advancements in hydrogen infrastructure and growing integration with the broader hydrogen economy increasingly position SOFC systems as a genuine bridge technology between conventional gas-fired generation and fully renewable hydrogen power. Growing investment in green hydrogen production and blending pilot programs continues reinforcing this fuel type's above-average growth trajectory.
By Scale, Small Scale Dominates the Solid Oxide Fuel Cell for CHP Application Market While Large Scale Grows Fastest
Small Scale holds 46% of the market by scale, the largest single category, reflecting how deeply micro-CHP systems in the 5 to 50 kilowatt range have penetrated residential and light commercial applications where compact, modular deployment matters more than raw output capacity. Favorable regulations supporting distributed micro-CHP adoption continue reinforcing small-scale systems' dominant position.
Large Scale is growing fastest, at an 11.40% CAGR, as data center and industrial backup power applications increasingly require systems in the 100 kilowatt to multi-megawatt range capable of supporting mission-critical, continuous power demand. Companies deploying SOFC technology have surpassed well over 1,000 megawatts of installed stationary capacity, providing operational validation that is accelerating large-scale system adoption.
By Component, Fuel Cell Stack Dominates the Solid Oxide Fuel Cell for CHP Application Market While Balance of Plant Grows Fastest
Fuel Cell Stack holds 48% of the market by component, the largest single category, since the stack represents the core electrochemical conversion technology and the single most capital-intensive component of any SOFC system, anchoring both system cost and overall performance characteristics. Continued R&D investment in stack efficiency and durability keeps this component the category's primary competitive battleground.
Balance of Plant is growing fastest, at a 10.80% CAGR, as system integrators increasingly focus on the supporting infrastructure, thermal management, fuel processing, and power conditioning that determines how reliably a SOFC system actually performs in continuous commercial deployment. Growing system complexity for large-scale, grid-independent installations is reinforcing demand for increasingly sophisticated balance of plant engineering.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.40% |
|
Asia Pacific |
Japan |
33.60% |
|
Europe |
Germany |
26.40% |
|
Middle East & Africa |
UAE |
17.20% |
|
Latin America |
Brazil |
26.50% |
North America Solid Oxide Fuel Cell for CHP Application Market Insights
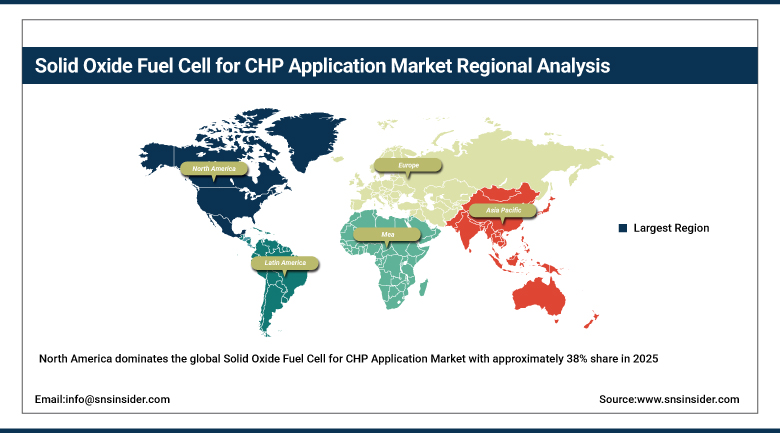
North America dominates the global Solid Oxide Fuel Cell for CHP Application Market with approximately 38% share in 2025, driven by surging data center power demand, favorable federal policy, and severe grid congestion that has made behind-the-meter generation a genuine necessity rather than an alternative. Growth here, registering a CAGR of approximately 8.90% during 2026-2035, is concentrating heavily around large-scale commercial deployments tied to AI infrastructure build-out rather than traditional CHP applications alone.
The United States accounts for approximately 85.40% of the North American market, reflecting its concentration of leading SOFC technology developers and the country's status as the epicenter of large-scale commercial deployment tied to AI data center growth. Canada contributes a smaller but steady share, tied to its own industrial energy infrastructure and comparable regulatory incentives.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Solid Oxide Fuel Cell for CHP Application Market Insights
Europe's solid oxide fuel cell for CHP application market is mature and steady, supported by supportive policies and incentives for SOFC installation in major countries such as Germany, reinforced by the region's strong commitment to decarbonization and distributed energy generation. Established industrial and commercial CHP adoption traditions across the region continue supporting steady demand.
Germany leads the European market with a 26.40% share, supported by its strong government incentive programs and advanced fuel cell manufacturing and research base. The United Kingdom and France follow, with demand in both countries tied to expanding decentralized energy generation and growing commercial CHP adoption.
Asia Pacific Solid Oxide Fuel Cell for CHP Application Market Insights
Asia-Pacific is witnessing growth at a rate higher than any other region in the market with a CAGR of about 9.60% from 2026 to 2035 due to developments in fuel cell technology which improve efficiency along with governmental incentives in major economies for installing SOFCs. The region had Japan and South Korea leading in using fuel cells for utilities as well as residential purposes, and this was because of the technological and manufacturing expertise already present in these nations.
Japan has a share of around 33.60% in this regional market owing to its established manufacturing base for SOFCs and existing governmental incentives in favor of fuel cells. South Korea and China are witnessing a fast growth in this market due to manufacturing and licensing agreements, whereas India is contributing via investments in industrial energy infrastructure.
Middle East & Africa and Latin America Solid Oxide Fuel Cell for CHP Application Market Insights
Middle East & Africa Region is experiencing steady growth due to increasing industrial energy infrastructure investments in the Gulf countries owing to the increasing demand for distributed and off-grid power generation technologies for the critical installations. The region of Latin America is following a similar path of growth due to increased industrial capacity in Brazil and interest in decentralized and efficient power generation technology in the region.
UAE is the leader in the market for Middle East & Africa region holding 17.20% share due to its position as a regional center for energy infrastructure investment. Brazil accounts for 26.50% share in the Latin American market due to industrial energy demands while Mexico is another important contributor in the region.
Market Dynamics
Growth Drivers: Data Center Power Demand and Grid Congestion Fueling Market Growth
Surging electricity demand from AI data centers, combined with persistent grid interconnection delays that can take six to ten years in many regions, is the clearest driver behind this market's growth, as behind-the-meter SOFC generation increasingly becomes a genuine necessity rather than an alternative power source. Rising demand for high-efficiency and low-emission power systems across commercial buildings and industrial facilities is reinforcing this demand, as organizations prioritize distributed generation technologies that reduce grid dependency.
Growing focus on grid resilience, coupled with advancements in hydrogen infrastructure, is boosting SOFC deployment across both developed and emerging markets as governments and enterprises alike prioritize decarbonization and energy security simultaneously.
Restraints: High Initial Capital Costs and Technical Barriers Limiting Market Expansion
High capital cost in the beginning is still an issue, especially when it comes to small-scale projects involving commercial or residential customers since the high initial capital can prove hard to justify without service contracts in place. It seems like the technical entry barriers and huge capital necessary to compete effectively have proven quite significant, as evidenced by the fact that one big tech company decided to abandon the SOFC concept due to increased restructuring pressures.
Fueling problems, especially in cases of hydrogen-powered SOFC systems which do not enjoy the advantage of having a preexisting fuel distribution pipeline system like natural gas does, may pose problems in areas without any hydrogen distribution network in place.
Opportunities: Data Center Deployment and Hydrogen Economy Integration Creating New Growth Avenues
Expansion in data centers and critical infrastructure represents a significant growth opportunity, as SOFC technology increasingly proves its readiness for the 24/7, high-load-factor requirements this application demands, backed by growing operational data demonstrating five-nines availability. Technology providers who can meet this reliability bar stand to capture substantial multi-gigawatt deployment opportunities as AI infrastructure build-out continues accelerating.
Integration with renewable energy sources and the broader hydrogen economy offers a second clear opportunity, particularly as SOFC systems' genuine fuel flexibility positions them as a credible bridge technology supporting the gradual transition from natural gas toward fully renewable hydrogen power generation.
Recent Developments:
-
July 2025: Doosan Fuel Cell Co., Ltd., a licensing partner of Ceres Power Holdings plc, began mass production of solid oxide fuel cell technology in South Korea, targeting the AI data center market.
-
November 2025: Ceres Power Holdings plc signed a licensing agreement with Weichai Power Co., Ltd. to manufacture its solid oxide fuel cell technology for the Chinese market.
-
June 2025: FuelCell Energy, Inc. abandoned its solid oxide fuel cell platform, recording a USD 64.5 million impairment charge, and restructured to focus on its core carbonate fuel cell and electrolysis technologies.
-
2024: Sunfire GmbH spun off its solid oxide fuel cell business to concentrate on its solid oxide electrolyzer cell technology for green hydrogen production, while retaining a combined backlog exceeding 800 MW.
Solid Oxide Fuel Cell for CHP Application Market key players are:
-
FuelCell Energy, Inc.
-
Bloom Energy Corporation
-
Ceres Power Holdings plc
-
Mitsubishi Power, Ltd.
-
Convion Ltd.
-
Sunfire GmbH
-
Hexis AG
-
Elcogen AS
-
Kyocera Corporation
-
Aisin Corporation
-
Miura Co., Ltd.
-
Rolls-Royce Holdings plc
-
Solidpower S.p.A.
-
Topsoe A/S
-
Weichai Power Co., Ltd.
-
Cummins Inc.
-
AVL List GmbH
-
Watt Fuel Cell Corporation
-
Fraunhofer IKTS
-
Doosan Fuel Cell Co., Ltd.
Solid Oxide Fuel Cell for CHP Application Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.43 Billion |
| Market Size by 2035 | USD 5.50 Billion |
| CAGR | CAGR of 8.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By End-Use (Residential, Commercial, Industrial) • By Fuel Type (Natural Gas, Biogas, Hydrogen) • By Scale (Small Scale, Medium Scale, Large Scale) • By Component (Fuel Cell Stack, Balance of Plant, Power Conditioning System) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | FuelCell Energy, Inc., Bloom Energy Corporation, Ceres Power Holdings plc, Mitsubishi Power, Ltd., Convion Ltd., Sunfire GmbH, Hexis AG, Elcogen AS, Kyocera Corporation, Aisin Corporation, Miura Co., Ltd., Rolls-Royce Holdings plc, Solidpower S.p.A., Topsoe A/S, Weichai Power Co., Ltd., Cummins Inc., AVL List GmbH, Watt Fuel Cell Corporation, Fraunhofer IKTS, Doosan Fuel Cell Co., Ltd. |
Frequently Asked Questions
Key players include Bloom Energy Corporation, Ceres Power Holdings plc, FuelCell Energy, Inc., Mitsubishi Power, Ltd., Sunfire GmbH, Kyocera Corporation, Doosan Fuel Cell Co., Ltd., and Weichai Power Co., Ltd., alongside other established fuel cell technology providers.
Key opportunities include expansion in data centers and critical infrastructure requiring reliable on-site power, integration with the broader hydrogen economy, and growing licensing and manufacturing partnership business models.
The market is driven by surging electricity demand from AI data centers, persistent grid interconnection delays, and rising demand for high-efficiency, low-emission power systems.
The Commercial segment dominated the Solid Oxide Fuel Cell for CHP Application Market in 2025.
The North America region dominated the Solid Oxide Fuel Cell for CHP Application Market in 2025, driven by surging data center power demand and favorable federal policy.
