
Sustainable Aviation Fuel Market Report Scope & Overview:
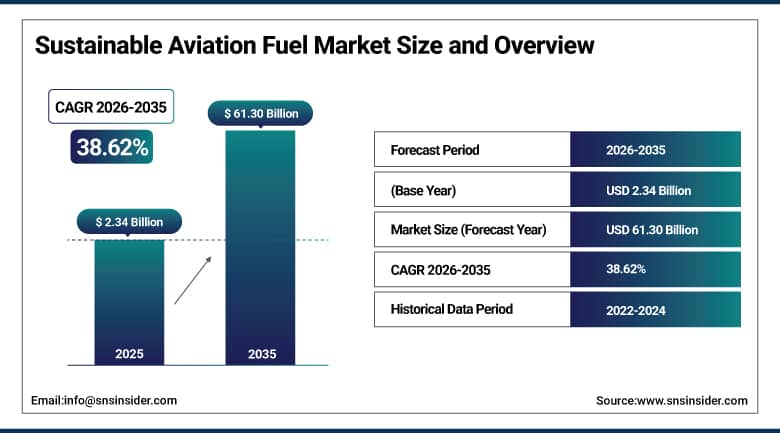
The Sustainable Aviation Fuel Market was valued at USD 2.34 Billion in 2025 and is expected to reach USD 61.30 Billion by 2035, growing at a CAGR of 38.62% from 2026-2035.
Market for sustainable aviation fuel continues growing as a fast-growing market because airlines, government organizations, and fuel manufacturers attempt to mitigate aviation’s CO2 emissions that cannot currently be mitigated with available electric and hydrogen technologies. Sustainable aviation fuel is a direct drop-in substitute for existing jet fuel and is produced from biomass and waste feedstocks, such as used cooking oil, animal fats, agricultural residues, municipal wastes, ethanol, and carbon capture coupled with green hydrogen. In comparison with fossil jet fuel, sustainable aviation fuel can cut greenhouse gas emissions during its life cycle by 80 percent or even higher. This fuel can be blended with regular fuel without any modifications of aircrafts. Blending mandates such as ReFuelEU Aviation, which requires 2% SAF in 2025 rising to 6% in 2030 and 70% by 2050, along with UK mandates and U.S. tax credits, are driving investment.
⮞Power-to-liquid fuel development in Africa advanced when Phelan Green Group reached, in September 2026, a final investment decision on the first phase of its eSAF project in South Africa, targeting production of 35,000 tonnes of electrofuel-based sustainable aviation fuel using renewable hydrogen and captured carbon.
To Get More Information On Sustainable Aviation Fuel Market - Request Free Sample Report
Sustainable Aviation Fuel Market Trends:
-
Rising SAF blending mandates under ReFuelEU Aviation and UK regulations.
-
Growing airline offtake agreements for neat and blended SAF.
-
Expanding alcohol-to-jet production from ethanol feedstocks.
-
Increasing final investment decisions for power-to-liquid eSAF projects.
-
Rising refinery co-processing and conversion to renewable fuels production.
-
Growing book-and-claim systems for corporate Scope 3 emission reductions.
U.S. Sustainable Aviation Fuel Market Outlook:
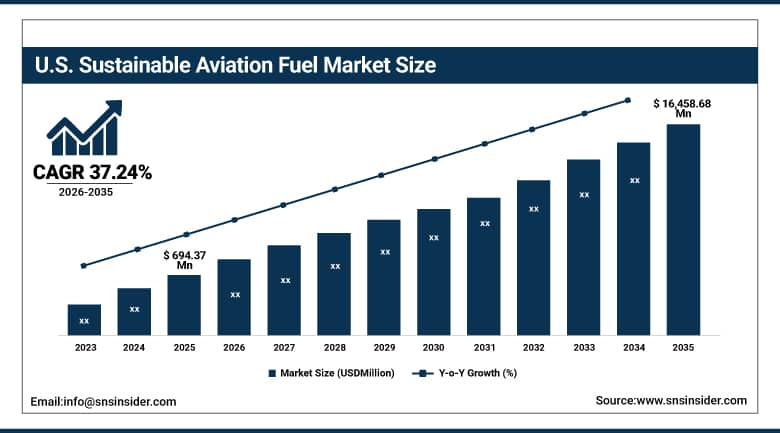
The U.S. Sustainable Aviation Fuel Market was valued at USD 694.37 Million in 2025 and is expected to reach USD 16,458.68 Million by 2035, growing at a CAGR of 37.24% from 2026-2035.
The U.S. Sustainable Aviation Fuel Market is experiencing continued growth, fueled by government tax credits for the production of clean fuels, state low carbon fuel standards, and increased demand from airlines and corporations for low emission flights. The SAF Grand Challenge has established a target of achieving production capacity of 3 billion gallons of SAF annually by the year 2030, aided by incentives available in California, Illinois, Washington, Minnesota, and Oregon. Montana Renewables, World Energy, Diamond Green Diesel, Phillips 66, among others, have plants in operation or under expansion for SAF production. The company LanzaJet has the world's first ethanol-to-SAF plant operating in Georgia. Airlines including United, Delta, American, Southwest, Alaska, JetBlue, and FedEx have entered into offtake agreements with the producers. There is plenty of availability of agricultural raw materials for SAF production.
⮞U.S. sustainable aviation fuel capacity planning advanced when SkyNRG selected, in September 2026, Technip Energies, Sasol, and Topsoe for the front-end engineering design phase of Project Wigeon in Washington State, a planned facility designed to produce 50 million gallons of SAF per year with start-up targeted for 2031.
Sustainable Aviation Fuel Market Segment Analysis:
-
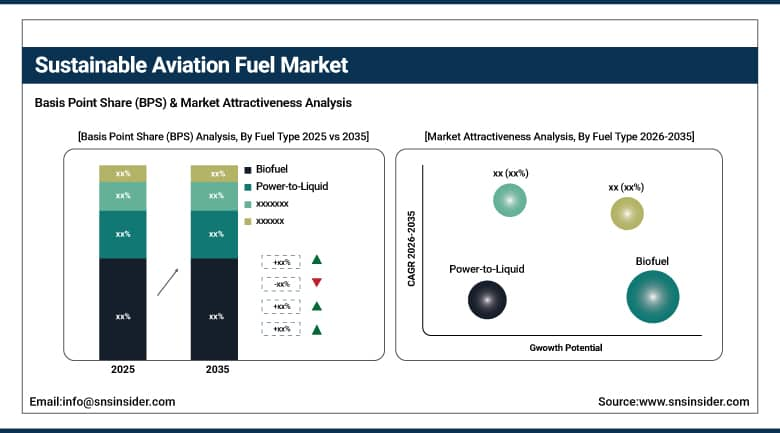
By Fuel Type, the Biofuel segment dominated the Sustainable Aviation Fuel Market with approximately 94.62% share in 2025, while the Power-to-Liquid segment is the fastest growing with a CAGR of approximately 72.48%.
-
By Conversion Pathway, the HEFA-SPK segment dominated the Sustainable Aviation Fuel Market with approximately 82.36% share in 2025, while the Alcohol-to-Jet segment is the fastest growing with a CAGR of approximately 58.42%.
-
By Blending Capacity, the Below 30% segment dominated the Sustainable Aviation Fuel Market with approximately 68.42% share in 2025, while the 30% to 50% segment is the fastest growing with a CAGR of approximately 42.36%.
-
By Aircraft Type, the Commercial Aviation segment dominated the Sustainable Aviation Fuel Market with approximately 84.26% share in 2025, while the Business & General Aviation segment is the fastest growing with a CAGR of approximately 41.84%.
By Fuel Type, Biofuel Dominates the Sustainable Aviation Fuel Market and Power-to-Liquid Grows Fastest
Biofuel-based SAF led the market in 2025 due to the almost exclusive use of biological sources for the existing production processes. These biological sources include waste cooking oil, animal fat, vegetable oils, agricultural waste, and ethanol. Additionally, biofuel SAF is further aided by sustainability certification programs that already exist throughout the world. The biofuel production process is commercially available and certified under the ASTM D7566 standard, with support from the existing refinery capacity. Companies such as Neste, World Energy, Montana Renewables, Diamond Green Diesel, and TotalEnergies provide biofuel SAF to airlines globally.
Power-to-liquid SAF is the fastest-growing fuel type due to the development of green hydrogen from electrolysis along with CO2 capture for synthetic jet fuel. A number of eSAF pilots are currently operational in Europe. Power-to-liquid fuels, also referred to as eSAF, are low-emission fuels and not constrained by availability of bio-based feedstocks. ReFuelEU Aviation has a synthetic fuel sub-mandate which begins at 1.2% in 2030. The mandate ensures a guaranteed demand. Examples of such projects include eSAF plant of Phelan Green Group in South Africa, Arcadia eFuels project in Denmark, Twelve, and Infinium projects. Mandates for fuel types will drive the fastest growth among all the segments.
⮞June 2026: The UK government announced a £219 million Low Carbon Fuels Fund, including £93 million for projects developing and scaling domestic low-carbon fuel production. The initiative creates potential support for emerging SAF production technologies, including synthetic-fuel pathways.
By Conversion Pathway, HEFA-SPK Dominates the Sustainable Aviation Fuel Market and Alcohol-to-Jet Grows Fastest
HEFA-SPK, or hydroprocessed esters and fatty acids, led the market in 2025 due to its maturity and widespread commercial application as a SAF production pathway. HEFA plants are capable of producing renewable diesel as well, thus providing producers with more flexibility in terms of their products. HEFA involves the production of jet fuel from waste oils, fats, and vegetable oils through hydrotreatment, a process that resembles renewable diesel production. Some of the companies operating HEFA plants include Neste, World Energy, Montana Renewables, Diamond Green Diesel, Phillips 66, and Enilive.
⮞February 2026: SkyNRG reached financial close and began construction of its DSL-01 SAF facility in Delfzijl, the Netherlands. The plant is designed to produce 100,000 tonnes of SAF annually using the hydroprocessed esters and fatty acids pathway, marking progress toward dedicated commercial-scale production.
Alcohol-to-jet is the fastest-growing conversion pathway as manufacturers are using ethanol and isobutanol to produce jet fuel and widen the pool of feedstocks, which previously was limited to waste oils and fats. The alcohol-to-jet pathway also enables manufacturers to use cellulosic ethanol produced from agricultural waste, which widens the number of feedstock options. LanzaJet's Freedom Pines Fuels located in Georgia is the first ever ethanol-to-SAF production facility and other companies, including Gevo, are planning to build even bigger plants. Huge production of ethanol from corn, sugarcane, and cellulosic feedstocks in the US and Brazil helps alcohol-to-jet grow. Collaboration with airlines, such as British Airways within the Project Speedbird, helps to grow fastest.
By Blending Capacity, Below 30% Dominates the Sustainable Aviation Fuel Market and 30% to 50% Grows Fastest
The Below 30% blending segment led the market in 2025 due to the fact that most SAFs are presently blended with traditional aviation fuel at low rates to fulfill the mandates and the airlines' requirements while keeping in view the limitations regarding costs and availability. The process of blending is generally carried out at the fuel terminals prior to the transportation to the airports. Low percentage blends are provided via the airport fuel infrastructure without any change in the process. In 2025 and 2026, both the EU and UK mandates call for low blend rates, and most of the off-take volumes of the airlines are available in low blends at the hub airports.
⮞March 2025: Airbus introduced SAF at its A220 assembly site in Mirabel, Canada, enabling production, customer-acceptance, and test flights using a 30% SAF blend. Airbus expected more than 600,000 litres of blended SAF to be used at the site during 2025.
The 30% to 50% blending segment is the fastest-growing category as the volume of production of SAF increases and airlines look towards making deeper emission cuts for their flights. Airlines have conducted flights using 100% SAF in one of their engines. Presently, the ASTM specifications permit blending of up to 50% of SAF with regular jet fuel. Greater blending levels are being experimented by various airlines for demonstration projects and special supply purposes. Airlines and companies that use flights are investing in such higher blend flights to meet their sustainability goals. The aircraft manufacturers and engine manufacturers have also been conducting tests for 100% SAF to certify it for commercial use.
By Aircraft Type, Commercial Aviation Dominates the Sustainable Aviation Fuel Market and Business & General Aviation Grows Fastest
Commercial aviation led the market in 2025 due to high demands for jet fuel by passenger airlines and freight carriers. Commercial aircraft is the segment that uses the most jet fuel in the world. Commercial airlines, such as United, Delta, American, Air France-KLM, Lufthansa, International Airlines Group (IAG), Singapore Airlines, and Qantas Airways have made large-scale purchase agreements for SAF. Freighter airlines like FedEx, UPS, and SF Airlines have also purchased SAF. ReFuelEU Aviation and the UK SAF mandate regulations apply to fuel produced at airports to be used by commercial aircrafts.
Business and general aviation is the fastest-growing aircraft type due to the use of SAF by private jet operators, fractional ownership firms, and fixed-base operators to deal with issues of sustainability that affluent customers face. Some fixed-base operators have begun to provide SAF blends at business aviation airports in Europe and the United States. Ambitious net-zero targets have been set by business aviation firms, and many operators are providing SAF solutions to their customers. The provision of SAF blends is becoming more common at fixed-base operators in large business aviation airports. Willingness to pay higher prices by business aviation customers facilitates premium pricing for SAF.
⮞August 2026: Gulfstream and Rolls-Royce completed a G800 flight using 100% SAF. The flight formed part of high-altitude testing to examine potential effects on contrail-forming particles, demonstrating the business aviation sector’s work on SAF compatibility and environmental performance.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
91.36% |
|
Asia Pacific |
Singapore |
28.64% |
|
Europe |
Netherlands |
22.48% |
|
Latin America |
Brazil |
52.36% |
|
Middle East & Africa |
United Arab Emirates |
38.42% |
Europe Sustainable Aviation Fuel Market Insights
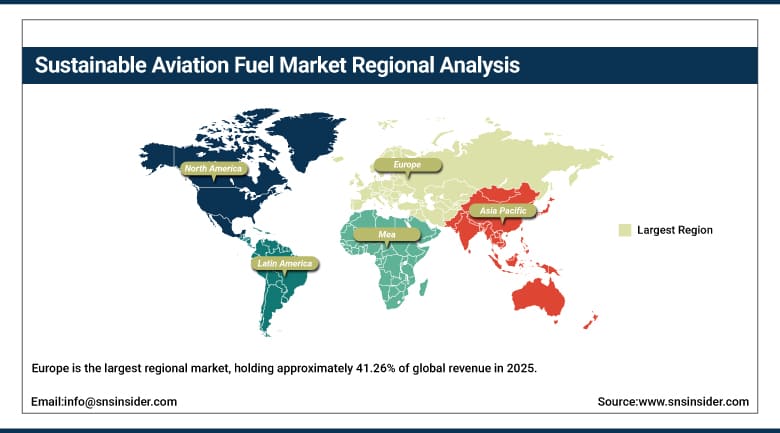
Europe is the largest regional market, holding approximately 41.26% of global revenue in 2025, supported by ReFuelEU Aviation, which requires fuel suppliers to blend 2% SAF at EU airports in 2025, rising to 6% in 2030, 20% in 2035, and 70% by 2050. European airports are also introducing incentive schemes for airlines using SAF, and fuel suppliers face significant penalties for failing to meet blending obligations under the regulation. The Netherlands is a leading country market, with Neste's Rotterdam refinery and SkyNRG's projects supplying SAF to Amsterdam Schiphol and other hubs. TotalEnergies, Shell, OMV, BP, Enilive, Repsol, and Moeve are converting refineries and building new SAF capacity across the region.
⮞September 2026: The UK government published provisional statistics on SAF supplied under its mandate, providing updated information on market implementation and fuel supply. Such reporting helps industry participants track compliance and evaluate progress toward mandated SAF adoption.
The United Kingdom has introduced its own SAF mandate and revenue certainty mechanism, supporting projects such as LanzaJet's Project Speedbird with British Airways and Nova Pangaea. European airlines are also among the largest buyers of SAF through long-term offtake agreements and corporate programs. Germany, France, Spain, Italy, and the Nordic countries are developing HEFA, alcohol-to-jet, and power-to-liquid projects. Synthetic fuel sub-mandates under ReFuelEU are driving eSAF projects such as Arcadia eFuels in Denmark, which signed a 10-year offtake agreement with Uniper. Binding mandates and strong airline commitments are expected to keep Europe the largest regional market over the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Sustainable Aviation Fuel Market Insights
North America accounted for approximately 32.48% of the global Sustainable Aviation Fuel Market in 2025, supported by federal tax credits, state low carbon fuel standards, abundant agricultural feedstocks, and strong airline demand. Corporate buyers in the region are also purchasing SAF certificates to reduce business travel emissions. Montana Renewables, World Energy, Diamond Green Diesel, Phillips 66, LanzaJet, and Gevo are producing or developing SAF capacity across the region. Montana Renewables announced plans to expand to 200 million gallons per year by the end of 2028, while major U.S. airlines and freight carriers continue to sign multiyear offtake agreements with producers.
⮞June 2026: Twelve opened AirPlant One in Moses Lake, Washington, a commercial-scale facility producing synthetic E-Jet fuel from captured carbon dioxide, renewable electricity, and water. The opening marks a milestone for U.S. power-to-liquid SAF production.
The United States anchors regional demand through the SAF Grand Challenge, California's Low Carbon Fuel Standard, and state SAF tax credits in Illinois, Washington, and Minnesota. Several U.S. airports are also expanding SAF blending and storage infrastructure to support growing airline demand. Canada is developing SAF production through refinery co-processing and new projects in Alberta and British Columbia, supported by its Clean Fuel Regulations. Mexico is exploring SAF production from agricultural residues and used cooking oil. Although changes to federal tax credits may affect some projects, strong feedstock availability and airline commitments are expected to support significant regional growth over the forecast period.
Asia Pacific Sustainable Aviation Fuel Market Insights
Asia Pacific is the fastest-growing regional market, holding approximately 18.36% of global revenue in 2025 and expanding at a CAGR of approximately 44.86% from 2026 to 2035. Rapid growth in air travel across the region is increasing jet fuel demand, while governments are introducing SAF policies to address aviation emissions and support local production. The region's growth reflects new SAF mandates and targets in Singapore, Japan, South Korea, India, and China, along with large used cooking oil feedstock supplies. Singapore introduced a SAF levy on departing flights, while Neste's Singapore refinery is one of the world's largest SAF production facilities, supplying airlines across the region and internationally.
⮞February 2026: Singapore’s Civil Aviation Authority, the Singapore Sustainable Aviation Fuel Company, and nine organizations launched the country’s first voluntary centralized SAF procurement trial. The initiative aggregates corporate demand to support SAF purchasing and adoption across the aviation ecosystem.
Japan targets 10% SAF use by 2030, with Cosmo Oil, ENEOS, and Idemitsu developing production capacity. Regional airlines are also signing long-term offtake agreements with local and international SAF producers. China is launching SAF pilot programs at major airports, and producers such as EcoCeres supply blended SAF to SF Airlines and other carriers. India has set SAF blending targets for international flights and is developing alcohol-to-jet production from sugarcane ethanol. South Korea and Australia are introducing mandates and supporting local production. Strong policy momentum, feedstock availability, and rising air travel are expected to keep Asia Pacific the fastest-growing regional market.
MEA & Latin America Sustainable Aviation Fuel Market Insights
The Middle East & Africa represents a growing market, led by the United Arab Emirates, Saudi Arabia, Qatar, and South Africa. Gulf airlines are also signing SAF agreements as part of broader sustainability commitments for their fleets. The United Arab Emirates has set national SAF targets, with ADNOC, Masdar, and Emirates exploring production and supply. Saudi Arabia is evaluating SAF production as part of its energy diversification strategy. South Africa is emerging as a power-to-liquid hub, with Phelan Green Group reaching a final investment decision on its eSAF project. Abundant solar resources across the region support future synthetic fuel production for regional and export markets.
⮞November 2025: Emirates and ENOC signed an MoU to explore sustainable aviation fuel supply at Emirates’ Dubai hub. The collaboration covers supply-chain infrastructure, production capabilities, and commercial feasibility, supporting development of the UAE’s SAF supply ecosystem.
Latin America is developing steadily, supported by Brazil, Colombia, Chile, and Uruguay. Regional development banks are also financing SAF feasibility studies and early projects in several Latin American countries. Brazil's Fuel of the Future law establishes SAF requirements for national flights starting in 2027, and the country's large sugarcane ethanol industry supports alcohol-to-jet production. Uruguay is developing NovaSAF-1 with Syzygy Plasmonics under a framework agreement with the International Finance Corporation. Chile is evaluating power-to-liquid projects using wind and solar resources. Abundant feedstocks, supportive policies, and renewable resources are expected to support strong growth across both regions over the forecast period.
⮞August 2026: Brazil regulated its National Sustainable Aviation Fuel Program, ProBioQAV. The decree establishes implementation rules for SAF production, certification, commercialization, and aviation emissions-reduction targets, creating a clearer framework for investment in the country’s emerging SAF market.
Market Dynamics:
Growth Drivers: Government Blending Mandates and Incentives and Airline Decarbonization Commitments
Government blending mandates and incentives represent the primary driver of Sustainable Aviation Fuel Market growth, as regulators require fuel suppliers and airlines to use increasing amounts of SAF. Mandates also include penalties for suppliers that fail to comply. ReFuelEU Aviation sets binding SAF shares at EU airports rising from 2% in 2025 to 70% in 2050, while the United Kingdom has introduced a similar mandate. The United States supports SAF through clean fuel production tax credits and state incentives, and countries including Japan, Singapore, India, and Brazil have adopted targets or mandates. These policies create guaranteed demand and encourage investment in new production capacity.
Airline decarbonization commitments are further strengthening market growth, as carriers pursue the aviation industry's goal of net-zero carbon emissions by 2050. Airline alliances are also coordinating SAF procurement to strengthen buying power and accelerate supply. SAF is expected to provide the largest share of emission reductions, as hydrogen and electric aircraft will take decades to scale. Airlines including United, Delta, Air France-KLM, Lufthansa, IAG, and Singapore Airlines have signed long-term offtake agreements for SAF. Corporate customers are purchasing SAF certificates to reduce business travel and freight emissions. These commitments provide revenue certainty that supports financing for new SAF production facilities worldwide.
⮞September 2026: The UK published its first provisional SAF mandate statistics for 2026, reflecting continued implementation of mandatory SAF supply requirements. Binding obligations and reporting requirements encourage fuel suppliers to expand eligible production and help airlines prepare for increasingly stringent decarbonization targets.
Restraints: High Production Costs and Limited Sustainable Feedstock Availability
High production costs remain a key restraint on the Sustainable Aviation Fuel Market, as SAF typically costs two to five times more than conventional jet fuel depending on the production pathway. Securing long-term feedstock supply contracts also adds cost and complexity for new producers. HEFA-based SAF is the lowest-cost option, but alcohol-to-jet, Fischer-Tropsch, and power-to-liquid pathways require higher capital investment and energy inputs. Airlines operate on thin margins and face challenges absorbing these costs without passing them to customers. Uncertainty around the duration and value of tax credits and incentives can also delay final investment decisions for new production facilities.
Limited sustainable feedstock availability further restrains market growth, as waste oils and fats used in HEFA production are constrained in supply and face competition from renewable diesel producers. Feedstock competition with renewable diesel producers is likely to intensify further as mandates rise. Concerns about fraud in used cooking oil supply chains and sustainability certification add complexity. Expanding to agricultural crops raises questions about land use and food competition. Advanced feedstocks such as agricultural residues, municipal waste, and captured carbon require newer, less proven technologies. These constraints limit how quickly SAF production can scale to meet rising mandates and airline demand.
Opportunities: Power-to-Liquid eSAF Production and Alcohol-to-Jet Expansion
Power-to-liquid eSAF production presents significant opportunities for the Sustainable Aviation Fuel Market, as synthetic fuels made from green hydrogen and captured carbon dioxide are not constrained by biological feedstocks. Long-term offtake agreements for eSAF are also steadily improving project bankability for developers and investors. ReFuelEU Aviation's synthetic fuel sub-mandate creates dedicated demand, while falling renewable electricity and electrolyzer costs are expected to improve economics over time. Developers including Phelan Green Group, Arcadia eFuels, Twelve, Infinium, and Synhelion are advancing projects. Regions with abundant low-cost renewable power, such as the Middle East, Africa, Chile, and Australia, can become major eSAF exporters.
Alcohol-to-jet expansion presents a further opportunity, as large global ethanol production capacity can be converted into SAF, significantly expanding feedstock availability. Brazil and India also have large ethanol industries that could support future alcohol-to-jet production. The United States and Brazil produce large volumes of corn and sugarcane ethanol, and alcohol-to-jet plants can be integrated with existing ethanol facilities. LanzaJet's Freedom Pines plant has demonstrated commercial production, while Gevo and other developers are planning larger facilities. Low-carbon ethanol produced with carbon capture and sustainable farming practices can further reduce lifecycle emissions, improving eligibility for incentives and creating strong long-term growth opportunities.
⮞May 2025: LanzaJet and Colombia’s BioD launched a feasibility study for a proposed SAF production plant using alcohol-to-jet technology. The project explores the potential to convert Colombia’s biomass resources into aviation fuel, creating an opportunity to diversify feedstocks and expand SAF production capacity in Latin America.
Recent Developments:
-
September 2026: Montana Renewables revised its facility expansion plans to reach sustainable aviation fuel production capacity of 200 million gallons per year by the end of 2028 at its Great Falls, Montana site, strengthening its position as North America's largest SAF producer.
-
September 2026: Arcadia eFuels signed a 10-year offtake agreement with Uniper for electrofuel-based sustainable aviation fuel from its proposed facility in Denmark, supporting compliance with synthetic fuel requirements under ReFuelEU Aviation.
Sustainable Aviation Fuel Market Key Players:
-
Neste Oyj
-
World Energy, LLC
-
Shell plc
-
TotalEnergies SE
-
OMV Aktiengesellschaft
-
BP p.l.c.
-
Enilive S.p.A.
-
Repsol S.A.
-
Moeve (formerly Cepsa)
-
Montana Renewables, LLC
-
Diamond Green Diesel LLC
-
Phillips 66
-
LanzaJet, Inc.
-
Gevo, Inc.
-
SkyNRG B.V.
-
Infinium Holdings, Inc.
-
Twelve Benefit Corporation
-
EcoCeres Inc.
-
Honeywell International Inc.
-
Topsoe A/S
Sustainable Aviation Fuel Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.34 Billion |
| Market Size by 2035 | USD 61.30 Billion |
| CAGR | 38.62% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Fuel Type: Dominant – Biofuel (94.62% share in 2025); Fastest-Growing – Power-to-Liquid (CAGR 72.48%) • By Conversion Pathway: Dominant – HEFA-SPK (82.36% share in 2025); Fastest-Growing – Alcohol-to-Jet (CAGR 58.42%) • By Blending Capacity: Dominant – Below 30% (68.42% share in 2025); Fastest-Growing – 30% to 50% (CAGR 42.36%) • By Aircraft Type: Dominant – Commercial Aviation (84.26% share in 2025); Fastest-Growing – Business & General Aviation (CAGR 41.84%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Neste Oyj, World Energy, LLC, Shell plc, TotalEnergies SE, OMV Aktiengesellschaft, BP p.l.c., Enilive S.p.A., Repsol S.A., Moeve (formerly Cepsa), Montana Renewables, LLC, Diamond Green Diesel LLC, Phillips 66, LanzaJet, Inc., Gevo, Inc., SkyNRG B.V., Infinium Holdings, Inc., Twelve Benefit Corporation, EcoCeres Inc., Honeywell International Inc., Topsoe A/S |

Frequently Asked Questions
Key players include Neste Oyj, World Energy, LLC, Shell plc, TotalEnergies SE, OMV Aktiengesellschaft, BP p.l.c., and Montana Renewables, LLC, among other global fuel producers and technology providers.
Power-to-liquid eSAF production, along with alcohol-to-jet expansion, represent the primary opportunities.
Growth is primarily driven by government blending mandates and incentives combined with airline decarbonization commitments.
By Conversion Pathway, HEFA-SPK dominated the market with approximately 82.36% share in 2025, reflecting its commercial maturity and use of waste oils and fats.
Europe dominated the market with approximately 41.26% share in 2025, driven by ReFuelEU Aviation mandates and strong refinery conversion activity.
