
Spin on Carbon Market Report Scope & Overview:
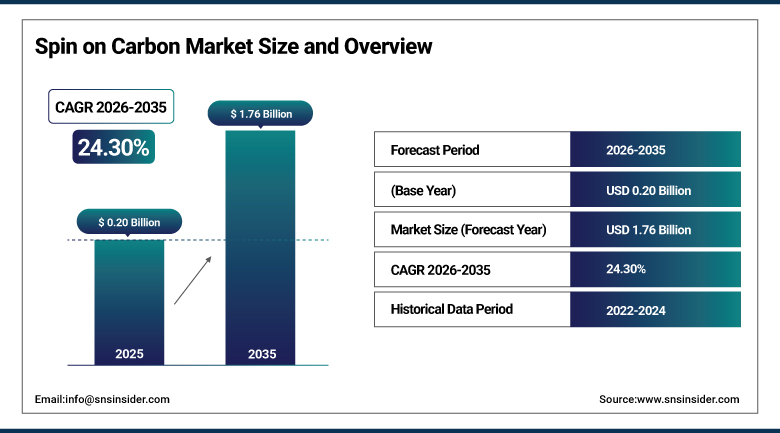
The Spin on Carbon Market size was valued at USD 0.20 Billion in 2025 and is expected to reach USD 1.76 Billion by 2035, growing at a CAGR of 24.30% from 2026-2035.
The Spin on Carbon Market covers carbon-rich liquid materials that are spin-coated onto wafers to form hardmask and planarization layers during semiconductor patterning. Spin on carbon fills gaps, flattens uneven surfaces and acts as an etch-resistant mask beneath photoresist, which is essential for multi-patterning and EUV lithography in advanced memory and logic chips. Growth is supported by chip capacity expansion, rising layer counts in 3D NAND and DRAM, and advanced packaging, while strict purity requirements, long customer qualification and concentrated suppliers shape the market.
⮞On October 14, 2024, Merck opened a spin-on-dielectric application center in Anseong, South Korea, with an investment of about USD 10.00 Billion, its second such center in Asia. The lab is meant to speed development of spin-on materials for advanced memory and logic chips, whose demand is rising with artificial intelligence.
To Get more information Spin on Carbon Market - Request Free Sample Report
Spin on Carbon Market Trends
-
Rising use of spin on carbon in EUV and multi-patterning flows at advanced nodes
-
Growth of 3D NAND and DRAM layer counts that raise hardmask consumption per wafer
-
Development of lower-bake and lower-outgassing formulations to cut energy and defects
-
Expansion of advanced packaging, which needs planarization and temporary bonding materials
-
Local supply chain building in the United States, Europe and India alongside new fabs
-
Co-development between materials makers and chipmakers through nearby application labs
U.S. Spin on Carbon Market Size Outlook
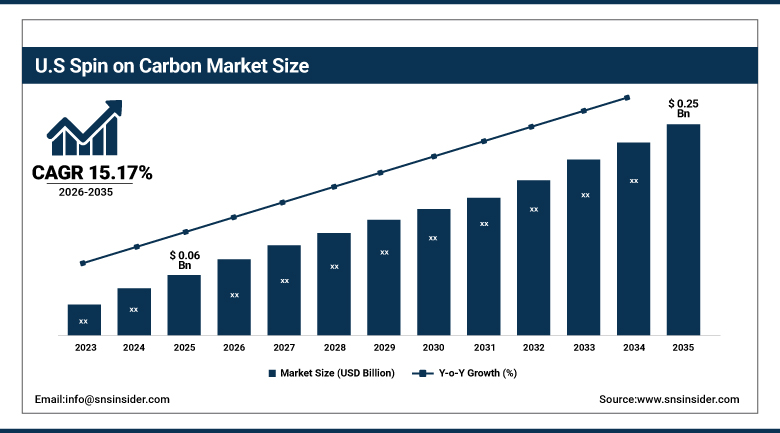
The U.S. Spin on Carbon Market was valued at USD 0.06 Billion in 2025 and is expected to reach USD 0.25 Billion by 2035, growing at a CAGR of 15.17% from 2026-2035.
The U.S. Spin on Carbon Market is led by demand from logic, memory and advanced packaging fabs in Arizona, Texas, New York, Oregon and Idaho, supported by federal incentives for local chip production. Local suppliers make materials and process chemicals, while Japanese, Korean and European producers sell through local offices and plants. Growth is moderated by long qualification times, the cost of building new fabs and reliance on imported precursors and specialty polymers.
⮞On September 23, 2025, Brewer Science opened its Arizona Innovation Center in Chandler, a new office and lab that serves as a collaborative research space and customer hub. The company says all of its research and manufacturing is carried out in the United States and that the site brings it closer to the U.S. semiconductor ecosystem.
Spin on Carbon Market Segment Analysis
-
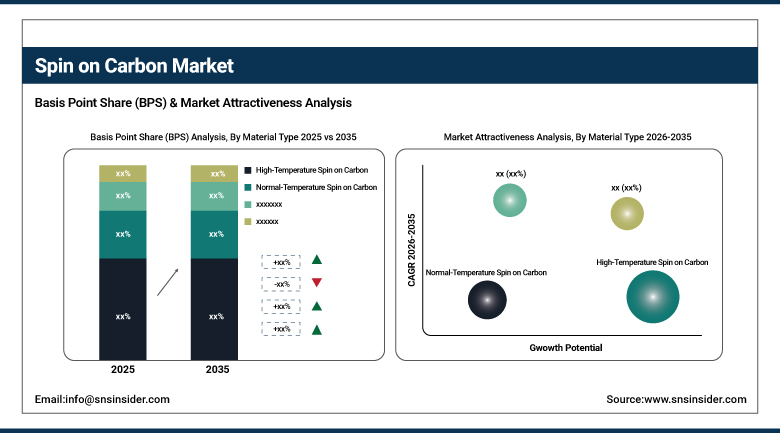
By Material Type, high-temperature spin on carbon segment dominated the Spin on Carbon Market in 2025 with an estimated 78.00% share; normal-temperature spin on carbon segment is the fastest-growing segment, with an estimated CAGR of 13.20% during 2026–2035.
-
By Application, memory devices segment dominated the Spin on Carbon Market in 2025 with an estimated 41.00% share; advanced packaging and others segment is the fastest-growing segment, with an estimated CAGR of 15.00% during 2026–2035.
-
By End User, foundries segment dominated the Spin on Carbon Market in 2025 with an estimated 52.00% share, and is also the fastest-growing segment, with an estimated CAGR of 12.30% during 2026–2035.
By Material Type, High-Temperature Spin on Carbon Dominates Spin on Carbon Market; Normal-Temperature Spin on Carbon to Register Fastest Growth.
High-temperature spin on carbon dominates the Spin on Carbon Market because films baked at high temperature offer strong etch resistance, thermal stability and low outgassing, which are required for deep etching in advanced memory and logic. Chipmakers have qualified these materials in volume production for hardmask stacks, and replacing a qualified material is slow and costly. Leading suppliers have a strong position and keep improving carbon content, film density and defect levels with each node. Close cooperation with chipmakers also lets suppliers tune each product to a specific etch recipe.
Normal-temperature spin on carbon is projected to register the fastest growth because lower bake temperatures reduce energy use, protect temperature-sensitive structures and suit advanced packaging, where wafers are bonded and thinned. Chipmakers are also seeking to cut the number of bake steps, which lowers cost and carbon emissions. Suppliers are developing formulations that approach the etch performance of high-temperature films while allowing simpler process flows. Better coating uniformity on large wafers and lower defect counts are also making these products easier to introduce.
⮞In September 2025, Brewer Science presented a technical talk at SEMICON Taiwan on a no-bake lithography process, highlighting its potential to reduce the number of baking steps required in conventional lithography workflows. The company noted that a standard process stack typically involves at least four baking steps, increasing to five when high-temperature spin-on carbon is used.
By Application, Memory Devices Dominates Spin on Carbon Market; Advanced Packaging and Others to Register Fastest Growth.
Memory devices dominate the Spin on Carbon Market because 3D NAND and DRAM manufacturing uses many hardmask layers and deep etch steps, and memory makers operate some of the largest fabs in the world. As NAND layer counts rise and DRAM moves to finer nodes, each wafer consumes more carbon hardmask. Large capacity additions in South Korea, China, Taiwan, Japan and the United States support steady purchases. Memory makers also run frequent process upgrades, which require new material grades and keep supplier teams closely involved.
Advanced packaging and other applications are projected to register the fastest growth as high-bandwidth memory, chiplets and 3D stacking require planarization, gap fill and temporary bonding layers. Power devices, sensors and photonics also use spin-on films for patterning and gap fill. Packaging houses and foundries are investing in new lines, and materials companies are developing products for thick coatings, panel-level formats and lower-temperature processing. Suppliers are also working with equipment makers on coating and cleaning tools that handle thicker films without defects.
By End User, Foundries Dominates Spin on Carbon Market and Is Also the Fastest-Growing Segment.
Foundries dominate the Spin on Carbon Market because contract manufacturers run large volumes of logic and specialty wafers for many customers and operate multiple process generations. They qualify materials from several suppliers and use them across many layers. Capacity expansions by leading foundries in Taiwan, Korea, Japan, the United States and Europe create steady demand for hardmask and planarization products. Long-term supply agreements between foundries and materials makers also help secure capacity and stabilize prices. Reliable uptime is also a key buying criterion.
Foundries are also projected to register the fastest growth as demand for artificial intelligence processors, automotive chips and specialty devices drives new fab construction. Governments are subsidizing local foundry capacity, which adds new customers for materials makers. Integrated device manufacturers remain important for memory and power devices, while outsourced assembly and test houses are growing in packaging materials. Specialty foundries serving power, sensor and automotive markets also add demand for mature-node hardmask materials. Vendors also offer technical training for new customers.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
Taiwan |
35.00 |
|
North America |
United States |
92.00 |
|
Europe |
Germany |
38.00 |
|
Latin America |
Brazil |
45.00 |
|
Middle East & Africa |
Israel |
50.00 |
North America Spin on Carbon Market Insights
North America is the second-largest region, growing at a CAGR of 10.20% during 2026-2035. The United States accounts for about 92.00% of regional demand, with Canada and Mexico adding small volumes through packaging and research activity. Brewer Science, DuPont, Entegris, Honeywell and Merck serve fabs and research centers in the region. Fabs in Arizona, Texas, New York, Oregon and Idaho are the main buyers, and Canada adds research demand through universities and photonics companies. Tight cleanroom rules also apply to every shipment.
New fabs from leading logic, memory and foundry companies, supported by federal incentives, are expanding local demand for patterning materials. Suppliers are building labs and plants near customers to shorten qualification and secure supply. Higher construction and labor costs, slow permitting and reliance on imported inputs restrain growth, but long-term commitments from chipmakers and governments provide a stable base. Industry groups, national laboratories and universities also support materials research and workforce training, which helps suppliers qualify new products with local customers more quickly.
Europe Spin on Carbon Market Insights
Europe is the third-largest region, growing at a CAGR of 9.40% during 2026-2035. Germany leads regional demand, followed by France, Italy, Ireland and the Netherlands, supported by specialty, power and automotive chip fabs and advanced research centers. Merck KGaA, Wacker Chemie and Air Products are among the suppliers with operations in the region. Ireland hosts large logic fabs, and France and Italy add demand through specialty and power chip production, while research centers in Belgium and the Netherlands develop next-generation patterning processes.
European production focuses on power devices, sensors, microcontrollers and specialty logic, which use mature and mid-range nodes. The European Chips Act supports new capacity and research, and suppliers have technical centers close to customers. Smaller fab volumes than in Asia, high energy costs and slow project approvals restrain growth, although automotive and industrial electronics provide steady demand. Collaborative research programs among universities, equipment makers and chipmakers also help European suppliers test new hardmask materials and keep a role in advanced process development.
⮞On March 18, 2026, GlobalFoundries held a groundbreaking for its EUR 1.10 billion Project SPRINT expansion in Dresden, Germany, which adds more than 110,000 wafers a year, with first tools expected in 2026.
Asia Pacific Spin on Carbon Market Insights
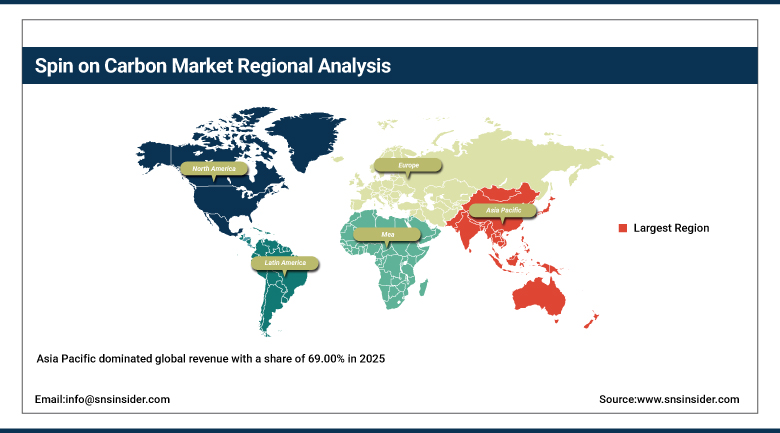
Asia Pacific dominated global revenue with a share of 69.00% in 2025, and is projected to grow at the fastest CAGR of 12.00% during 2026-2035. Taiwan accounts for about 35.00% of regional demand, followed by South Korea, China, Japan and India. JSR Corporation, Shin-Etsu Chemical, Tokyo Ohka Kogyo, Nissan Chemical, Samsung SDI, Dongjin Semichem and YCCHEM supply materials in the region. Taiwan hosts the largest foundry operations, and South Korea hosts leading memory fabs, while China is expanding local capacity and local materials suppliers.
The region hosts most of the world's memory and foundry capacity, and materials makers keep plants and labs near customers. Governments support local materials supply, and Japanese producers hold strong positions in photoresist and related chemicals. Dependence on a few suppliers, trade restrictions on critical materials and capacity concentration create risks, though continued fab investment keeps demand strong. Universities, research institutes and industry groups in the region also support training and joint development, which helps materials makers recruit skilled engineers and test new products at pilot scale.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Spin on Carbon Market Insights
In Latin America, Brazil and Mexico host small packaging, testing and electronics assembly activity, and regional demand grows at about 9.00% annually. Spin on carbon is imported through distributors and mainly supports research laboratories and limited pilot lines. Lack of leading-edge fabs, small volumes and import dependence limit growth in the region. Chile and Costa Rica add smaller activity through packaging and testing facilities, and universities in Argentina and Colombia run research programs that use small quantities of specialty process chemicals.
In the Middle East and Africa, Israel leads with fabs and design centers, followed by the United Arab Emirates and Saudi Arabia, which are exploring semiconductor investment. Regional demand grows at about 9.80% annually from a small base. Reliance on imported materials and small production volumes restrain adoption, though government programs and global fab investment may add demand later. Egypt, Turkey and South Africa add small volumes through university research and electronics assembly, and international investors are studying packaging projects in the Gulf that could create demand later.
Market Dynamics
Growth Drivers: Advanced Patterning, Memory Scaling and Fab Expansion
The main driver of the Spin on Carbon Market is the growing complexity of chip patterning. Multi-patterning and EUV lithography rely on hardmask stacks that need high etch resistance and flat surfaces, and each new node adds layers. Rising layer counts in 3D NAND and DRAM increase the amount of material used per wafer. Rising investment in artificial intelligence servers and data centers also pulls more advanced chips through fabs.
New fab construction supported by government incentives adds demand across regions. Advanced packaging for artificial intelligence processors needs planarization and bonding layers, which opens a second growth area for spin-on materials beyond front-end patterning. Government subsidies in the United States, Europe, Japan, Korea and India reduce the cost of new plants.
Restraints: Qualification Time, Purity Needs and Supplier Concentration
Chipmakers take a long time to test and qualify a new material, and any change risks yield loss, which slows adoption by new suppliers. Strict limits on metals, particles and outgassing add to development and production costs. Customer audits and process controls require suppliers to maintain strict quality systems.
A few suppliers control most of the supply, and raw material shortages or plant disruptions can affect customers. Cyclical swings in memory demand can also delay capacity additions and cut material orders. Export controls and trade tensions can also interrupt flows of materials between regions.
Opportunities: Lower-Bake Materials, Advanced Packaging and Regional Supply
Lower-bake and no-bake processes can reduce energy use and process steps, giving suppliers a way to differentiate. New formulations for EUV and high-aspect-ratio etch can capture premium pricing at leading-edge nodes. Recycling and solvent recovery programs can cut waste and appeal to chipmakers with sustainability targets.
Advanced packaging, panel-level processing and new fabs in the United States, Europe and India create demand for local supply and technical support. Co-development agreements with chipmakers can secure long-term positions on new process platforms. Emerging fab clusters in India and Southeast Asia may open new customer bases for qualified suppliers.
Recent Developments:
-
2025: Entegris announced USD 700.00 Billion in R&D spending to create a U.S. Technology Center in Aurora, Illinois. The center covers deposition materials, slurries, cleans and CMP pads.
-
2024: Shin-Etsu Chemical announced about JPY 83 billion for a new lithography materials plant in Gunma, Japan. The first phase is scheduled for completion by 2026.
Spin on Carbon Companies are:
-
Merck KGaA
-
Shin-Etsu Chemical Co., Ltd.
-
Tokyo Ohka Kogyo Co., Ltd.
-
Nissan Chemical Corporation
-
Samsung SDI Co., Ltd.
-
Dongjin Semichem Co., Ltd.
-
YCCHEM Co., Ltd.
-
Irresistible Materials Ltd.
-
Nano-C, Inc.
-
Resonac Holdings Corporation
-
DuPont de Nemours, Inc.
-
FUJIFILM Holdings Corporation
-
Sumitomo Chemical Co., Ltd.
-
Entegris, Inc.
-
Dow Inc.
-
Honeywell International Inc.
-
LG Chem Ltd.
-
Soulbrain Co., Ltd.
Spin on Carbon Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.20 Billion |
| Market Size by 2035 | USD 1.76 Billion |
| CAGR | CAGR of 24.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material Type (High-Temperature Spin on Carbon, Normal-Temperature Spin on Carbon) • By Application (Memory Devices, Logic Devices, Power Devices, Advanced Packaging, Others) • By End User (Foundries, IDMs, OSAT, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Merck KGaA, JSR Corporation, Shin-Etsu Chemical Co., Ltd., Tokyo Ohka Kogyo Co., Ltd., Nissan Chemical Corporation, Samsung SDI Co., Ltd., Brewer Science, Inc., Dongjin Semichem Co., Ltd., YCCHEM Co., Ltd., Irresistible Materials Ltd., Nano-C, Inc., Resonac Holdings Corporation, DuPont de Nemours, Inc., FUJIFILM Holdings Corporation, Sumitomo Chemical Co., Ltd., Entegris, Inc., Dow Inc., Honeywell International Inc., LG Chem Ltd., Soulbrain Co., Ltd. |

Frequently Asked Questions
Key players include Merck KGaA, JSR Corporation, Shin-Etsu Chemical Co., Ltd., Tokyo Ohka Kogyo Co., Ltd., Nissan Chemical Corporation, Samsung SDI Co., Ltd., Brewer Science, Inc. and Dongjin Semichem Co., Ltd.
Key opportunities include lower-bake and no-bake materials, advanced packaging for AI chips, and local supply near new fabs in the United States, Europe and India.
The major growth factor is the rising complexity of chip patterning, with EUV, multi-patterning and rising memory layer counts increasing hardmask use per wafer.
By Material Type, the High-Temperature Spin on Carbon segment dominated the market in 2025 with an estimated 78.00% share, supported by etch resistance and thermal stability.
Asia Pacific dominated the market with a share of 69.00% in 2025, driven by the concentration of memory and foundry capacity in Taiwan, South Korea, China and Japan.
